The promise of artificial intelligence in the financial sector has reached a fever pitch, yet the transition from theoretical budget allocation to operational reality remains a significant hurdle for most major institutions. According to the ComplyAdvantage State of Financial Crime 2026 report, while a staggering 99% of financial organizations have secured dedicated funding or established formal projects for AI-driven financial crime detection, only one-third of these entities have successfully deployed agentic solutions into live environments for transaction monitoring or identity screening. This disparity highlights a "reality gap" that is currently defining the maturation of fintech strategy.
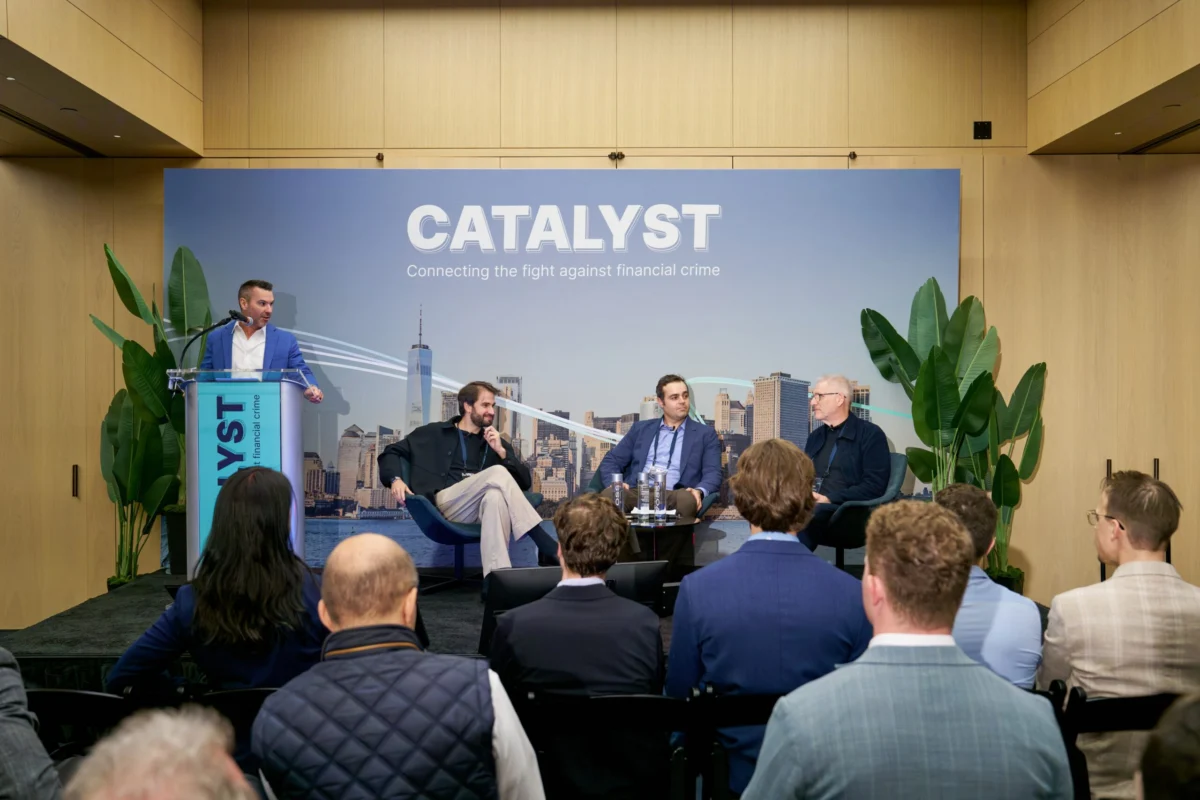
The issue took center stage on November 5, 2026, at the ComplyAdvantage CATALYST New York event. Industry leaders, including Greg Capece, Managing Director at EY, and Pedro Sanzovo, General Manager and Head of Fraud at Plaid, gathered to dissect the technological and regulatory barriers preventing widespread adoption. The consensus among these experts was clear: the effectiveness of an AI model is not defined by its complexity, but by the integrity of the data it processes and the robustness of the control environment surrounding it.
The Anatomy of Stalled Pilots
The journey from a pilot program to a production-grade system is fraught with structural challenges. Industry analysis suggests that adoption rates are heavily bifurcated by the size and age of the institution. Fintech firms and cryptocurrency exchanges, often unburdened by the technical debt of legacy infrastructure, have demonstrated the greatest agility in implementing agentic AI. Conversely, regional banks are frequently constrained by limited technical capacity, while global tier-one institutions have adopted a "build-it-ourselves" strategy that, while theoretically sound, significantly slows down deployment timelines.
Three recurring blockers consistently derail these projects:
- Data Integrity: AI models are only as reliable as their input. Firms that struggle to clean, integrate, and contextualize their data silos find it impossible to train effective models.
- Technical Architecture: The perennial "build-versus-buy" dilemma often leads to protracted procurement cycles or failed in-house developments that fail to scale.
- Governance Frameworks: Without a clear, pre-defined path for audit and compliance, even the most promising technology is often shelved by risk committees concerned with regulatory non-compliance.
"Where we’ve seen pilots successfully make it to production, the firms got the data right, they got the technology right, and they had a clear path through governance," noted Greg Capece during the CATALYST panel.
The Shifting Economics of Fraud
The rise of generative AI has fundamentally rewritten the economics of financial crime. Fraudsters are now leveraging low-cost tools to generate sophisticated fake documents and deepfakes at an industrial scale. This commoditization of forgery has rendered traditional, document-based identity verification methods increasingly obsolete.
The threat landscape has shifted from simple identity theft to intent-based fraud. First-party fraud—characterized by credit bust-outs, promotional abuse, and "friendly" fraud through chargebacks—has surged. Data from Plaid’s identity verification platforms indicates an uptick in the number of fraud attempts per identity, suggesting that bad actors are testing multiple vectors simultaneously.
In this adversarial environment, the cost of generating high-assurance data has become the new primary defense. "For a fraudster to create a bank account, farm the bank account, and run multiple legitimate transactions through it over years, it becomes really expensive," explained Pedro Sanzovo. "It’s doable, but it’s really, really expensive." Because no single data point acts as a silver bullet, modern fraud prevention requires the synthesis of disparate signals into a cohesive narrative—a task ideally suited for agentic AI, provided the system can effectively map these connections.
Regulatory Evolution: Governing by Consequence
The apprehension surrounding AI deployment is not merely technical; it is deeply rooted in the fear of regulatory reprisal. For financial institutions, the question is not "can we build this," but "can we defend this in an audit five years from now?"
This concern was addressed by the U.S. Office of the Comptroller of the Currency (OCC) on November 4, 2026, when it released its "Super Intelligence: Supervisory Framework" (Bulletin 2026-54). This document serves as a critical guide for banks navigating the integration of generative and agentic AI. The framework adopts a pragmatic approach, treating AI not as a separate risk category, but as an extension of existing model risk management and operational risk standards. It emphasizes that non-deterministic models—which may produce different outputs for identical inputs—require rigorous validation, continuous tuning, and persistent monitoring to ensure repeatable, defensible outcomes.
The OCC framework is expected to accelerate adoption among larger banks that have been waiting for "the manual" before moving beyond the sandbox phase. By providing a clear roadmap for how AI will be examined, the bulletin provides the regulatory cover necessary for risk-averse institutions to scale their programs.
Practical Takeaways for Compliance
The fraud and compliance sectors, though traditionally siloed, have much to learn from one another. Fraud teams have historically prioritized data-led, outcome-oriented strategies, whereas compliance teams have often focused on rule-based, process-driven frameworks. To close the reality gap, compliance functions must adopt the agility of fraud teams, focusing on three specific pillars:
- Measuring False Positives: Understanding the cost and impact of false positives is essential for fine-tuning AI agents. If a model is too aggressive, it risks customer churn; if it is too passive, it risks regulatory fines.
- Data-Led Decisioning: Shifting from static, rule-based screening to dynamic, data-driven analysis allows for better detection of complex, multi-layered financial crime patterns.
- Long-Term Auditability: Implementing systems that allow institutions to reconstruct the logic behind an AI’s decision is the key to surviving long-term regulatory scrutiny.
Broader Implications and Future Outlook
The industry is currently at an inflection point. The "Super Intelligence" framework represents the first major attempt by U.S. regulators to reconcile the non-deterministic nature of AI with the deterministic requirements of financial law.
As institutions transition into 2027, the success of their AI programs will be measured not by the size of their budgets, but by their ability to prove that their AI is behaving as intended under stress. The shift from "pilot" to "production" is ultimately a shift from viewing AI as a novelty to viewing it as a core component of institutional governance.
For the compliance professional, the message is clear: the technology is no longer the primary bottleneck. The ability to integrate, validate, and defend AI decisions within the context of existing regulatory standards will separate the leaders from the laggards in the coming years. Financial crime is evolving into a game of high-stakes data orchestration, and those who rely on outdated, static defense mechanisms will find themselves increasingly vulnerable to the sophisticated, AI-driven tactics of modern adversaries.
As the industry continues to digest the implications of Bulletin 2026-54, firms that prioritize transparency, rigorous validation, and data-centric strategies will be best positioned to harness the full potential of artificial intelligence while maintaining the trust and stability required by the global financial system.