The modern consumer operates in a landscape of instant digital gratification, managing banking, healthcare, retail, and communication through seamless mobile interfaces and real-time data access. Yet, a glaring anomaly persists within the financial services sector: the life insurance application process. Despite widespread technological adoption among the public, many life insurance carriers continue to rely on legacy workflows characterized by lengthy paper questionnaires, manual collection of medical histories, and persistent administrative follow-ups. This systemic disconnect creates unnecessary friction precisely when carriers should be engaging and converting prospective buyers.
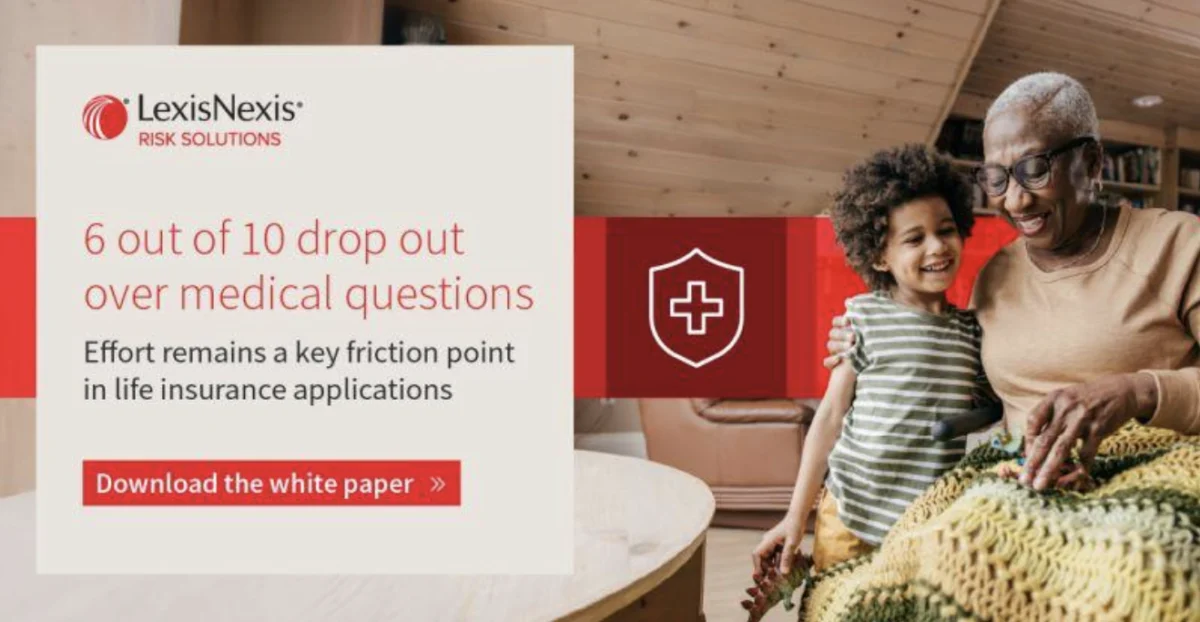
Recent findings from the LexisNexis® Life Insurance Consumer Experience Study shed light on this pressing industry challenge. Released in September 2026, the report delves deeply into applicant perceptions, identifying the specific pain points that lead to disengagement and outlining modern preferences for sharing medical data. The core takeaway from the study is both profound and urgent: consumers are significantly more digitally prepared to share their health data than the life insurance industry traditionally assumes. As insurers grapple with fierce market competition, fluctuating retention rates, and the imperative to accelerate underwriting cycles, this disconnect highlights an urgent need for structural modernization.
The Evolution of Consumer Digital Readiness in Healthcare
To understand the current friction in life insurance underwriting, one must examine how consumer behaviors regarding personal health management have transformed over the past decade. The proliferation of electronic health records (EHRs), patient portals, mobile health applications, and wearable fitness trackers has empowered individuals to take direct ownership of their medical data. Today, patients routinely review lab results, schedule appointments, and communicate with physicians through secure digital portals.
However, the traditional life insurance underwriting paradigm largely ignores this digital evolution. When an individual applies for coverage, they are frequently asked to manually recall dates of past diagnoses, list complex pharmacological histories, and endure the delays of traditional paramedical exams and attending physician statements (APS). This manual retrieval process is not only burdensome for the applicant—who may not have exact dates or medical terminology readily available—but it is also inefficient for carriers, introducing human error and extending the time-to-issue cycle.
The LexisNexis® Life Insurance Consumer Experience Study highlights that this mismatch between consumer capability and carrier process is a primary driver of policy abandonment. When applicants encounter a cumbersome application journey, drop-off rates increase exponentially. In an era where consumers expect onboarding to take minutes rather than weeks, a sluggish application process directly impacts top-line growth and placement rates for insurance providers.
Key Insights from the LexisNexis® Study
The comprehensive report offers a granular look at the friction points that plague the contemporary life insurance journey. By evaluating applicant sentiments, the study outlines several critical areas where carrier methodologies fail to meet modern expectations:
- The Willingness to Share Data Digitally: Contrary to common industry hesitation surrounding consumer privacy and digital data transmission, the study reveals a high degree of applicant comfort with leveraging digital conduits—such as patient portals—to share medical records directly with insurance carriers, provided the process is secure and transparent.
- Minimizing Administrative Burdens: Manual medical history collection not only frustrates consumers but also bogs down underwriting teams. The report explores how integrating digital medical record access can streamline workflows, significantly reducing the volume of manual follow-ups required by underwriters.
- Alignment with Consumer Habits: Modern applicants expect financial products to integrate smoothly into their digital lives. When life insurance processes mirror out-of-date administrative burdens, it creates a psychological barrier to completion.
Industry experts note that carriers utilizing advanced data analytics and streamlined digital intake forms are already capturing market share from legacy competitors. By allowing applicants to authenticate and share existing electronic health data instantaneously, forward-thinking insurers are shrinking underwriting timeframes from weeks to mere days or hours.
Background Context and Chronological Development
The friction identified in the 2026 study is the culmination of decades of conservative risk assessment practices within the life insurance sector. Historically, life insurance underwriting has been built on conservative actuarial science designed to accurately price mortality risk. For generations, this relied on physical examinations, bodily fluid testing, and exhaustive medical questionnaires verified through third-party databases like the Medical Information Bureau (MIB).
While these traditional methods successfully mitigated anti-selection and fraud, they were designed for an analog era. The first major wave of disruption began in the late 2010s with the rise of accelerated underwriting programs, which utilized predictive modeling and external data sources (such as motor vehicle records and prescription histories) to bypass physical exams for low-risk applicants. However, these initial accelerated programs often hit a wall when deeper medical history was required, forcing underwriters back into the slow lane of traditional APS retrieval.
By the mid-2020s, the widespread adoption of standardized health data exchange frameworks began to mature. Despite this technological readiness, institutional inertia, regulatory compliance complexities, and legacy IT infrastructure prevented many carriers from fully embracing direct-to-consumer digital medical data sharing. The LexisNexis® study arrives at a critical juncture in this timeline, serving as an empirical wake-up call for an industry that must pivot from theoretical digital transformation to practical, consumer-centric execution.
Industry Reactions and Strategic Implications
Market analysts and insurance executives have responded to the findings with a mix of validation and urgency. As customer acquisition costs rise across the financial services sector, optimizing the conversion funnel is paramount.
Chief Underwriting Officers (CUOs) and Chief Technology Officers (CTOs) are increasingly recognizing that the customer experience is the product during the application phase. If a carrier’s digital interface is cumbersome, applicants will seek alternative providers or abandon their search for coverage altogether, leaving families unprotected and insurers with unrealized revenue.
From a strategic standpoint, the implications of the study can be categorized into three core pillars:
- Acceleration of Underwriting Timelines: Integrating patient portals and instant electronic health record retrieval allows underwriters to access verified clinical data instantly. This eliminates the multi-week lag associated with traditional medical record collection.
- Enhancement of Placement Rates: Reducing friction directly correlates with higher completion rates. When applicants experience a frictionless, intuitive digital journey, fewer policies fall out of the pipeline between submission and issue.
- Modernization of Brand Perception: Life insurance has historically battled a perception of being opaque, intimidating, and antiquated. Adopting modern digital data-sharing practices positions carriers as innovative, customer-centric partners aligned with contemporary lifestyle expectations.
Furthermore, compliance and data security remain central to these discussions. Modern consumers demand robust data protection protocols. Insurers that can successfully combine a seamless user experience with transparent, bank-grade security standards are best positioned to earn consumer trust and loyalty.
The Path Forward for Life Insurance Carriers
The insights provided by the LexisNexis® Life Insurance Consumer Experience Study serve as both a diagnostic tool and a strategic roadmap for the industry. To remain competitive in a rapidly evolving marketplace, insurance executives must critically evaluate their current application workflows, identifying every instance of redundant data collection and administrative drag.
Embracing digital readiness requires more than simply translating paper forms into PDF documents or online portals; it demands a fundamental redesign of the underwriting workflow around the digital capabilities consumers already utilize every day. By bridging the gap between how consumers manage their health information and how carriers collect it, the life insurance industry can unlock new levels of operational efficiency, improve placement metrics, and deliver an experience that truly meets the expectations of the modern digital applicant.
For industry professionals seeking a deeper dive into these findings, the complete research offers extensive data and strategic recommendations. Stakeholders are encouraged to review the complimentary LexisNexis® Life Insurance Consumer Experience Study, accessible via the official LexisNexis Risk Solutions Insights and Resources portal, to better understand how to align their underwriting strategies with the demands of today’s digitally empowered consumer.