Artificial Inu, currently trading under the ticker $AI, has emerged as the most prominent stock-paired memecoin on the Robinhood Chain, functioning as the primary vehicle for tokenized Nvidia exposure within the ecosystem. The asset’s liquidity pool currently holds 8,783 $NVDA tokens, representing approximately 16.2% of the entire on-chain float of tokenized Nvidia shares. This structure is indicative of a broader trend: as retail interest in the Robinhood Chain’s tokenized equity offerings grows, memecoin developers are increasingly bypassing traditional stablecoin pairs in favor of direct equity-token pairings. When users purchase these dog-themed assets, routing protocols prioritize the equity wrapper to secure liquidity, effectively turning every trade into a standing bid for the underlying stock token.
The Evolution of Robinhood Chain and Asset Tokenization
Launched in July 2026, the Robinhood Chain was designed as an Arbitrum Orbit Layer 2 network specifically optimized for tokenized equities. Utilizing Uniswap v4 as its primary Automated Market Maker (AMM), the chain allows for the issuance of ERC-20 debt securities by a Robinhood subsidiary. These tokens track real-world share prices without conferring direct ownership, maintaining a strict exclusion policy for U.S. retail investors while allowing for frictionless, global peer-to-peer transfers.
The rapid shift toward equity-paired memecoins began in mid-July, shortly after the chain’s inception. Platforms such as Long, Bankr, Flap, and PAIR industrialized the process of pairing new tokens with equity wrappers. By late August, the ecosystem had moved beyond simple $TOKEN/$USDC pairings. Instead, the standard for new project launches on the chain became the "Equity-Quote" model, where liquidity pools are denominated in assets like $NVDA, $AAPL, or $SPY. This model has effectively transformed equity wrappers into the base layer of liquidity for the chain’s burgeoning memecoin economy.
Market Dynamics: A Quantitative Analysis
A comprehensive data audit conducted at block 51,651,897, recorded at approximately 10:30 UTC on September 1, 2026, reveals the extent of this phenomenon. Across 19 of the most liquid stock tokens on the network, researchers identified 432 active liquidity pools where a tokenized equity served as the quote asset. These pools collectively held $8.84 million worth of stock tokens against a total on-chain float of $51.5 million, meaning roughly 17.2% of all equity tokens on the chain are currently locked in memecoin pools.
The impact on trading volume is even more pronounced. Over the 24-hour period preceding the audit, these pools facilitated $95.3 million in volume out of a total $304.1 million traded across the 19 tracked tickers, accounting for 31.3% of total activity. While these figures represent a lower bound—given the limitations of on-chain data scraping and the rapid turnover of pool liquidity—they underscore a structural reality: memecoin trading is now the dominant use case for tokenized equities on the Robinhood Chain.
Chronology of the Memecoin-Equity Pairing Trend
The transition toward these pairings followed a clear, iterative timeline:
- July 14, 2026: The Long platform enters the ecosystem, pioneering the selection of stock tokens as pricing assets for new token launches.
- July 20, 2026: Bankr launches with a wider scope, supporting over 90 tickers and explicitly marketing the concept of pools denominated in tech stocks rather than traditional stablecoins.
- Late July 2026: The "Stocks Vault" model is introduced by Flap, where memecoin fee revenue is redirected into a treasury that accumulates a "drip" of real-world equity tokens for holders.
- August 29, 2026: PAIR enters the market, introducing "multipool" RWA launchpads that allow new tokens to be quoted against baskets of multiple stock tokens, signaling a move toward more complex financial products.
- September 1, 2026: The announcement of "LongX" and $NVDA3x, a 3x leveraged perpetual position that functions as an ERC-20 token, marks the transition toward using complex derivative wrappers as the foundational quote asset for memecoins.
The Logic of the Vault and Fee Accumulation
The popularity of this format is rooted in its economic incentive structure. Developers of projects like Artificial Inu have argued that pairing against an equity creates a "deflationary" and "value-accumulating" asset. In the case of $AI, transaction fees are paid in $NVDA, with the majority of these tokens locked in a community vault. The project claims that this creates a permanent, growing claim on the underlying equity, effectively tying the long-term success of the memecoin to the accumulation of real-world corporate assets.
This mechanism has proven highly lucrative for the underlying infrastructure. Uniswap v4, serving as the backbone for these pools, reported $6.5 million in fees during a single 24-hour period, a significant portion of the $14.3 million generated across the entire Robinhood Chain.
The Weekend Squeeze: Fragility in the System
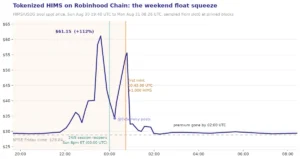
The most significant risk inherent in this model was exposed during the final weekend of August 2026. A memecoin project, utilizing the $HIMS tokenized equity as its liquidity pair, absorbed a substantial portion of the available float. Because the equity issuer operates on a standard Monday-to-Friday issuance schedule, the supply of $HIMS became inelastic over the weekend.
As demand for the memecoin spiked, the price of the $HIMS wrapper decoupled from its NYSE-listed spot price, surging by as much as 112% as traders scrambled to provide liquidity to the pool. The premium only evaporated once the issuer resumed minting operations on Monday, diluting the localized supply spike. This "weekend premium" phenomenon serves as a stark reminder of the risks when retail-driven, 24/7 crypto markets interact with traditional, gate-controlled equity issuance. Analyst @0xSammy noted that "user growth is currently outrunning available on-chain float," highlighting that the current infrastructure lacks the capacity to bridge the gap between weekend demand and weekday supply.
Broader Implications and Future Outlook
The rise of equity-backed memecoins has created a unique, if unintended, financial environment. While proponents argue that this is the natural evolution of "tokenized RWA" (Real World Assets), critics point out that the mechanism ends at the wrapper. Cornering the supply of a tokenized $HIMS or $NVDA share on the Robinhood Chain does not influence the price of the actual shares on the New York Stock Exchange. The wrapper is a debt security, and its volatility is largely contained within the ecosystem.
Furthermore, the "namespace collision" issue has become a growing concern for investors. On the Robinhood Chain, tickers like $GME and $NVDA are often co-opted by memecoin projects. A user searching for a ticker might inadvertently purchase a joke token rather than the equity wrapper they intended. This requires a level of diligence that many retail participants currently lack.
As the ecosystem approaches the expiration of its 90-day gas subsidy in early October, the sustainability of this model remains an open question. Many of these pools have never operated in a high-cost environment where every trade must cover gas fees. If the "fee-insensitive churn" that currently characterizes much of the volume dries up, the vaults that are supposed to hold these accumulated equity tokens will face their first true test of viability.
For now, the Robinhood Chain represents a frontier where the speed of decentralized finance and the weight of traditional equity markets collide. While the current primary use case remains speculative, the volume of capital being funneled into these equity-backed pools suggests that the marriage of memecoin liquidity and traditional assets is a trend that is likely to persist, albeit with significant structural risks for the unwary participant.