Emerging risks rarely arrive fully formed; they evolve at the volatile intersection of rapid technological innovation and systemic uncertainty. As industries accelerate their adoption of quantum computing, hyperscale data infrastructure, and advanced peptide therapeutics, they are inadvertently creating a new generation of exposure vectors. For the insurance sector, the primary challenge lies not merely in tracking these emerging technologies but in quantifying how they translate into tangible liabilities, operational disruptions, and systemic shocks. As these breakthroughs transition from theoretical potential to commercial reality, the insurance industry must recalibrate its underwriting strategies to avoid being blindsided by the next generation of loss events.
The Quantum Computing Trajectory and Emerging Liability
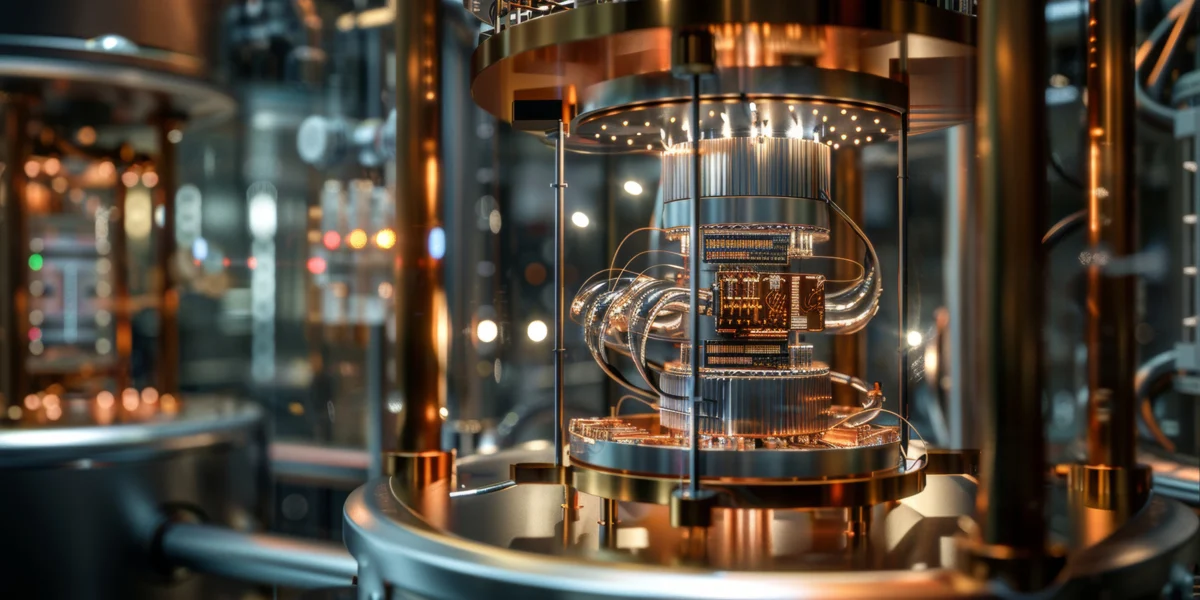
While artificial intelligence currently dominates the technological discourse, quantum computing represents a more fundamental, albeit slower-moving, paradigm shift. Traditional computers operate using classical bits—binary units representing either a 0 or a 1. Quantum computers, by contrast, utilize quantum bits, or "qubits," which leverage the principles of superposition and entanglement to exist in multiple states simultaneously. This capability allows for computational power that could solve problems currently deemed impossible for even the world’s most advanced supercomputers.
The economic footprint of this sector is expanding rapidly. Valued at approximately $1.45 billion in 2024, the industry is projected to reach $2.2 billion by 2027. However, the commercialization of this technology introduces immediate property and casualty (P/C) exposures. The transportation of highly sensitive, cryogenic-cooled quantum hardware creates unique inland marine risks, while the intense pressure on startups to secure venture capital often leads to aggressive financial disclosures. Consequently, directors and officers (D&O) liability is becoming a focal point, as any misalignment between projected capabilities and actual technical delivery could trigger shareholder litigation.
The most significant long-term risk, however, is the arrival of "Q-Day"—the moment a cryptographically relevant quantum computer becomes powerful enough to break existing public-key encryption standards. While estimates for this event range from 2029 to several decades out, the mere prospect is forcing a massive transition to "post-quantum" cryptography (PQC). For organizations, the failure to transition systems to PQC standards in a timely manner is already being analyzed by legal scholars as a potential failure of fiduciary duty. Should a major data breach occur post-Q-Day, companies that neglected to update their cryptographic protocols may face significant negligence claims, potentially testing the limits of cyber insurance coverage.
The Hyperscale Data Center Boom and Infrastructure Strain
The infrastructure supporting the AI and quantum revolutions—the modern data center—is currently experiencing a period of unprecedented investment. Driven by the computational demands of large language models and cloud processing, data center construction spending reached $46.5 billion in the first quarter of this year, a massive increase from the $7.3 billion recorded during the same period in 2025. This surge, however, is not without severe friction.
The rapid scaling of these facilities has run into the hard realities of physical infrastructure limitations. Nearly 50% of planned projects face delays or outright cancellation. The primary culprits include power grid interconnection backlogs, localized permitting failures, and significant community pushback. Recent surveys indicate that 70% of the American public opposes the siting of AI-focused data centers within their local municipalities, citing concerns over water consumption, noise pollution, and the strain on local electrical grids. This public opposition resulted in the cancellation of 25 major projects last year alone.
From an insurance perspective, these delays represent a complex web of commercial risk. Projects that stall after initial capital expenditure face significant contractual disputes between developers, contractors, and local governments. Furthermore, the specialized nature of these builds has created a "talent vacuum," with 58% of data center managers reporting that they cannot fill critical technical roles. A lack of skilled oversight during the construction and commissioning phases increases the probability of structural defects or operational failures, creating new avenues for professional liability and construction risk insurance.
Peptide Therapeutics: The New Frontier of Pharmaceutical Liability
The rise of peptide-based pharmaceuticals, particularly the success of GLP-1 agonists, has revolutionized the weight-loss and metabolic health industry. With nearly 100 peptide-based drugs currently approved globally, the pharmaceutical industry has found a potent new mechanism for disease management. However, the commercial success of these drugs has also spawned an unregulated "shadow market" of peptide products marketed directly to consumers through social media, wellness clinics, and telehealth platforms.
The danger lies in the distinction between FDA-approved therapies and the proliferation of "research chemicals." Many products sold online are labeled as "not for human consumption," yet they are being actively promoted by influencers for weight loss, cosmetic enhancement, and performance optimization. This gray market creates a hazardous liability landscape. Insurers are now evaluating the potential for bodily injury claims stemming from contaminated or mislabeled substances, as well as the liability exposure of telehealth companies and compounding pharmacies that facilitate the distribution of these substances outside of rigorous clinical oversight.
Legal experts warn that the marketing practices surrounding these peptides—specifically, the use of unsubstantiated health claims—could lead to a wave of litigation similar to the opioid crisis. The potential for long-term health complications arising from unverified, impure, or improperly dosed peptides poses a significant risk to product liability insurers. As these products become more accessible, the likelihood of a high-profile class-action lawsuit against distributors and marketers grows, necessitating a more stringent approach to pharmaceutical and professional liability underwriting.
Chronology of Emerging Risk Evolution
- 2024: Global quantum computing revenue hits $1.45 billion; the surge in AI data center investment causes grid instability in major tech hubs.
- 2025: Data center project cancellations spike as public opposition and power constraints force developers to abandon 25 major sites.
- 2026–2027: Projected growth of the quantum industry to $2.2 billion coincides with the first waves of regulatory pressure regarding post-quantum cryptographic standards.
- 2028–2030 (Anticipated): As the window for Q-Day narrows, the insurance industry expects a shift in cyber policy language, with potential exclusions for non-compliant cryptographic systems.
- Ongoing: The proliferation of non-prescription peptides continues to trigger localized health incidents, prompting potential regulatory crackdowns on compounding pharmacies and telehealth distribution models.
Analytical Implications for the Insurance Sector
The common denominator across these three trends is the rapid transition from experimental technology to systemic dependency. Quantum computing, while still in its infancy, demands a proactive adjustment to cyber liability policies. Hyperscale data centers, while necessary for global connectivity, present a volatile mix of construction and operational risk. Peptide therapeutics, while a medical breakthrough, have created a dangerous regulatory loophole in the wellness industry.
For insurers, the imperative is to move beyond traditional actuarial models that rely solely on historical loss data. Because these risks are emergent, they require a forward-looking, qualitative approach that incorporates engineering analysis, geopolitical monitoring, and regulatory forecasting. The potential for "cascading failures"—such as a data center failure causing a massive supply chain disruption, or a widespread health crisis linked to unregulated peptides—suggests that systemic risk management must be prioritized.
In summary, the insurance industry is currently standing at the threshold of a new era of risk. As these breakthroughs continue to gain momentum, the gap between traditional coverage and modern exposure will widen. By engaging with these developments now, the insurance industry can shift from a reactive posture to a proactive role as a stabilizer of global innovation, ensuring that when the risks associated with these breakthroughs manifest, the market is prepared to absorb the shock rather than being defined by it. The proactive integration of these technological and health-related risks into underwriting strategies will be the defining competitive advantage for insurers in the coming decade.