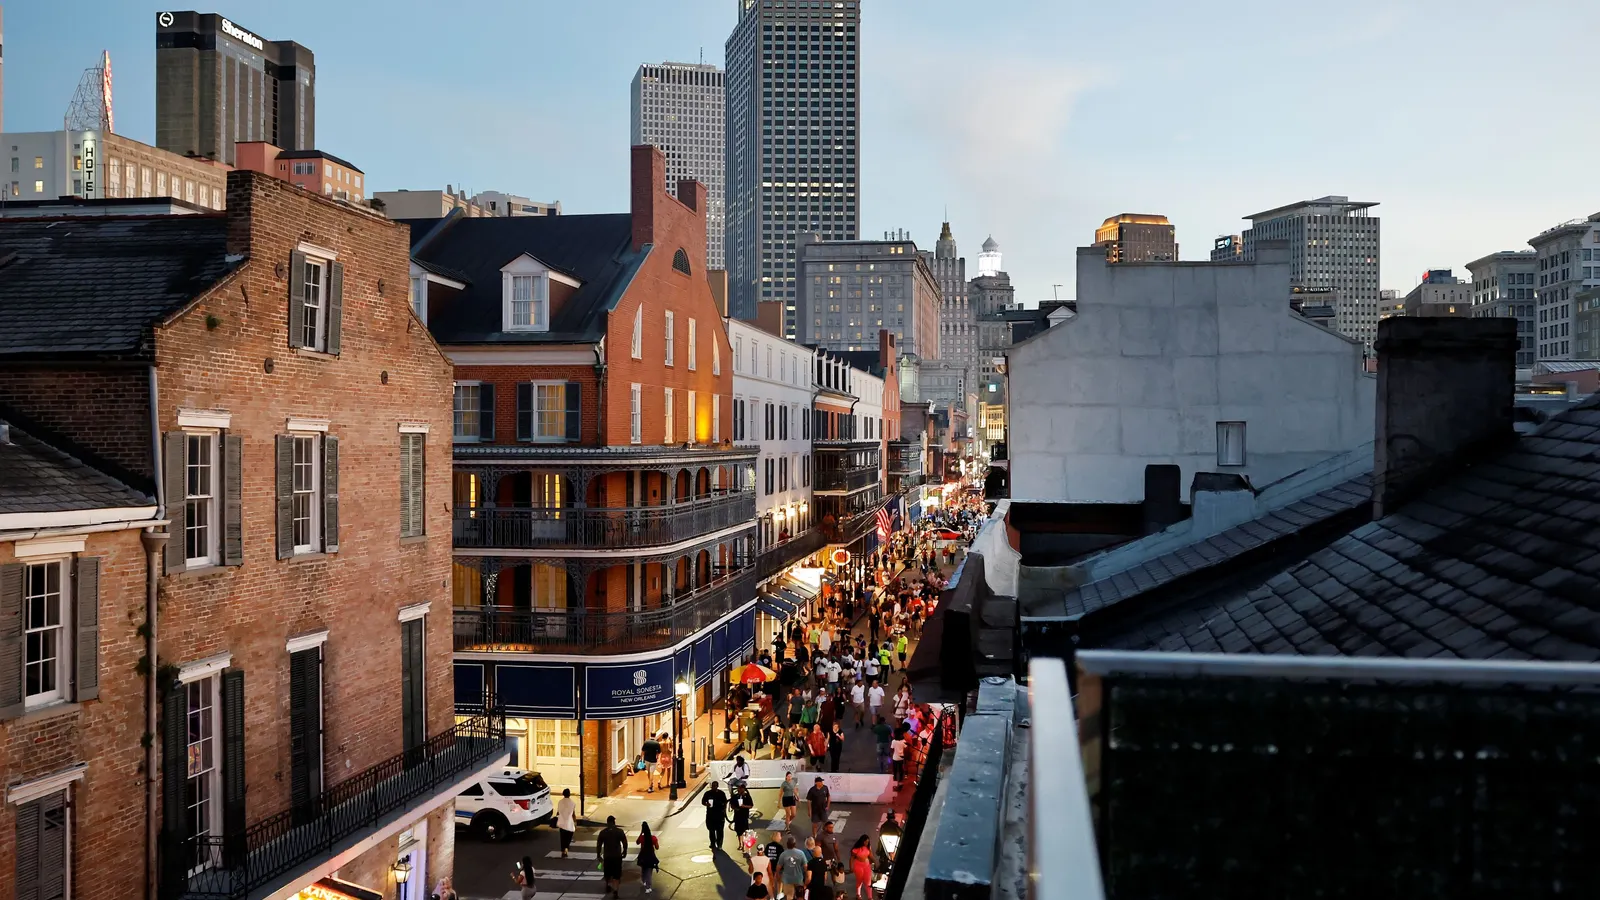
The financial sector in New Orleans reached a significant milestone this September with the official opening of Nola Bank, the first new commercial lender to launch in the city in over a decade and a half. Following years of regulatory preparation and capital acquisition, the institution opened its doors on September 14, marking a departure from a long-standing trend of regional consolidation that has dominated the Louisiana banking market since the mid-2000s. The arrival of Nola Bank, the eighth de novo institution to launch in the United States this year, represents a strategic effort to reintroduce localized decision-making to a market that has become increasingly defined by large, centralized regional and national financial entities.
The launch follows final regulatory approval granted on September 11, concluding a rigorous vetting process by both the Federal Deposit Insurance Corporation (FDIC) and the Louisiana Office of Financial Institutions. With $29.2 million in initial capital raised from a diverse pool of 78 investors—many of whom are local entrepreneurs—the bank enters the market with a specific mission to address the needs of the underbanked and the local small business community.
A Historical Context of Consolidation and Resilience
To understand the necessity of Nola Bank, one must look back at the economic trajectory of New Orleans in the early 21st century. The aftermath of Hurricane Katrina in 2005 fundamentally altered the city’s economic structure. The physical destruction of the storm was compounded by long-term demographic shifts, as significant portions of the population relocated permanently. This exodus, combined with the subsequent economic volatility, created a climate of instability that stifled the formation of new banks.
For years, the local banking environment followed a "consolidate or be acquired" model. CEO Joe Omner notes that the industry phrase "Ain’t dere no more"—a local colloquialism regarding the disappearance of once-familiar landmarks—aptly describes the fate of many independent community banks in the region. These institutions were frequently absorbed by larger regional entities, resulting in a market where the top-tier institutions are dominated by national players.
Current FDIC data from June 2026 highlights the extent of this concentration. Capital One, which solidified its regional dominance by acquiring the New Orleans-based Hibernia National Bank in 2005, currently commands the largest deposit market share in the city at approximately 35%. Other major players, such as Gulfport-based Hancock Whitney Bank and New York-based JPMorgan Chase, each hold roughly 21% of the deposit market. Smaller entities like First Horizon Bank and the local Gulf Coast Bank and Trust Company maintain shares of 8% and 4%, respectively. This landscape, dominated by institutions with centralized, often out-of-state decision-making processes, left a perceived vacuum in the market for personalized, community-centric commercial lending.
The De Novo Process and Regulatory Environment
The journey to establish Nola Bank was a complex undertaking that spanned several years. The "de novo" process—the creation of a new, state-chartered bank from the ground up—is notoriously difficult, requiring substantial capital, a robust business plan, and strict adherence to post-launch performance metrics. Nola Bank’s ability to secure the necessary funding where other groups had failed is attributed to a mission-driven approach that resonated with local investors.
The bank is currently in the process of applying for Minority Depository Institution (MDI) status with a multiracial designation. This status is not merely a label; it carries significant functional benefits. Under the Community Reinvestment Act (CRA), larger lenders can earn credits by partnering with MDIs, which in turn provides the smaller bank with a steady stream of collaborative opportunities. Furthermore, MDI status opens doors to specific federal and state-funded programs designed to promote financial literacy and expanded credit access in underserved populations.
Henry L. Coaxum Jr., who chairs the bank’s board, has overseen a governance structure that reflects the community the bank intends to serve. With a board composed primarily of racial minority individuals and an investor base where over half are business owners, Nola Bank is positioned to act as a financial anchor for local enterprises that may have felt alienated by the impersonal underwriting algorithms of larger, national banks.
Operational Strategy: The Speedboat Model
According to Chris Shah, Nola’s chief banking officer, the bank’s competitive edge lies in its agility and responsiveness. Using an analogy often cited by CEO Joe Omner, Shah contrasts the local lender with its larger competitors: "Big banks are like barges that take miles to turn around. We are a speedboat."
This operational philosophy is intended to solve a common pain point for small business owners: the distance between the borrower and the decision-maker. At major national banks, underwriting is often centralized, meaning the loan officer meeting the client has little say in the final approval process, which is instead handled by a committee or an automated system in a different state. Nola Bank plans to counter this by ensuring that its decision-makers are physically present and accessible. By keeping underwriting local, the bank claims it can better assess the "character" of a borrower and the unique dynamics of the New Orleans economy, factors that are often overlooked by national institutions relying strictly on data-driven models.
Technology and Regulatory Compliance
Despite its focus on traditional community banking, Nola Bank is not eschewing modern technological requirements. Recognizing that a digital presence is mandatory for survival in the current financial climate, the bank has partnered with Jack Henry & Associates to provide its core technology and digital banking platforms. Shah emphasizes that for the bank to effectively serve the underbanked and small business sectors, its digital capabilities must be on par with, if not superior to, the regional incumbents.
"Community banks can compete now because technology is going so far," Omner stated during a recent interview. By leveraging modern tech stacks, Nola Bank intends to offer high-end service without the bureaucratic overhead that plagues larger institutions.
However, the bank remains under strict regulatory scrutiny. As a condition of its charter, Nola Bank is required to maintain a Tier 1 leverage ratio of at least 8% for its first three years of operation. This is a common safety measure for new institutions, ensuring that they maintain sufficient capital to absorb potential losses during their vulnerable formative period. Despite these hurdles, the leadership team has expressed gratitude toward the FDIC and the Louisiana Office of Financial Institutions, noting that both regulatory bodies were responsive and supportive throughout the lengthy application process.
Broader Economic Implications for New Orleans
The launch of Nola Bank serves as a litmus test for the economic vitality of New Orleans. If successful, the bank could catalyze a broader trend of "re-banking" the city, where capital is circulated more effectively within the local economy rather than being siphoned off by national corporations.
The implications of this move are twofold. First, it addresses the "banking desert" phenomena often found in specific urban neighborhoods where large banks have shuttered branches to reduce overhead. By maintaining a physical presence and an active interest in the local economy, Nola Bank aims to provide the foundational infrastructure required for economic growth in these areas. Second, it highlights the changing attitude of federal regulators. The recent efforts by the FDIC to streamline the de novo application process—a sentiment echoed by Omner—suggest that there is a growing recognition at the federal level that community banks are essential for maintaining a healthy, competitive financial ecosystem.
Looking Ahead
As Nola Bank begins its first year of operation, the focus will be on loan portfolio quality and building trust within the community. The bank’s commitment to "knowing the borrower" will be tested as it navigates the complexities of the New Orleans market. Whether the institution can maintain its "speedboat" agility while scaling its operations remains to be seen.
The success of Nola Bank will likely be measured not just by its deposit growth or its Tier 1 leverage ratio, but by its ability to foster relationships that the larger, regional incumbents have arguably neglected. By combining modern technology with a traditional, relationship-based approach to finance, the bank is attempting to bridge a gap that has existed in New Orleans for sixteen years. For a city that has fought hard to redefine its identity in the 21st century, the emergence of a locally owned, community-focused lender is a development that many analysts will be watching closely as a indicator of the region’s long-term economic resilience and potential for independent growth.