The passage of Amendment 3, a constitutional change narrowly approved by Florida voters this past Tuesday, marks a significant pivot in the state’s fiscal strategy. By expanding the homestead exemption for primary residences from $50,000 to $150,000 effective next year, and scaling it to $250,000 by 2028, the measure seeks to offer immediate relief to homeowners grappling with rising inflation and housing costs. However, the economic reality of the Sunshine State suggests that this relief may come at a hidden price: a potential degradation of the municipal services that keep insurance premiums from spiraling even further out of control.
A Fiscal Gamble in a High-Risk Environment
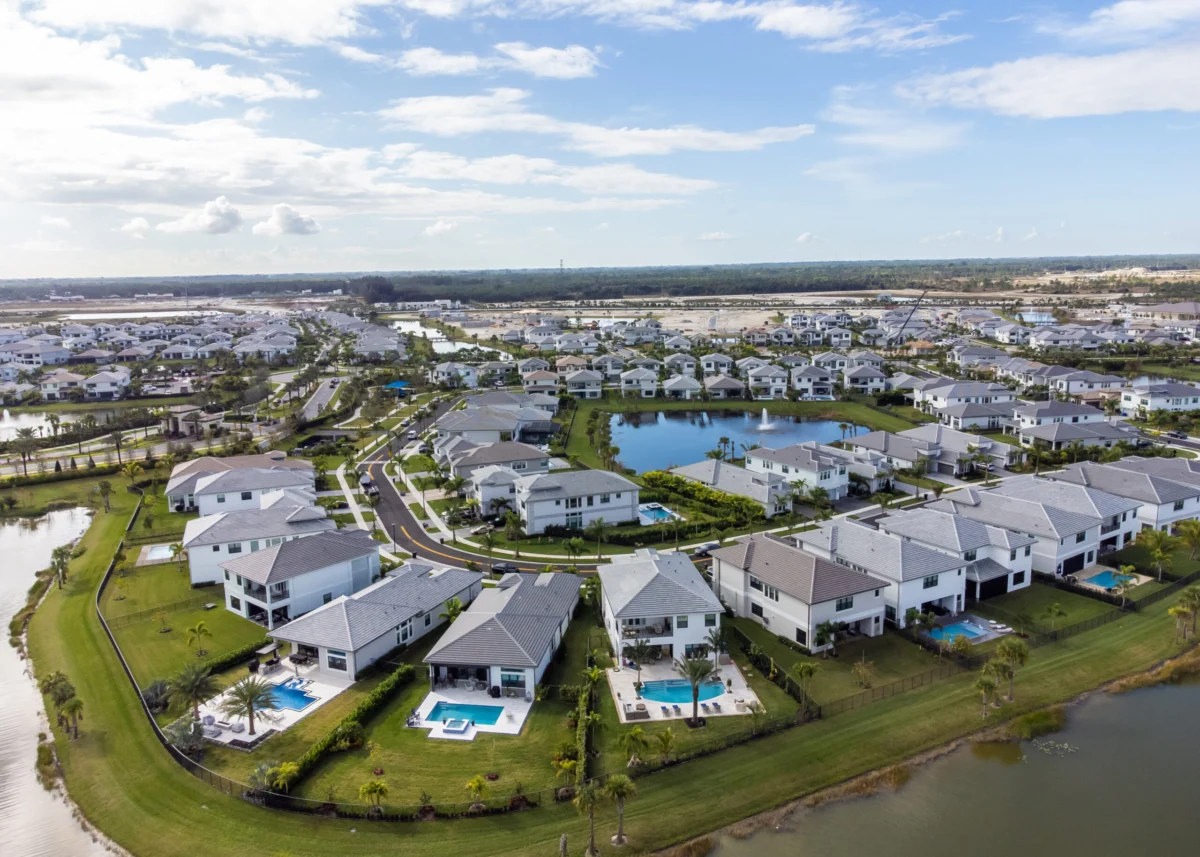
Florida occupies a unique position in the American insurance landscape. With its extensive coastline and vulnerability to catastrophic weather events—ranging from Category 5 hurricanes to chronic flooding—the state’s property insurance market is already the most expensive in the nation. According to recent industry data, the average annual premium for home insurance in Florida is significantly higher than the national average, a trend driven by the compounding effects of climate change and aggressive litigation environments.
While property taxes in Florida have risen sharply in recent years, they remain middle-of-the-road in a national context. The mean effective rate on owner-occupied homes currently ranks 27th among U.S. states. Proponents of Amendment 3, including Governor Ron DeSantis and the influential trade group Florida Realtors, argued that the tax cut was essential to combat the rising cost of living. Chuck Bonfiglio Jr., president of Florida Realtors, championed the measure as a victory for the "middle-class homeowner," asserting that the state could implement these cuts without compromising essential community services.
The Math Behind the Mandate
The fiscal impact of the amendment is substantial. Florida TaxWatch, an independent, nonpartisan research organization, has projected that the measure will strip tens of billions of dollars from the coffers of counties, cities, and special districts over the first five years of implementation. Because the amendment excludes school taxes, the burden of the shortfall falls squarely on local municipal budgets—the very budgets that fund fire departments, police, building code enforcement, and infrastructure maintenance.
The chronology of this legislative push began with the state legislature’s desire to address housing affordability without implementing broad-based rent controls or state-funded housing subsidies. The ballot measure, which required a 60% supermajority to pass, cleared the threshold by a razor-thin margin. Critics, including former Republican state senator Jeff Brandes, have characterized the move as a dangerous fiscal experiment. "Florida passed Amendment 3. The governor and the Legislature own what comes next," Brandes noted on social media, emphasizing that the burden of managing the potential collapse of local funding now rests entirely on the state’s leadership.
The Direct Link Between Municipal Services and Insurance Rates
The connection between tax revenue and insurance premiums is not merely theoretical; it is deeply embedded in the actuarial science of the insurance industry. Insurers rely heavily on the Insurance Services Office (ISO) ratings to determine the risk profiles of specific communities. These ratings, which range from 1 to 10, evaluate the efficacy of local fire protection, water supply infrastructure, emergency communications, and the density of fire stations.
"A reduction in fire protection services in a community can lead to a lower ISO rating," explained Mark Friedlander, a spokesperson for the Insurance Information Institute. "The ISO rating is among numerous risk factors property insurers use to underwrite homes in Florida and could potentially cause premiums to increase if the rating is downgraded."
If a city like Dunedin—which has already initiated contingency planning for potential firefighter staffing reductions—is forced to cut its budget, the resulting decline in fire response times could lead to a poorer ISO rating. When a community’s ISO rating drops, insurance companies are mathematically justified in raising premiums for every policyholder in that jurisdiction, effectively neutralizing the savings homeowners gained from the tax cut.
Economic Displacement and the Shifting Tax Burden
Beyond the immediate risk of insurance hikes, the structural change to the tax code creates a "shell game" of revenue. As municipalities face a massive budget hole, they are legally constrained in how they can bridge the gap. Experts in urban planning and fiscal policy suggest that local governments will likely turn to alternative revenue streams to maintain basic operations.
"You ostensibly are going to pay for living in a high-risk area, either as a taxpayer or as a ratepayer," said Jesse Keenan, a professor of sustainable real estate and urban planning at Tulane University. "It’s just shifting the burden."
This shift is likely to manifest in several ways:
- Increased Fees and Assessments: Municipalities may increase "impact fees" for new developments or implement special assessments for services like trash collection, stormwater management, and emergency medical services.
- Sales Tax Hikes: Local governments may seek voter approval for additional local-option sales taxes, which are regressive in nature and hit lower-income residents harder than property taxes.
- The "Rental Pass-Through": While the homestead exemption protects primary residences, it does not apply to rental properties. Landlords, faced with the same municipal service cuts and potential property tax fluctuations, are likely to pass any increased costs—or the cost of rising insurance premiums—directly to tenants in the form of higher monthly rents.
The Long-Term Mitigation Crisis
Perhaps the most overlooked implication of the amendment is its impact on long-term climate resilience. Building safety codes, rigorous inspections, and land-use planning are the primary defenses against the increasing intensity of Florida’s hurricane seasons. These functions are almost exclusively funded through local property taxes.
As Professor Keenan noted, the reduction in tax revenue will inevitably impair local governments’ ability to make investments in risk reduction. This includes everything from upgrading storm drains to meet modern flood standards to employing a sufficient number of building inspectors to ensure that new construction can withstand high-velocity winds. If these preventative measures are sacrificed at the altar of tax relief, the long-term cost of property damage will inevitably rise, further straining the already fragile state-backed insurance markets.
The Path Forward: Uncertainty for Localities
For now, the situation remains in flux. The Florida Association of Counties has signaled a cautious approach, with deputy executive director Cragin Mosteller stating that local governments are committed to protecting the quality of life for residents while navigating the fiscal transition. However, the lack of a clear directive from the Governor’s office regarding how municipalities should compensate for the shortfall has left many local officials in a state of limbo.
As the 2026 fiscal year approaches, the eyes of the state will be on cities like Dunedin and others that are currently drafting contingency budgets. The success or failure of Amendment 3 will not be measured merely by the immediate relief felt on individual tax bills, but by the downstream stability of the state’s insurance market and the continued viability of the essential public services that safeguard Florida’s built environment.
While the political victory of the tax cut is complete, the economic consequences are only beginning to unfold. The state now enters a period of fiscal adjustment where the promise of lower taxes faces the harsh reality of insurance math and the rising cost of climate-related risks. Whether the legislature can provide the necessary guardrails to prevent a cascade of rising premiums remains the defining question of Florida’s economic future.