The landscape of automotive insurance claims has reached a critical inflection point in 2026, characterized by a stark divide between the experiences of policyholders dealing with total loss scenarios and those managing repairable vehicle claims. According to the J.D. Power 2026 U.S. Auto Claims Satisfaction Study, customer satisfaction regarding total loss claims has plummeted for the third consecutive year, suffering a 12-point drop on a 1,000-point scale. This downward trajectory represents a cumulative 46-point decline since 2023, signaling systemic friction in how insurers handle vehicles deemed beyond economic repair. Conversely, the industry has seen a modest improvement in satisfaction for repairable vehicle claims, which rose by four points, keeping the overall industry satisfaction index stagnant at 700.
The Rising Prevalence of Total Losses
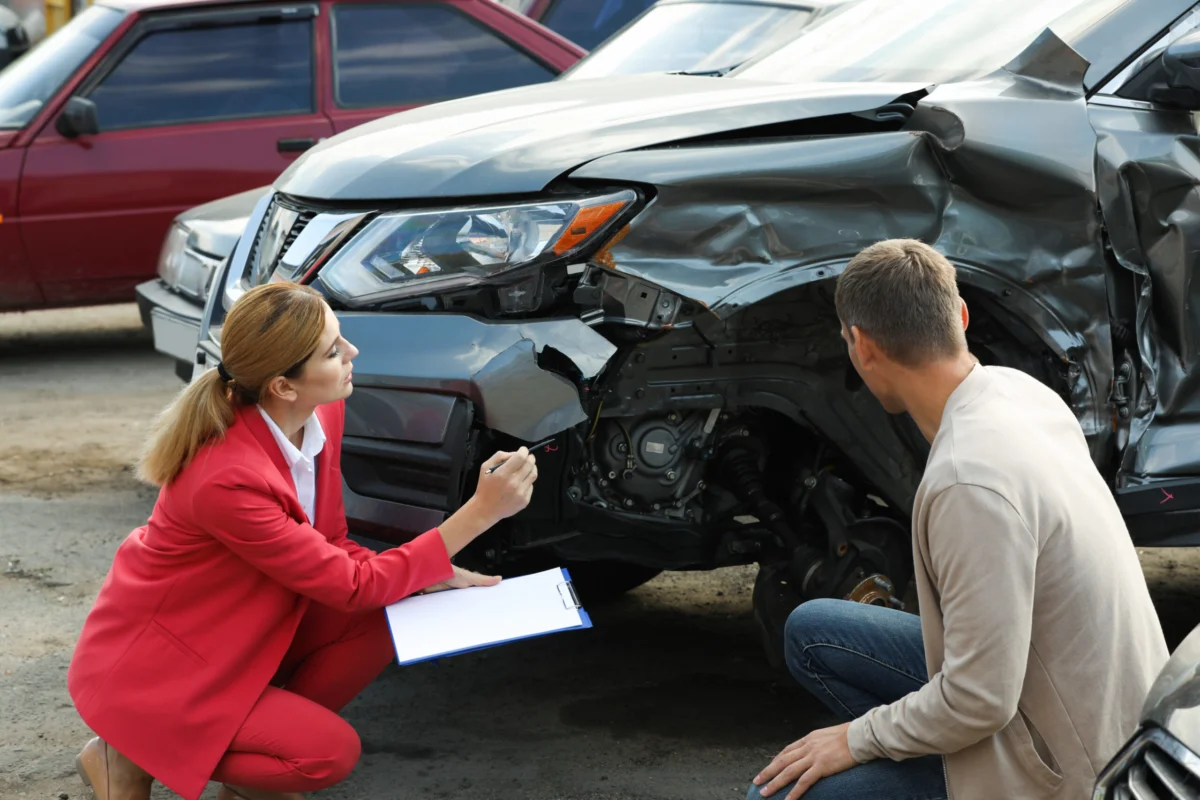
A significant factor driving the current sentiment is the increased frequency of total loss classifications. In 2026, approximately 26% of all auto insurance claims were categorized as total losses, a notable surge from the 16% recorded just four years prior. This shift is not merely a statistical anomaly but a reflection of deeper economic and structural changes within the automotive industry.
Several macro-level forces are contributing to this trend. First, the escalating cost of vehicle repairs—driven by the integration of complex sensors, advanced driver-assistance systems (ADAS), and specialized materials—has reached a threshold where even moderate damage can render a vehicle a total loss. Furthermore, as consumers hold onto their vehicles for longer periods due to high interest rates and fluctuating new car prices, older vehicles with lower market values are being totaled more frequently following relatively minor accidents.
The financial strain on consumers is also impacting the claims process. Faced with broader affordability pressures, many policyholders have opted to increase their deductibles or remove rental vehicle coverage from their policies to lower monthly premiums. When a claim is filed, these cost-cutting measures often lead to frustration, as policyholders find themselves paying out-of-pocket for rental cars or facing high initial costs before their insurance coverage begins to apply.
Repair Cycle Times and Operational Efficiencies
While the total loss experience has faltered, the repair segment of the industry has demonstrated tangible operational improvements. In the wake of the pandemic-era supply chain bottlenecks that crippled repair shops, the average repair cycle time has shown a consistent decline. During the first quarter of 2026, the average cycle time dropped to 15.3 days, representing a 10-day improvement compared to the first quarter of 2024.
This improvement can be attributed to several factors, most notably the stabilization of parts supply chains and a decrease in overall claim volume. With repair shops regaining capacity and labor shortages easing slightly in the collision repair sector, the "bottleneck effect" that defined the 2022–2024 period has largely dissipated. This reduction in cycle time has served as a primary driver for the improved satisfaction scores among customers whose vehicles were repaired, as timely vehicle restoration remains the highest priority for claimants.
The Communication Gap: A Critical Failure Point
The J.D. Power study highlights a profound correlation between communication efficacy and customer satisfaction. The data reveals a dramatic disparity in scores based on the perceived seamlessness of interactions across digital and human channels. Customers who reported a "seamless experience" across all touchpoints recorded an average satisfaction score of 804. In stark contrast, those who struggled to navigate disparate systems—such as having to repeat information to different agents or finding digital tools inconsistent with phone support—reported an average score of only 390.
Despite the critical nature of this integration, the industry’s performance in this area remains lackluster. Insurers were able to provide a truly seamless cross-channel experience only 54% of the time. Common points of failure cited by participants included:
- Fragmented Information: Customers receiving contradictory information from digital portals versus phone representatives.
- Technological Friction: Digital tools that failed to load, lacked necessary functionality, or required manual workarounds.
- Lack of Clarity: Insurers failing to explain the specific "total loss" valuation process, leaving customers feeling that the settlement offers were arbitrary or unfair.
Industry Rankings and Performance Benchmarks
In a competitive market where service quality serves as a primary differentiator, Amica Insurance claimed the top position in the 2026 study with a score of 775. Nationwide followed with a score of 743, while the Automobile Club of Southern California (AAA) secured the third position with a score of 740.
These top-performing firms consistently scored higher in the study’s most critical drivers of satisfaction: trust and the perceived fairness of settlement. The study weights these factors heavily, followed by the professionalism of personnel, the speed of the settlement, and the overall ease of resolving the claim. For insurers, the message from the 2026 data is clear: while speed is essential, the emotional and cognitive aspects of the claims process—trust and clear communication—are the true arbiters of customer loyalty.
Broader Economic Implications and Future Outlook
The implications of these findings extend beyond customer satisfaction scores. For insurance carriers, the inability to manage total loss expectations creates long-term reputational risk and increases customer churn. As the cost of vehicle technology continues to rise, the trend toward higher total loss ratios is unlikely to reverse in the near term.
Industry analysts suggest that insurers must pivot their strategy toward more transparent, data-driven communication regarding total loss valuations. When a vehicle is declared a total loss, the transition from "repair process" to "settlement process" is often where the breakdown occurs. Providing policyholders with granular, understandable data on how their vehicle’s value was determined, and offering guidance on the market realities of the current automotive landscape, could help mitigate the feelings of unfairness that currently plague the total loss segment.
Furthermore, the disparity between the 804-point satisfaction level of "seamless" customers and the 390-point level of others underscores the urgency of digital transformation. Insurers that fail to unify their backend data systems—ensuring that a claims adjuster, a mobile app, and a customer service center are all working from the same source of truth—will continue to lose ground to competitors that prioritize an integrated, omnichannel customer journey.
Study Methodology and Scope
The 2026 U.S. Auto Claims Satisfaction Study provides a robust view of the industry, based on the responses of 8,261 auto insurance customers. The respondents were selected based on their experience of settling a claim within the nine months preceding the survey period, which ran from September 2025 through August 2026. By examining the entire spectrum of the claim experience—from the ease of the initial reporting to the final resolution—the study provides a comprehensive benchmark for the insurance sector.
As the industry moves into the latter half of the decade, the focus for insurers will likely shift from merely managing repair volume to managing the human side of the claims experience. With repair times normalizing, the focus has shifted back to the core tenets of the insurance contract: trust, transparency, and the promise of a fair resolution during what is often a stressful life event for the policyholder. Whether the industry can address the persistent decline in total loss satisfaction will depend on its ability to modernize its communication frameworks and manage the realities of an increasingly expensive automotive market.
The data serves as a sobering reminder that while technology can accelerate the repair of a vehicle, it cannot replace the need for clear, empathetic, and unified communication. For the insurance sector, the path to 2027 and beyond will require a fundamental reassessment of how they interact with claimants when a vehicle is deemed a total loss, ensuring that the final settlement is not just a financial transaction, but a process that reinforces, rather than erodes, customer trust.