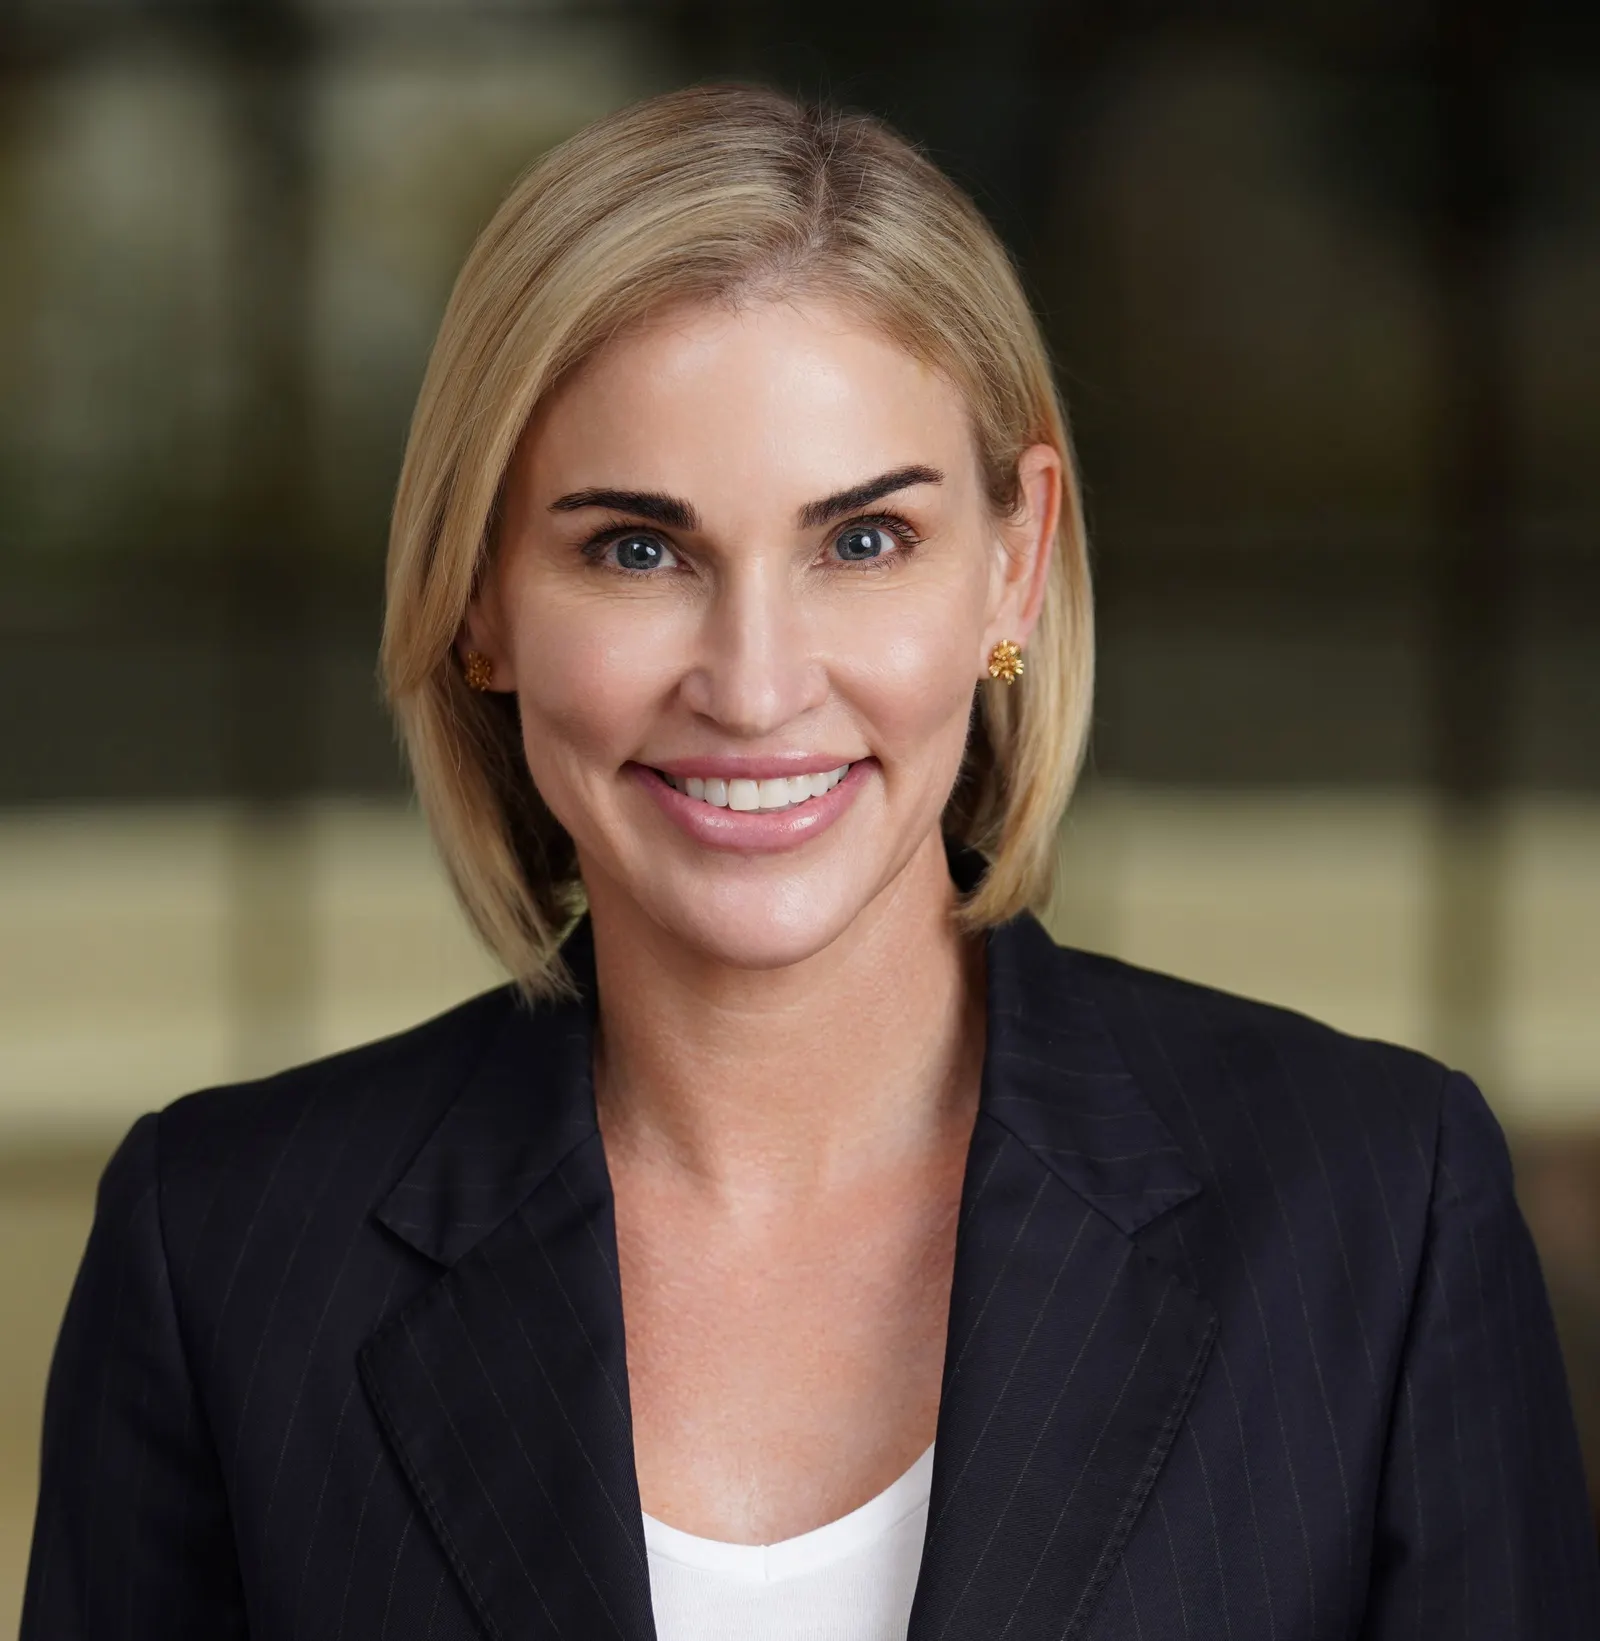
The financial services landscape is currently witnessing a high-stakes talent arms race, as major U.S. banking institutions scramble to capture the loyalty of the nation’s small-business owners. Bank of America, under the leadership of Sharon Miller, president of business banking, has signaled a significant ramp-up in its recruitment and retention strategies. This move comes as industry data reveals a staggering 105% increase in job openings for small-business banking roles at major competitors compared to the previous year, underscoring the vital importance of this segment to the bottom lines of national and regional lenders.
For financial institutions, the small-business sector represents a multifaceted goldmine. Beyond basic deposit accounts and commercial lending, business owners serve as a critical gateway to comprehensive, high-margin revenue streams. These include personal wealth management, complex treasury services, employee benefit programs, and the personal banking needs of the owners themselves. As a result, heavyweights such as Wells Fargo, U.S. Bank, and Capital One have all pivoted toward aggressive expansion in this space, effectively turning the battle for specialized relationship managers into a top-tier corporate priority.
The Strategic Value of the Business Banking Segment
The focus on small and midsize enterprises—defined by Bank of America as those generating up to $50 million in annual revenue—is not merely about expanding loan portfolios. It is about becoming the primary operating account for the business. By embedding themselves into the day-to-day financial operations of a company, banks can secure a sticky relationship that spans the entire life cycle of the firm.
Bank of America currently serves approximately 3.4 million small and midsize clients, a massive footprint that the bank intends to expand significantly. During the company’s investor day last November, leadership articulated a long-term goal of achieving a 30% market share in the 50-plus markets where they operate. Recent figures indicate steady progress, with the bank’s national average share reaching 27.6%, up from 27% just one year prior.
This growth is being managed through a dual approach: hiring external talent from a wide range of competitors and cultivating an internal pipeline. Miller emphasizes that the bank’s existing workforce, particularly its business solutions advisers in branch locations, provides a deep talent pool. By transitioning these employees into relationship manager roles, the bank ensures that new hires are already acclimated to internal systems, corporate culture, and risk management protocols.
Technological Integration: The AI Advantage
In a market where traditional relationship-based banking is being challenged by digital-first fintech platforms, Bank of America is leaning heavily into artificial intelligence to maintain its competitive edge. Speed to market has become a primary differentiator in business lending. In the current interest rate environment, where timing can often determine the success of a property acquisition or a capital expenditure project, the ability to underwrite and approve loans efficiently is paramount.
The bank’s investment in AI is already yielding measurable results. Specifically, in its "practice solutions" segment—which caters to specialized medical professionals such as doctors, dentists, and veterinarians—the bank has deployed an AI agent that has revolutionized the documentation process. By automating the gathering and verification of paperwork, the time required to move from application to funding has been reduced from three hours to just 15 minutes.
Miller has confirmed that the bank intends to scale this technology across its entire business-banking division by 2027. This transition represents a shift in how banks perceive efficiency; it is no longer just about cutting costs, but about enhancing the customer experience to prevent "deal leakage," where a borrower might pivot to a faster competitor.
Navigating the Human Element of Finance
Despite the rapid integration of AI and machine learning, Bank of America maintains that technology cannot replace the nuance of face-to-face interaction. The strategy for market penetration—particularly in newer territories like Omaha, Nebraska—relies heavily on a boots-on-the-ground approach.
The bank’s commitment to physical outreach is reflected in its staffing model. With over 2,125 business solution advisers and relationship managers, the bank is actively targeting the top 20 U.S. markets by GDP for intensive hiring. This strategy recognizes that while digital platforms are essential for transactional tasks, the "across-the-desk" conversation remains the gold standard for high-value client acquisition.
Industry analysts suggest that this "phygital" approach—combining sophisticated digital tools with high-touch human expertise—is the most effective way to compete against lean, digital-only fintechs. While fintechs may offer slick interfaces, they often struggle to provide the comprehensive advisory services, cash management platforms, and capital access that large, established banks provide.
Economic Implications and Future Outlook
The current competitive climate is largely a response to the shifting macroeconomic landscape. As small businesses navigate inflationary pressures and fluctuating interest rates, their need for sound financial advice and reliable liquidity has increased. Banks that can provide both—a stable platform and a trusted adviser—are seeing improved "prospect favorability" and client retention metrics.
The broader implications of this hiring frenzy suggest that the banking sector expects small-business demand to remain robust over the next several years. If the 105% growth in job postings is any indicator, the industry is preparing for a period of sustained, if not accelerated, competition. For the consumer, this suggests a more favorable environment characterized by faster loan processing, better-integrated digital tools, and a higher level of personalized service.
However, the challenge for lenders will be to balance this rapid expansion with prudent risk management. As Bank of America and its peers scale their operations, they must ensure that the quality of their loan portfolios remains intact while managing the costs of a massive talent acquisition program.
Conclusion: A Balancing Act
Bank of America’s trajectory reflects a broader industry recognition: the small-business sector is no longer a secondary focus but a core engine of growth. By leveraging its vast scale, investing in proprietary AI technologies, and doubling down on human relationship management, the bank is positioning itself to lead the market.
As Sharon Miller noted, the goal is to be there "in the moment" for the client. Whether that involves using AI to expedite a complex underwriting process or having a relationship manager walk into a client’s office to discuss a long-term strategic pivot, the winning strategy in modern banking appears to be the seamless integration of high technology and high touch. As the bank pushes toward its 30% market share target, the industry will be watching closely to see if this dual-pronged strategy continues to yield the competitive advantages required to outpace an increasingly aggressive field of rivals.
The next three years, leading up to the 2027 full implementation of its AI-driven lending platforms, will likely prove decisive. The bank’s ability to retain its current staff while successfully integrating new, highly skilled relationship managers will be the true test of its long-term viability in this high-growth sector. For now, Bank of America remains firmly committed to the belief that in an era of automation, the most successful bank will be the one that best understands the value of the human connection.