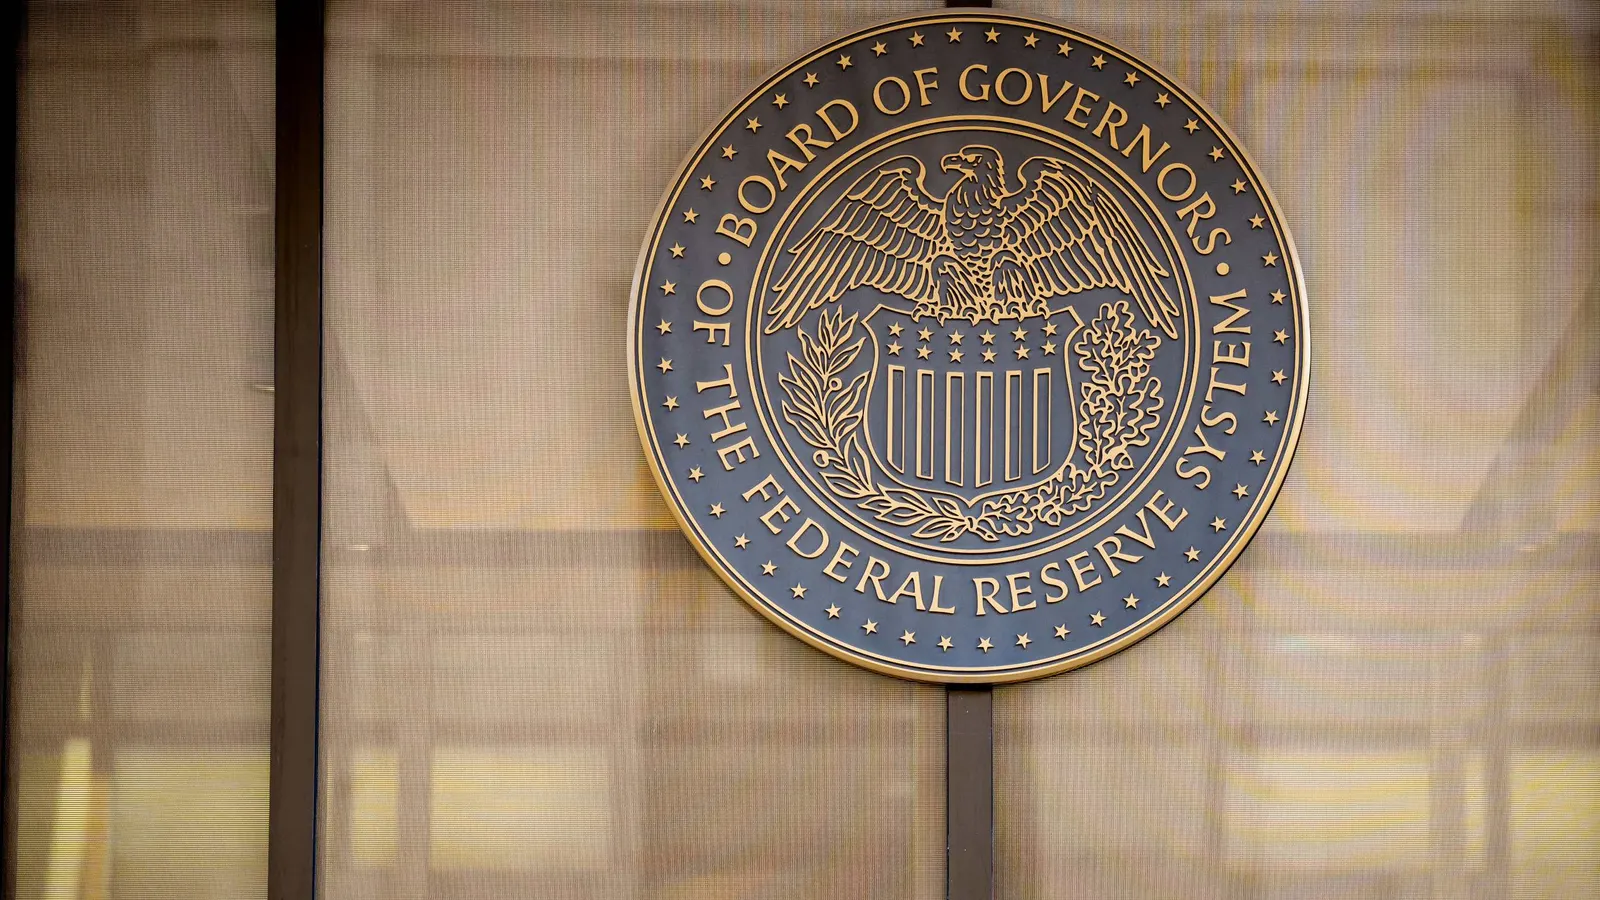
The Federal Reserve has officially unveiled its long-anticipated proposal for regulating stablecoin issuers, marking a critical step toward integrating digital assets into the traditional financial perimeter. The proposed rules, released on September 25, 2026, aim to establish a rigorous standard for entities issuing stablecoins—a class of cryptocurrency pegged to the value of a sovereign currency, most commonly the U.S. dollar. By mandating that issuers back their tokens with high-quality, liquid assets such as U.S. Treasury bills and creating a structured application process for commercial banks seeking to participate in the space, the Fed seeks to mitigate the systemic risks inherent in digital payment innovations.
This regulatory action comes in direct response to the requirements set forth by the Genius Act, a landmark legislative mandate that charged federal financial regulators and the Treasury Department with crafting a comprehensive framework for the burgeoning stablecoin market. While the legislative timeline initially targeted a July 2026 deadline for these regulations, the Federal Reserve’s latest move represents a significant, albeit delayed, effort to ensure that digital payment instruments do not compromise the integrity of the broader monetary system.
Defining the Regulatory Perimeter
The Federal Reserve’s proposal focuses on three primary pillars: asset composition, capital adequacy, and operational oversight. Under the new rules, issuers would be strictly limited in how they hold reserves. The requirement to maintain backing in "high-quality, liquid assets" is designed to prevent the liquidity mismatches that have historically plagued private currency issuers. By requiring that these reserves be held in instruments that can be converted to cash with minimal price volatility, the Fed aims to ensure that "redemption at par" is not merely a promise, but a technical certainty.
Beyond asset management, the proposal introduces specific capital requirements intended to absorb potential losses stemming from credit or operational failures. This shift effectively treats stablecoin issuers with a level of scrutiny comparable to traditional banking institutions. Furthermore, the Fed has outlined a detailed procedural framework for banks that wish to issue stablecoins, including a rigorous application, review, and potential appeals process. This oversight extends to firms that provide custodial services for the assets backing these digital coins, ensuring that the entire supply chain of stablecoin issuance is subject to federal supervision.
A Chronology of Regulatory Implementation
The road to this proposal has been marked by a staggered, inter-agency rollout. The Genius Act established a high bar for cooperation among federal regulators, yet the implementation process has seen varying speeds across agencies.
- February 2026: The Office of the Comptroller of the Currency (OCC) and the National Credit Union Administration (NCUA) were the first to move, releasing their respective proposed rules for stablecoin issuers under their purview.
- April 2026: The Federal Deposit Insurance Corporation (FDIC) followed suit, introducing standards focused on depositor protection and the risks stablecoins pose to the Deposit Insurance Fund.
- August 2026: The U.S. Treasury Department issued its own set of proposals, emphasizing the role of stablecoins in global payments and the importance of maintaining U.S. dollar hegemony.
- September 2026: The Federal Reserve finalized its proposal, effectively rounding out the regulatory mosaic required by the Genius Act.
Despite these collective efforts, no federal agency has yet finalized its rulebook. The industry currently exists in a "proposed" limbo, where issuers must anticipate the final regulatory trajectory without having the clarity of codified law. The Federal Reserve’s proposal will now enter a 60-day public comment period following its publication in the Federal Register, after which the Board of Governors will review feedback before finalizing the regulations.
Insights from the Fed: The "Par Redemption" Mandate
In his statement accompanying the proposal, Federal Reserve Governor Michael Barr emphasized that the primary goal of the framework is to preserve public confidence in the payment system. "Stablecoins will only be stable if they can be reliably and promptly redeemed at par in a range of conditions," Barr noted. He highlighted the necessity of maintaining this parity even during periods of extreme market stress, where government debt may face temporary liquidity constraints.
Barr’s comments reflect a broader concern among central bankers: that a sudden loss of confidence in a major stablecoin issuer could lead to a "run" on the reserves, forcing a fire sale of Treasury securities that could ripple into the wider bond market. By imposing strict risk management standards, the Fed is essentially attempting to "ring-fence" stablecoin issuers, ensuring that their failures remain idiosyncratic rather than systemic.
Economic Implications and Market Reaction
The proposed rules are likely to have a transformative impact on the cryptocurrency sector. For incumbent stablecoin issuers, the cost of compliance will be significant. The transition from unregulated or lightly regulated operations to a regime that requires high-quality reserve backing and capital buffers will inevitably force market consolidation. Smaller issuers who cannot afford the overhead of federal compliance may be squeezed out, potentially leading to a market dominated by a few "bank-like" entities.

From the perspective of traditional financial institutions, the proposed framework provides a long-awaited "green light" to experiment with digital assets. By creating a clear application process for banks, the Fed is inviting commercial lenders to move into the stablecoin space. This could lead to a hybrid model where regulated banks provide the infrastructure for digital payments, theoretically offering consumers the benefits of blockchain efficiency with the safety net of federal oversight.
However, some analysts argue that the complexity of the requirements could stifle innovation. Critics of the proposal often point to the "Genius Act" timeline, suggesting that the regulatory lag has created uncertainty that drives talent and capital toward jurisdictions with more established frameworks. Conversely, supporters argue that the deliberate, albeit slow, approach of the Fed ensures that the U.S. does not compromise on financial stability for the sake of speed.
Broader Financial System Integration
The integration of stablecoins into the regulated financial system represents a pivot point for the global economy. If stablecoins become a standard, safe instrument for retail and institutional payments, they could reduce the friction associated with cross-border transactions and settlement times. However, the Fed’s insistence on "par redemption" highlights the central bank’s desire to maintain control over the unit of account.
By mandating that these assets be backed by high-quality government debt, the Fed is essentially ensuring that the demand for stablecoins continues to bolster the demand for U.S. Treasurys. This creates a symbiotic relationship: the stablecoin industry gains legitimacy, and the U.S. government maintains a captive market for its sovereign debt.
Future Outlook and Finalization
As the 60-day comment period approaches, industry stakeholders, consumer advocacy groups, and technology firms are expected to weigh in heavily. Key points of contention likely to emerge include the stringency of the capital requirements, the definition of "high-quality, liquid assets," and the role of non-bank entities in the ecosystem.

For the Federal Reserve, the challenge remains to finalize these rules in a way that provides enough clarity to foster responsible innovation while maintaining the guardrails necessary to protect households and businesses. The upcoming months will be crucial, as the final version of these rules will set the tone for the next decade of digital finance. With all major federal regulators now having weighed in, the stage is set for a transition from the "Wild West" era of digital assets to a supervised, institutionalized future.
The success of this framework will ultimately be measured not by how many issuers comply, but by how well the system holds up during the next inevitable period of financial volatility. If the Fed’s vision holds true, the stablecoin of the future will be a boring, reliable, and highly regulated instrument—a stark contrast to the volatile assets that characterized the industry’s inception. As Washington shifts from theory to implementation, the digital economy is entering its most critical phase of maturation.