The quest for a national bank charter has evolved from a distant ambition to a critical inflection point for the modern fintech sector, requiring nothing less than the total dedication of a company’s leadership and operational infrastructure. This consensus emerged as a central theme during the Federal Reserve Bank of Philadelphia’s annual fintech conference, where industry leaders from Mercury, SoFi, and Square dissected the rigorous, multi-year journey required to transition from a technology provider to a regulated banking institution. As fintechs reach a critical mass of users and product complexity, the pursuit of a charter is increasingly viewed not merely as a regulatory hurdle, but as a foundational strategy for long-term growth, stability, and operational autonomy.
The Philosophy of Commitment: The Mercury Blueprint
For Jon Auxier, CEO and President of Mercury Bank, the decision to pursue a national bank charter is an existential commitment. Speaking at the Philadelphia Fed’s gathering, Auxier emphasized that a charter pursuit will only be successful when it becomes the singular, overriding objective of the enterprise. According to Auxier, who previously spearheaded the implementation of SoFi’s national bank charter, the process is transformative. "Chartering affects the operations of the business a ton, as it should," Auxier noted.
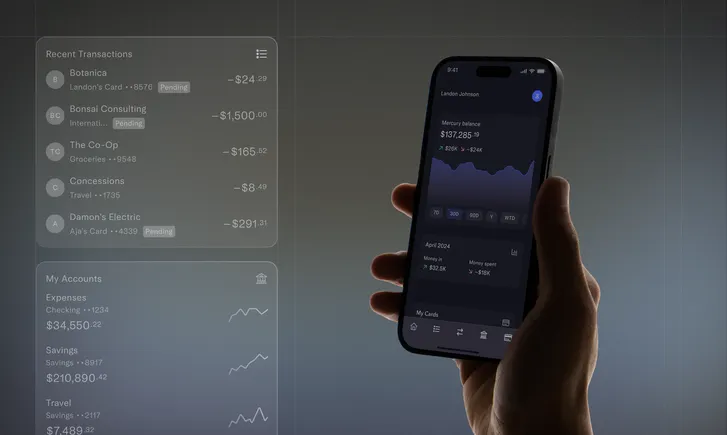
Mercury, which recently secured conditional approval from the Office of the Comptroller of the Currency (OCC), is currently navigating the final stages of its transition, with full banking operations anticipated by late 2027. For Auxier, the timing of such an endeavor is paramount. He advises that firms should only initiate this process when they reach a scale that allows them to treat the regulatory requirement with the gravity it demands. While Mercury filed its formal application in December, the objective was embedded in the company’s original business plan nearly a decade ago, illustrating the patient, long-term capital planning required to navigate the complex U.S. regulatory landscape.
A Chronology of Charter Evolution
The path to a banking charter has historically been fraught with uncertainty, yet the last five years have seen a surge in interest from non-bank financial institutions. The regulatory environment has matured alongside the industry, providing a clearer, albeit more demanding, roadmap for applicants.
- 2020: A watershed year for the industry. SoFi filed its formal application for a national bank charter, signaling a shift in how large-scale fintechs viewed their relationship with traditional financial infrastructure. Concurrently, Square Financial Services successfully secured an industrial loan company (ILC) charter from the FDIC, setting a precedent for the "bank-as-a-feature" model.
- 2021: Square launched its bank, demonstrating the operational benefits of direct access to the Federal Reserve system and deposit insurance.
- 2022: SoFi received conditional approval from the OCC, a milestone that significantly reduced its reliance on third-party bank partners and lowered its cost of capital.
- 2023–2024: A period of refinement. Regulators, including the OCC and the FDIC, have increased scrutiny on "banking-as-a-service" (BaaS) partnerships, prompting more fintechs to pursue independent charters to gain regulatory certainty and control over their own compliance frameworks.
- 2027 (Projected): The expected full launch of Mercury Bank, marking the culmination of a multi-year effort to integrate banking operations directly into its fintech platform.
The Human Capital Factor: Lessons from SoFi
Transitioning from a technology-first company to a chartered bank requires a fundamental shift in corporate DNA, a process that relies heavily on recruiting talent with institutional banking experience. Eric Schuppenhauer, an executive vice president at SoFi Bank, underscored the necessity of "hiring people who get it." According to Schuppenhauer, the process of obtaining a charter is not merely a legal exercise; it is a cultural transformation.
"Go get the folks that have done it before, put them into the seats, and make sure that they’re driving the processes forward," Schuppenhauer advised. He noted that the rigor required by federal regulators—such as the OCC and the Federal Reserve—eventually becomes a competitive advantage. When SoFi began its journey, it served approximately 3 million users. Today, that number has swelled to 15.8 million, with the bank adding roughly 1 million new members each quarter. For SoFi, the charter provided the "certainty" required to innovate at scale. As Schuppenhauer aptly put it, "Strong supervision provides strong innovation."
The Industrial Loan Company Model: The Square Perspective
While national charters offer broad geographic reach, the Industrial Loan Company (ILC) charter has provided a viable alternative for companies like Square. Richard Rosenthal, CEO and President of Square Financial Services, views the charter not as a burden but as a "feature." By bringing the banking functions in-house, Square has been able to build its own controls, moving from a reliance on partner banks to a self-sufficient model.
Rosenthal argued that the legwork required to satisfy regulators—specifically the creation of robust compliance, risk management, and capital adequacy frameworks—has allowed the company to move with greater speed in the long run. "If you have the foundation straight and you’re learning from your customer, the speed at which you can move is really differentiating," he said. This sentiment highlights a shift in the industry: regulation is no longer seen as a speed bump, but as the scaffolding that allows for sustainable, high-velocity growth.
Implications for the Financial Ecosystem
The movement of major fintech players toward chartering has profound implications for the broader financial services landscape. First, it signifies the maturation of the fintech sector. The "move fast and break things" ethos of the early 2010s is being replaced by a "build fast and comply with everything" strategy. This shift is likely to lead to increased consolidation, as only firms with significant capital reserves and the ability to attract top-tier compliance talent will be able to navigate the chartering process.
Second, the relationship between fintechs and traditional "sponsor banks" is changing. As more fintechs become banks themselves, the traditional BaaS model—whereby non-banks lease the charters of smaller, community-focused banks—may face a period of contraction. This forces smaller banks to re-evaluate their business models, while the fintechs themselves gain the ability to hold deposits, manage their own balance sheets, and exert greater control over their cost of funds.
Third, the regulatory oversight of these entities is becoming more uniform. As fintechs move under the same regulatory umbrella as traditional commercial banks, they are subject to the same capital requirements, stress testing, and consumer protection standards. This harmonization is expected to increase the stability of the digital banking sector, potentially reducing systemic risks associated with rapid, unregulated growth.
Conclusion
The journey toward a bank charter is a grueling test of corporate resilience. As demonstrated by the experiences of Mercury, SoFi, and Square, the successful pursuit of a charter requires a synchronization of strategy, talent, and regulatory alignment that can take years to achieve. While the barrier to entry is high, the reward is a level of operational sovereignty that allows these companies to scale safely and sustainably in an increasingly complex global financial market. For the next generation of fintech firms, the lesson is clear: if you intend to play in the big leagues of finance, you must be prepared to build the bank from the ground up, with the full weight of the organization behind the objective. As industry standards rise, the charter will remain the ultimate marker of a fintech firm’s transition from a startup to an enduring financial institution.