While nimble financial technology companies like Chime and Current have successfully tapped into influencer marketing and digital creator ecosystems, traditional financial institutions continue to steer clear of this rapidly expanding sector. This persistent reluctance highlights a deeper disconnect: traditional banks largely fail to understand the creator economy, both as a marketing channel and as a lucrative customer segment.
Despite the exponential growth of content creation—fueled by low barriers to entry and a booming digital marketplace—financial products tailored specifically to the unique operational needs of creators remain remarkably rare. This oversight
represents a significant missed opportunity for banks to engage with an underserved, highly motivated demographic. According to recent research from Mastercard, 78% of individuals report that participating in the creator economy directly contributes to their financial stability. Yet, financial institutions (FIs) remain hesitant to adapt their legacy systems to capture this burgeoning market.
The Structural Hesitation of Traditional Financial Institutions
To understand why traditional banks lag behind in servicing creators, one must examine the foundational risk models of the banking industry. Legacy financial institutions are built to serve predictable, stable profiles, such as traditional W-2 salaried employees or established small-to-medium-sized businesses (SMBs) with consistent cash flows.
Content creators, by contrast, rarely fit these rigid molds. Their revenue streams are notoriously volatile, fluctuating wildly based on platform algorithm changes, ad-rate variations, seasonal brand sponsorships, and shifting audience engagement. Consequently, traditional banks frequently classify creators as high-risk clients. Standard banking infrastructure struggles to apply conventional financial models—such as automated credit scoring, business lending, and long-term financial planning—to individuals whose income cannot be easily forecasted on a monthly basis.
Tachat Igityan, CFO and founder of destream, a financial platform built specifically for content creators, points out the systemic misalignment between traditional banking and the creator lifestyle. Traditional banks, Igityan notes, are simply not optimized to build products for creators because of income instability. Because it is exceedingly difficult to evaluate risk using legacy credit metrics, banks often choose to exclude creators entirely rather than innovate around their needs.
The Product Complexity Paradox: Why Creators Are Hard to Serve
Beyond risk assessment, designing scalable financial products for influencers presents a unique operational paradox. Unlike traditional SMBs that may operate physical storefronts or localized service businesses, creators exist in a borderless digital ecosystem governed by third-party tech platforms.
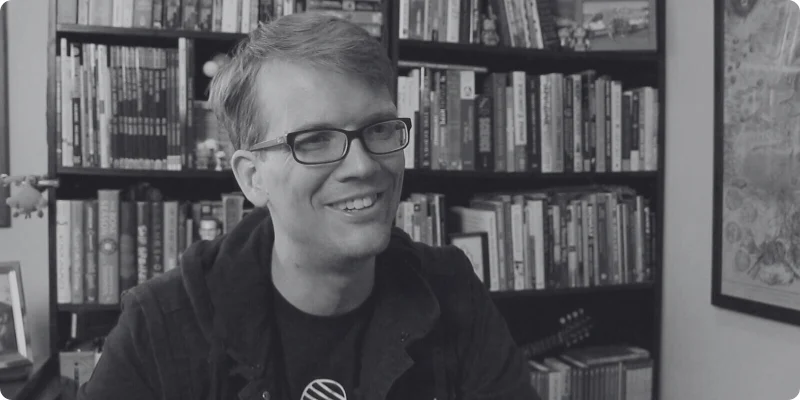
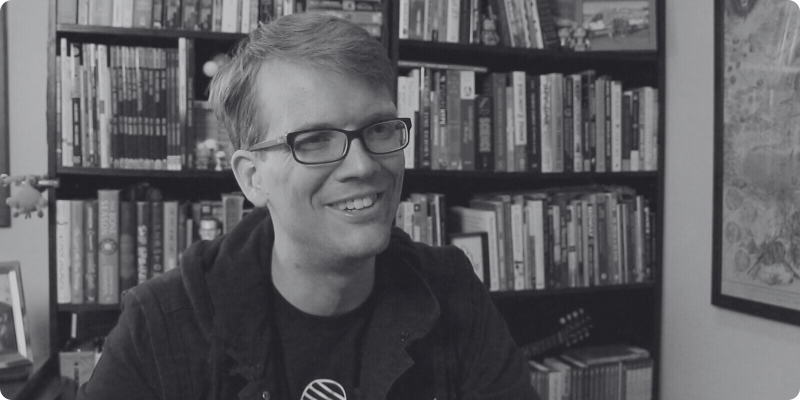
Veteran YouTuber and entrepreneur Hank Green, founder of the crowdfunding platform Subbable (later acquired by Patreon), has frequently highlighted the profound difficulties of building financial tools for this demographic. Having considered developing creator-centric financial products during periods of peak venture capital funding, Green understands the underlying complexities firsthand.
According to Green, creators are exceptionally diverse in their financial and operational needs. Designing a product that achieves true financial scale without requiring costly, individualized customization often results in an inferior product that fails to solve users’ actual problems.
Furthermore, the operational power dynamic between creators and major social media platforms complicates matters further. Content creators are uniquely dependent on massive tech conglomerates—such as YouTube, TikTok, and Meta—for their livelihoods. These platforms dictate payout schedules, monetization rules, and audience reach. Even industry veterans with years of experience frequently struggle to track their earnings accurately. Highlighting the fragility of these systems, Green publicly criticized platform payment infrastructure earlier this year, noting difficulties in tracking revenues, experiencing delayed updates, and facing unexpected currency conversions due to system errors.
Parallels with the SMB Evolution and the Cost of Inaction
The hesitation of traditional banks mirrors historical industry resistance toward other emerging economic shifts, such as the gig economy a decade ago. Initially viewed as temporary or excessively risky, gig work eventually forced traditional financial institutions to develop flexible banking tools, instant payout systems, and specialized micro-lending products.
However, the creator economy presents an even more complex challenge due to its global reach and reliance on intangible digital assets. Creators require sophisticated financial toolkits that mirror those of traditional SMBs, including streamlined invoicing, multi-currency processing, tax management assistance, and reliable cash-flow smoothing mechanisms. While major commercial banks now boast robust product suites for mainstream SMBs, they have largely failed to adapt these offerings to the distinct nuances of digital entrepreneurship.
The consequences of this inaction extend beyond lost revenue for banks. Without dedicated financial architecture, creators are forced to cobble together disparate tools—often relying on consumer-grade accounts, expensive peer-to-peer payment apps, or unregulated digital wallets—to manage complex business finances. This fragmentation exposes them to unnecessary fees, tax compliance risks, and vulnerability to sudden account freezes by platforms unaccustomed to business-volume transactions.
A Path Forward for Forward-Thinking Financial Institutions
As the creator economy matures from a decentralized hobbyist culture into a multi-billion-dollar global industry, the cost of ignoring this demographic is rising. The traditional banking sector’s insistence on applying twentieth-century risk frameworks to twenty-first-century business models is becoming increasingly untenable.
To successfully capture the creator market, forward-thinking financial institutions must rethink risk assessment entirely. This evolution could involve analyzing alternative data points—such as historical platform engagement metrics, recurring subscription revenues from fans, and diversified sponsorship contracts—rather than relying solely on traditional credit scores and stable tax returns. Furthermore, partnering with specialized fintech platforms that already understand the unique pain points of content creators could allow traditional banks to deploy embedded financial services without rebuilding their core infrastructure from scratch.
Ultimately, bridging the gap between traditional finance and the creator economy will require a fundamental shift in perspective. Banks that recognize creators not as high-risk anomalies, but as the modern iteration of small-business entrepreneurship, stand to capture a fiercely loyal, rapidly growing, and financially motivated customer base that is currently searching for a reliable financial home.