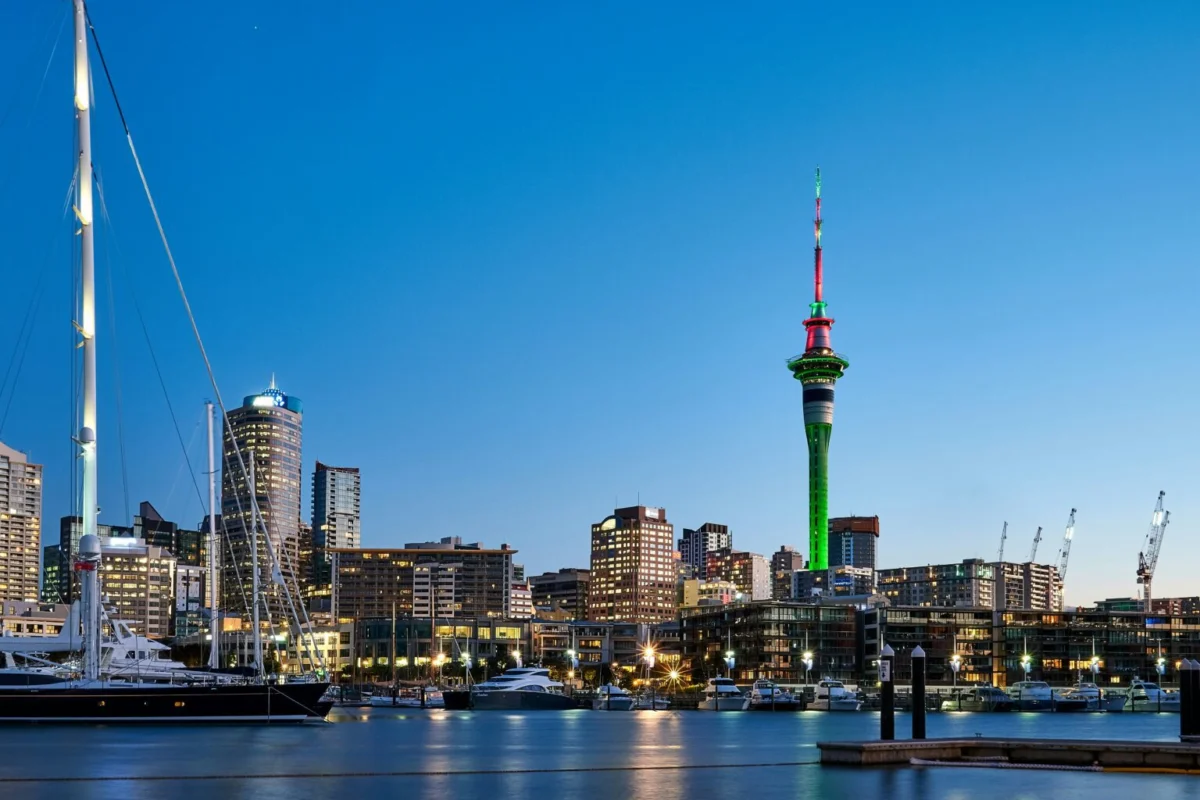
Global digital banking titan Revolut has officially crossed a major threshold in its international growth strategy by securing a banking licence in New Zealand. The Reserve Bank of New Zealand registered Revolut Bank New Zealand Limited, officially establishing the fintech as the country’s 27th registered bank and, crucially, its first-ever purely digital bank. This milestone fundamentally alters the competitive landscape of a financial sector long dominated by a small group of traditional institutions, paving the way for a new era of technology-driven consumer banking in the country.
The formal regulatory approval arrives three years after Revolut initially entered the New Zealand market operating purely as a financial services provider. Armed with full banking credentials, the company is wasting no time rolling out core banking products. Among the first offerings is a newly introduced Instant Access Savings account, which features a competitive 3.50% variable introductory savings rate guaranteed for the first four months. Furthermore, to build immediate consumer trust and comply with local regulatory standards, eligible deposits up to NZ$100,000 will be fully protected under the New Zealand Depositor Compensation Scheme (DCS).
A Landmark Moment for Global Ambitions
For the leadership team at Revolut, the New Zealand rollout is far more than a localized expansion; it represents a critical piece in an overarching global puzzle. Nik Storonsky, Founder and CEO of Revolut, emphasized the magnitude of the achievement.
“Launching our New Zealand bank marks another significant step in our mission to build the world’s first truly global bank,” Storonsky stated. “Securing our seventh bank licence and our fifth this year alone is a testament to our business model and our team. We are confident our offering will bring true competition to the New Zealand banking sector.”
The numbers underscore the breakneck pace of Revolut’s regulatory conquests. Serving more than 80 million customers worldwide, the UK-headquartered fintech now holds seven distinct banking licences and operates as a licensed bank across 34 separate geographies, encompassing major markets such as the United Kingdom, broader Europe, Australia, and now New Zealand.
The company’s regulatory momentum has been particularly fierce over the past year. Revolut has successfully secured new licences and authorizations in the United Arab Emirates, Mexico, Colombia, and Peru. At the same time, it has advanced its pending U.S. bank charter application with the Office of the Comptroller of the Currency (OCC) and cleared regulatory hurdles to acquire Banco Cetelem in Argentina. This trajectory marks a remarkable evolution from the company’s early days, when CEO Storonsky first demonstrated the nascent banking platform at the FinovateEurope conference in London back in 2015.
A Multi-Million Dollar Commitment to the Local Economy
Revolut is backing its digital-first vision with substantial capital investment. Alongside the regulatory announcement, the fintech committed to injecting NZ$120 million directly into the New Zealand market over the next five years. This capital expenditure is earmarked for scaling local operations, refining product offerings tailored specifically to Kiwi consumers, and mounting an aggressive marketing campaign to capture market share from legacy financial institutions.
Ryan Brosnahan, CEO of Revolut Bank New Zealand, highlighted the strategic importance of the local milestone.
“Becoming a bank in New Zealand marks a defining moment in our journey, achieved through a relentless focus on delivering a better financial experience for Kiwis,” Brosnahan remarked. “Since launching here in 2023, we have experienced massive growth. It’s clear the market is primed for disruption, and this licence is the launchpad for our next chapter to build the most seamless, secure, and customer-first banking experience in New Zealand.”
Chronology of Revolut’s Evolution in New Zealand
To understand the weight of Revolut’s latest achievement, it is helpful to look back at the timeline of its integration into the South Pacific economy:
- 2015: Revolut is founded in the UK and showcases its early platform capabilities at FinovateEurope in London.
- 2021–2022: The platform scales aggressively across Europe and expands into international markets, building out its multi-currency and digital wallet infrastructure.
- 2023: Revolut officially launches operations in New Zealand, initially functioning as a financial services provider rather than a fully licensed bank, offering international money transfers and multi-currency accounts.
- 2024–2025: As local user adoption surges, leadership lays the groundwork for full regulatory compliance and local incorporation, engaging closely with the Reserve Bank of New Zealand.
- Late 2026: The Reserve Bank of New Zealand officially registers Revolut Bank New Zealand Limited. The company becomes the country’s 27th registered bank and first digital-only banking institution, simultaneously announcing a NZ$120 million five-year investment plan and rolling out insured Instant Access Savings accounts.
A Distinct Strategy Compared to Industry Peers
Revolut’s aggressive global strategy sets it apart from many of its fintech peers. While other high-profile international digital banks—such as Brazil’s rapidly growing digital giant Nubank—have concentrated their overseas expansion efforts primarily within specific geographic regions or emerging markets, Revolut is pursuing a far more geographically diverse, border-agnostic playbook.
By securing fully regulated banking licences across multiple continents, Revolut is intentionally positioning itself to compete head-to-head with entrenched traditional financial institutions on their own turf, rather than settling for the role of a supplementary digital wallet or secondary financial services app. This structural shift allows the company to hold deposits, issue credit, and offer localized lending and savings products under the direct oversight of host-nation regulators.
Broader Market Implications and Future Outlook
The entry of New Zealand’s first digital bank could trigger a wider transformation within a domestic banking sector that has historically been characterized by high concentration and limited consumer choices. For decades, the New Zealand banking market has been heavily reliant on a handful of major incumbent lenders—many of them Australian-owned—which critics argue has led to lower deposit rates, higher lending margins, and slower technological innovation compared to more digitally fragmented markets in Europe or Asia.
By introducing an agile digital platform backed by a localized banking licence and a competitive 3.50% introductory savings rate, Revolut is forcing traditional banks to reassess their digital infrastructure, fee structures, and savings yields to prevent customer churn.
Industry analysts note that while capturing market share from deeply embedded legacy institutions will require sustained effort and consumer education, Revolut’s immense global backing, substantial five-year local investment commitment, and regulatory compliance under the Depositor Compensation Scheme provide a formidable foundation. As the first digital bank to clear New Zealand’s rigorous regulatory hurdles, Revolut has set a new benchmark for fintech entry into the region, signaling that the era of traditional banking dominance in the South Pacific is facing its most significant digital challenge to date.