The financial technology sector is undergoing a profound paradigm shift as artificial intelligence moves past passive customer-facing chatbots and basic task automation into the realm of fully autonomous execution. Casap, an emerging leader in enterprise-grade artificial intelligence agent platforms tailored specifically for the financial services industry, announced this week that it has successfully closed a $56 million Series B funding round. This latest injection of capital brings the California-based company’s cumulative funding to $90 million, arriving just over twelve months after the closure of its $25 million Series A round.
The financing milestone was spearheaded by Base10 Partners, a prominent venture capital firm known for backing transformative enterprise software companies. The round also featured strategic participation from major financial ecosystem players including Experian and Synchrony, alongside continued backing from existing institutional investors such as Emergence Capital and Lightspeed Venture Partners. According to company executives, the newly acquired capital will be deployed aggressively to scale Casap’s proprietary artificial intelligence platform, expand its roster of industry experts and forward-deployed engineering teams, and broaden its operational capabilities beyond its initial beachhead in fraud and payment disputes to encompass collections, complex claims, and general institutional exceptions.
The rapid trajectory of Casap underscores a broader institutional appetite for sophisticated technological interventions capable of navigating heavy regulatory environments, mitigating escalating fraud vectors, and overhauling legacy back-office infrastructures that have historically relied on extensive manual intervention.
The Chronology of Casap: From Inception to Market Validation
Founded in 2023 by industry veterans Shanthi Shanmugam—a former executive at digital brokerage giant Robinhood—and Saisi Peters—formerly of consumer financial technology leader Chime—Casap was established with a singular, ambitious mandate: to dismantle and streamline the notoriously cumbersome operational friction inherent in modern financial institutions.
During its formative months in early 2023, the founding team identified that back-office operations, particularly those governing payment disputes under regulations like the Electronic Fund Transfer Act (Regulation E) and the Truth in Lending Act (Regulation Z), represented an acute pain point for banks and fintechs alike. These processes traditionally demanded intense labor hours, high error rates, prolonged customer resolution windows, and substantial financial overhead.
By late 2023 and throughout 2024, Casap refined its core technological architecture. Rather than building static workflow software, the company engineered a platform powered by specialized artificial intelligence agents designed to autonomously investigate complex cases, synthesize data across disparate internal systems, render compliance-checked decisions, and execute necessary corrective actions. Crucially, these autonomous agents were programmed to adhere strictly to each financial institution’s unique policies and regulatory guidelines, maintain immutable auditable ledgers of every transactional decision made, and intelligently escalate edge cases requiring human judgment to authorized personnel.
The market response was swift and decisive. Over the preceding year, Casap experienced a staggering tenfold increase in annual revenue, more than doubling its internal projections and expanding its active client base to encompass more than 100 financial institutions. This market momentum culminated in a high-profile industry validation when Casap secured Best of Show honors for its live product demonstration at FinovateFall 2025. The company’s subsequent Series B announcement in late 2026 solidifies its transition from an early-stage disruptor to an entrenched enterprise infrastructure provider.
Decoding Agentic AI: How Casap Operates Within Financial Institutions
To understand the economic and operational impact of Casap’s technology, one must examine the mechanics of agentic artificial intelligence within regulated financial architectures. Traditional enterprise automation typically relies on rigid rule-based engines or robotic process automation (RPA), which frequently falter when confronted with unstructured data, nuanced customer behaviors, or novel fraud patterns. Conversely, generative artificial intelligence tools have often been limited to summarizing text or assisting human service agents without the autonomy to execute end-to-end operational workflows.
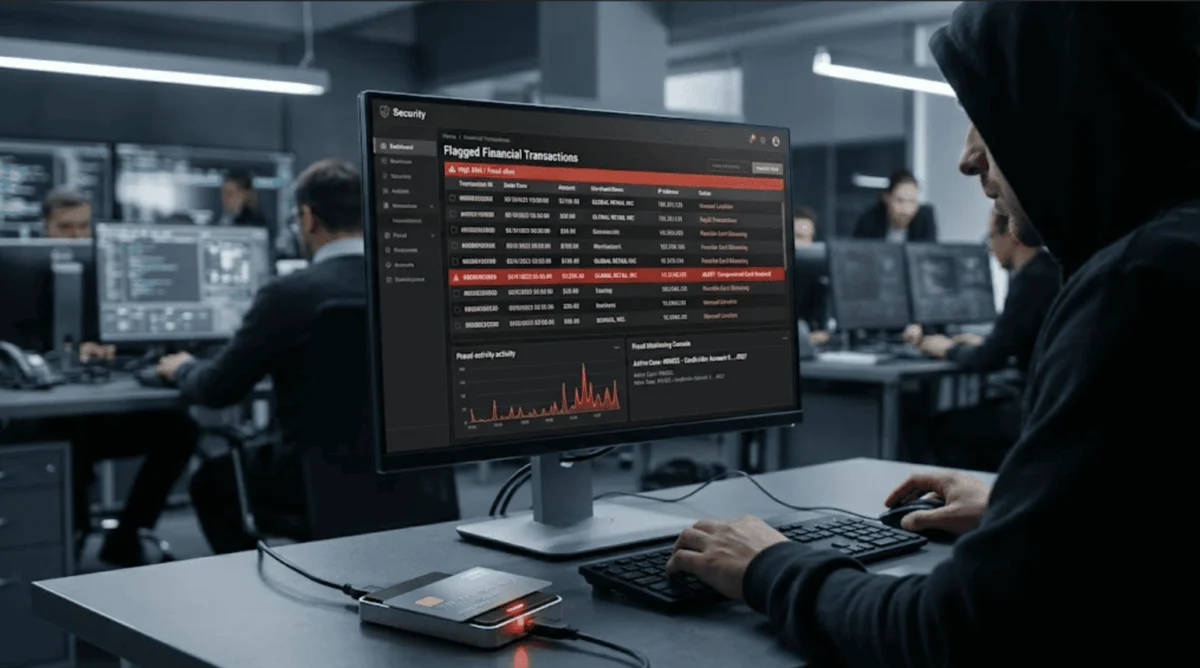
Casap bridges this chasm by deploying domain-specific AI agents capable of operating across the entire lifecycle of a financial exception. When a customer initiates a payment dispute or flags unauthorized account activity, Casap’s platform initiates an autonomous multi-step investigation. The agents cross-reference transaction logs, device fingerprints, behavioral biometrics, and historical account data, weighing the evidence against the host institution’s specific risk thresholds and compliance mandates.
If the parameters align with established fraud indicators or dispute legitimacy criteria, the system autonomously resolves the claim, issues provisional or permanent credits, updates core banking ledgers, and communicates the resolution to the customer—all within a fraction of the time required by human processing teams. For anomalies or high-value claims breaching risk tolerances, the system generates a comprehensive investigative dossier and routes the file to human compliance officers with clear, auditable recommendations.
This capability has fundamentally disrupted the traditional economic trade-off that banking executives have wrestled with for decades: the perceived necessity to compromise either on operational cost-efficiency or on customer experience quality. By collapsing investigation and resolution cycles from weeks or months down to mere days—while simultaneously cutting direct fraud losses in half—Casap’s platform demonstrates that technological leverage can simultaneously enhance risk mitigation and customer satisfaction.
Strategic Perspectives: Insights from Leadership and Investors
The convergence of venture capital interest and strategic corporate participation in Casap’s Series B round highlights the commercial viability of agentic workflows in enterprise settings.
"We started with disputes because it was one of the hardest problems in financial services," explained Shanthi Shanmugam, Chief Executive Officer and Co-founder of Casap. "But our ambition was always bigger than disputes. We wanted to prove that AI could do more than make work more efficient. It could fundamentally change the outcomes for financial institutions. Today we’re cutting fraud losses in half while resolving disputes in days instead of months. Now our customers are asking us to bring that same transformation to the rest of their operations."
The inclusion of major strategic investors such as Experian and Synchrony provides Casap with invaluable domain expertise and potential distribution pathways into vast credit and consumer finance ecosystems. Experian, a global leader in information services, data analytics, and credit reporting, views the partnership through the lens of enhanced identity verification and fraud prevention integration. Similarly, Synchrony, one of the premier consumer financial services companies providing private label credit cards and installment loans, recognizes the immense value of scaling automated dispute and claims resolution across millions of active revolving credit accounts.
Adeyemi Ajao, Managing Partner at lead investor Base10 Partners, emphasized the broader macroeconomic significance of the investment. "We’ve been told for years that financial institutions will have to make a tradeoff between operational economics and experience quality," Ajao noted. "Casap has shown that agentic AI technology can change that tradeoff. The same technology lowers the cost of complex work, while improving speed, quality, and consistency. Disputes proved that model in one of the hardest environments in financial services, and we believe the opportunity now is much larger."
Broad Market Implications: The Shift Toward Autonomous Workflows
The rapid ascent and substantial funding of platforms like Casap point toward a structural transformation in how banking institutions approach digital transformation and back-office scalability. For over a decade, financial technology spending was heavily concentrated on front-end user interfaces—such as mobile banking applications, streamlined account opening portals, and conversational virtual assistants. Meanwhile, middle- and back-office operations remained heavily dependent on armies of human analysts manually reviewing spreadsheets, cross-checking legacy databases, and processing exception queues.
As financial institutions face macroeconomic headwinds, compressed net interest margins, and sophisticated, AI-enabled fraud rings orchestrated by malicious actors, maintaining traditional manual operations is becoming economically untenable. Fraud losses globally continue to scale into the tens of billions of dollars annually, while regulatory scrutiny regarding timely dispute resolution and fair consumer treatment remains stringent.
By proving that autonomous agents can reliably execute complex, multi-system workflows without violating regulatory guardrails, Casap and its peers are effectively pioneering a new category of enterprise software. The expansion of Casap’s platform into adjacent operational domains—including loan collections, complex insurance and banking claims, and multi-layered exception processing—signals that the financial services sector is crossing a threshold. Automation is no longer viewed merely as a tool to assist human employees in performing repetitive micro-tasks, but as a resilient operational backbone capable of autonomously executing entire corporate workflows from inception to resolution.
Looking ahead, as Casap deploys its newly secured $56 million capital reserve to scale its engineering talent, deepen integrations with core banking providers, and onboard its expanding pipeline of institutional clients, the company is well-positioned to define the operational standards of the next generation of digital banking infrastructure.