The global creator economy has expanded at an unprecedented pace over the past decade, evolving from a casual hobbyist landscape into a multi-billion-dollar commercial engine driven by low barriers to entry and shifting consumer consumption habits. Yet, despite the explosive growth of independent digital entrepreneurs, content creators, and social media influencers, traditional financial institutions (FIs) remain largely detached from this lucrative sector. While innovative fintech pioneers such as Chime and Current have successfully leveraged creator-focused marketing and tailored banking features to capture massive younger demographics, mainstream banks continue to steer clear. This institutional reluctance highlights a profound misunderstanding of how the creator economy operates, resulting in a glaring gap in the market where creators are consistently overlooked, underserved, and alienated by legacy financial products.
According to extensive industry research, approximately 78 percent of individuals participating in the creator economy report that building a digital brand and monetizing content directly helps them achieve long-term financial stability. Despite this powerful financial motivation, traditional banking models have failed to adapt. While most major commercial banks currently offer robust suites of products designed for traditional small- and medium-sized businesses (SMBs), the unique operational nuances of the creator economy—such as highly volatile revenue streams, delayed platform payouts, and globally diversified income sources—demand a specialized, dedicated financial strategy. Legacy institutions continue to miss a monumental opportunity to cultivate relationships with a rapidly expanding, highly motivated, and digitally native customer base.
The Evolution of the Creator Economy: A Brief Chronology
To understand why traditional banks struggle to accommodate content creators, it is essential to examine the rapid chronology of the digital content landscape.
During the early 2000s, user-generated content platforms like YouTube emerged primarily as hobbyist communities. Monetization was virtually nonexistent, and creators relied on personal savings or external employment to fund their digital projects. By the early 2010s, programmatic advertising models matured, allowing pioneering creators to generate sustainable ad-revenue shares. This era marked the birth of the professional influencer, though financial infrastructure remained primitive, forcing creators to rely on standard personal bank accounts or basic merchant services.
Between 2015 and 2020, the creator ecosystem diversified drastically. Platforms introduced native monetization tools, subscription models, brand sponsorships, and merchandise integration. The COVID-19 pandemic catalyzed this growth further, as millions turned to digital platforms for entertainment and income, lowering the barriers to entry and solidifying digital content creation as a viable career path.
However, throughout this rapid evolution, traditional banking infrastructure remained stagnant. While venture-backed fintech startups began engineering specialized financial platforms to address the idiosyncratic cash-flow challenges of influencers, legacy banks maintained rigid underwriting criteria, effectively locking creators out of traditional credit markets, tailored commercial loans, and sophisticated wealth-management services.
Why Traditional Financial Institutions Remain Reticent
The fundamental disconnect between traditional financial institutions and the creator economy stems from operational rigidity. Content creators operate under business models that starkly contrast with the predictable, salaried profiles traditionally favored by commercial risk assessors.
Tachat Igityan, Chief Financial Officer and founder of destream—a specialized financial platform catering to content creators—elaborates on this systemic hesitation. Traditional banks are fundamentally unaccustomed to building products for creators due to the inherent instability and unpredictability of digital income streams, Igityan notes. Modern banking business models are traditionally engineered around servicing stable, low-risk customers, such as W-2 salaried employees or established brick-and-mortar businesses. Consequently, legacy institutions frequently view digital creators as high-risk clients. Applying traditional financial models—such as credit scoring, commercial lending, algorithmic risk assessment, and long-term financial planning—to an influencer whose monthly revenue can fluctuate wildly based on algorithm changes or ad-rate seasonality remains a formidable challenge for risk-averse bankers.
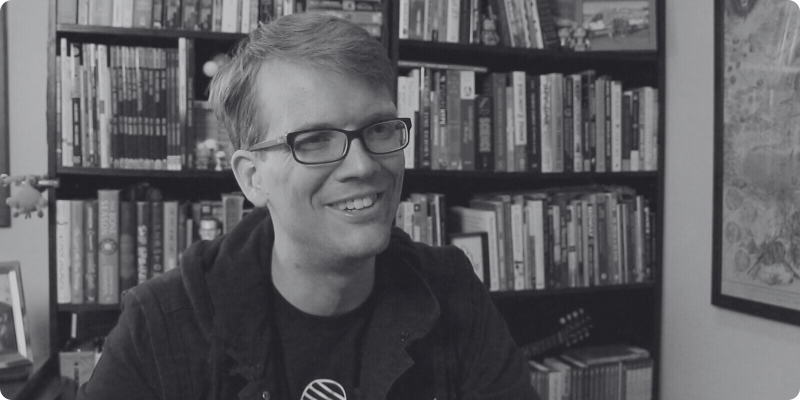
Furthermore, the operational diversity within the creator segment complicates scalable product development. Veteran YouTuber and digital entrepreneur Hank Green, author and founder of the crowdsourcing platform Subbable (later acquired by Patreon), has frequently discussed the extreme complexities of engineering financial solutions for this demographic. Having evaluated the feasibility of building creator-centric financial tools during peak venture capital funding cycles, Green highlighted the paradox of scale.
Creators possess such diverse, individualized needs that attempting to build a scalable product—while avoiding excessive operational costs associated with hyper-customization—frequently results in an ineffective product, Green observes. For legacy banks accustomed to deploying standardized, one-size-fits-all financial products across millions of retail or corporate clients, the granular, multi-faceted requirements of content creators represent an unappealing operational hurdle.
The Complexities of Platform Dependency and Revenue Opacity
Compounding the difficulty of servicing influencers is the immense centralized power held by social media and content hosting platforms. Unlike traditional businesses that issue invoices directly to clients and collect predictable accounts receivable, digital creators are frequently dependent on third-party intermediaries—such as YouTube, TikTok, Meta, and Twitch—to process, report, and disburse their earnings.
Even highly experienced, globally recognized digital personalities frequently struggle with basic financial transparency regarding their own revenues. Green publicly underscored this systemic opacity earlier this year, detailing frustrating administrative friction regarding cross-border platform disbursements. The lack of standardized, reliable payout mechanisms creates significant accounting and cash-flow forecasting hurdles for creators. When multi-national platforms experience technical failures, misattribute a creator’s geographic tax jurisdiction, or disburse funds in foreign currencies unexpectedly, the creator’s financial planning is immediately compromised.
For traditional financial institutions, these structural vulnerabilities translate into compliance, auditing, and verification nightmares. Without transparent, verifiable revenue pipelines, legacy banks struggle to establish automated underwriting rules or compliance protocols satisfying anti-money laundering (AML) and know-your-customer (KYC) mandates.
Why Creators Desperately Need Intervention from Financial Institutions
Despite these complex operational hurdles, the urgency for traditional financial institutions to engage with the creator economy has never been higher. At the core of every creator’s operational challenge is liquidity and payments. Because financial motivation serves as the primary catalyst drawing new participants into the digital economy, the current vacuum of sophisticated financial products directly impedes creators from fully capturing and maximizing the value of their labor.
Creators require robust financial ecosystems that mirror those available to traditional small businesses, yet are custom-tailored to their unique operational realities. Key operational needs include:
- Predictable Cash-Flow Management: Tools designed to smooth out cyclical income dips caused by seasonal advertising rate fluctuations or irregular brand sponsorship cycles.
- Simplified Cross-Border Payouts: Automated systems that handle multi-currency conversions, international tax withholding, and global remittances without excessive transaction fees.
- Flexible Credit and Lending Underwriting: Alternative credit-scoring models that evaluate a creator’s historical platform engagement, follower retention, subscriber metrics, and signed contract pipelines rather than historical W-2 tax returns.
- Tax and Compliance Automation: Integrated software solutions capable of tracking multi-jurisdictional income, calculating estimated quarterly taxes, and managing business expenses efficiently.
Broader Market Implications and Future Outlook
The persistent refusal of traditional financial institutions to engage meaningfully with the creator economy leaves a massive, high-value market segment wide open to aggressive fintech disruption. Companies that successfully bridge this gap stand to capture intense brand loyalty from a young, affluent, and digitally influential demographic.
As the creator economy continues its maturation into a foundational pillar of the modern digital labor market, legacy banks can no longer afford to dismiss influencers as anomalies or high-risk outliers. Successfully servicing this demographic requires a fundamental shift in banking philosophy: moving away from rigid, historical risk-assessment models toward dynamic, data-driven financial engineering. Until traditional financial institutions adapt their underwriting frameworks, modernize their cross-border payment rails, and invest in understanding the complex nuances of digital entrepreneurship, the creator economy will remain a missed opportunity—and fintech innovators will continue to reap the rewards.