The landscape of consumer personal finance is undergoing a profound structural transformation, driven by persistent inflationary pressures, elevated interest rates, and evolving consumer preferences regarding debt and liquidity. As traditional budgeting constraints tighten across households—symbolized by the reality that roughly 78 percent of Americans currently live paycheck to paycheck—consumers are increasingly altering how they manage credit utilization, loyalty rewards, and alternative payment models. High-spend retail events, such as Amazon Prime Day, have historically served as barometers for consumer financial health. Recent data from these shopping windows reveals a marked divergence in how modern shoppers fund their purchases, balancing traditional credit cards against the rapid proliferation of Buy Now, Pay Later (BNPL) platforms.
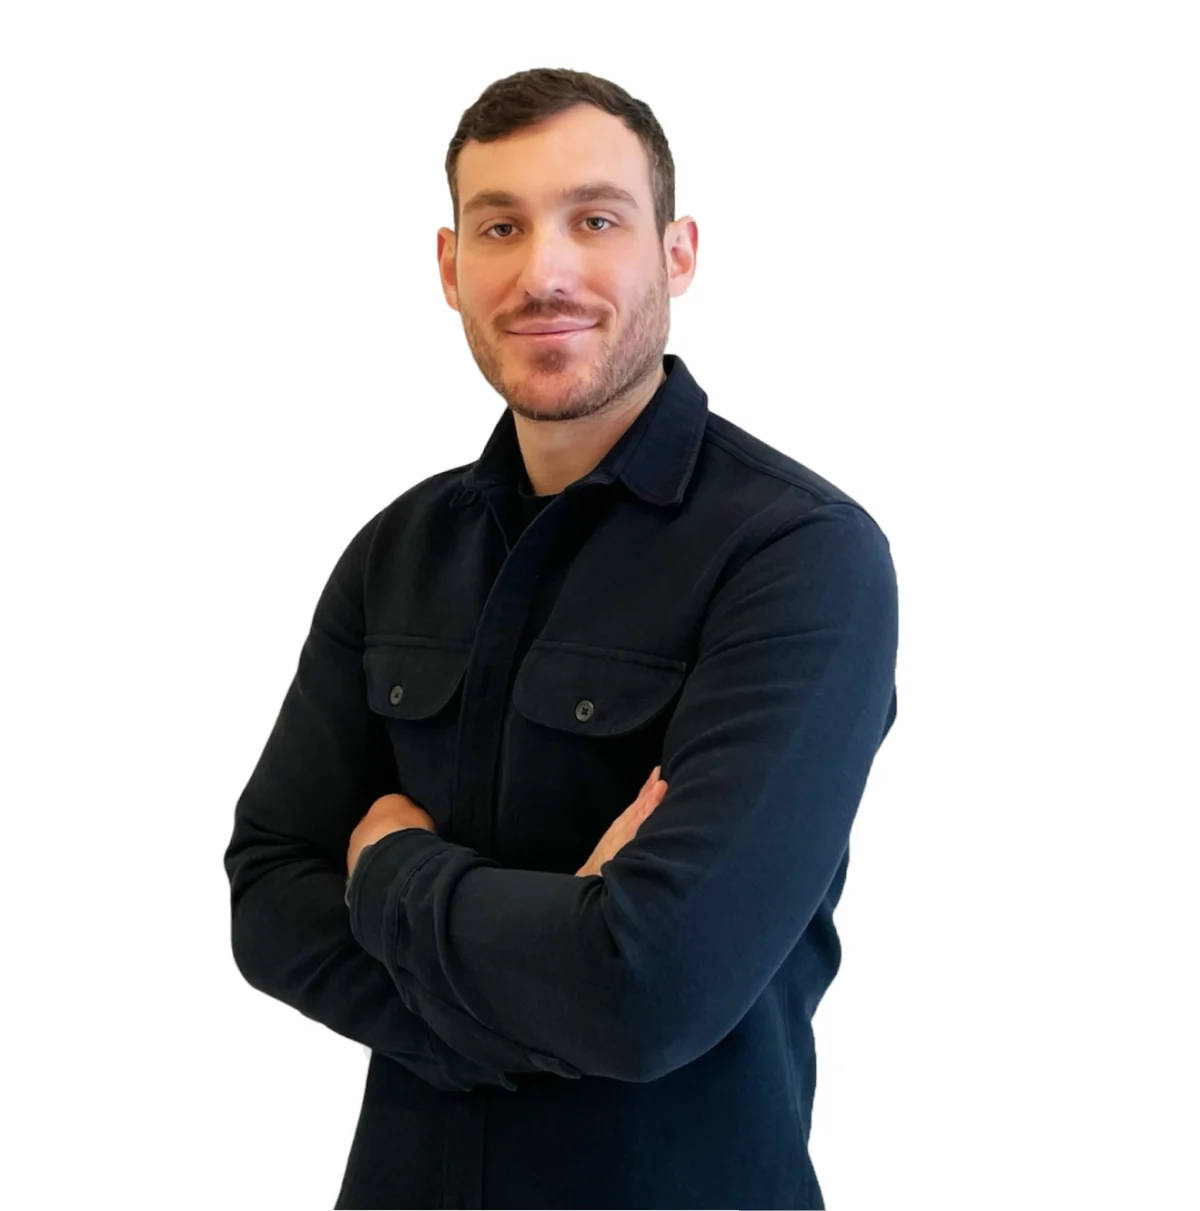
Amid these macroeconomic headwinds, financial technology firms are racing to introduce advanced tools designed to safeguard consumer credit scores while offering transactional flexibility. Among industry leaders addressing these challenges is Sam Miller, Chief Executive Officer of Kasheesh, a financial technology platform specializing in multi-use split payments and credit optimization. In a detailed discussion on the shifting paradigms of consumer credit, Miller outlines the intersection of artificial intelligence, regulatory pressures, and generational shifts in financial management, offering a comprehensive look at how the broader financial services ecosystem must adapt to survive an impending credit crunch.
Macroeconomic Pressures and the Evolution of Consumer Spending
To understand the current volatility in credit behavior, one must examine the broader economic climate that has defined consumer spending over the past several years. Following unprecedented global supply chain disruptions and subsequent spikes in inflation, central banks worldwide aggressively raised benchmark interest rates to cool economic activity. While these monetary policy interventions eventually curbed the velocity of inflation, they simultaneously increased borrowing costs for mortgages, auto loans, and revolving credit card debt.
Consequently, personal savings rates have dwindled, leaving households with narrower margins for error. According to recent market metrics, consumer reliance on non-traditional payment flows has surged. Expenses traditionally excluded from standard credit card processing—such as residential rent, utility bills, municipal car payments, and student loan obligations—are increasingly being funneled through alternative liquidity mechanisms. This behavioral adaptation highlights a distressed consumer base seeking to bridge monthly income gaps through inventive financial footwork.
This financial strain was prominently displayed during major e-commerce milestones. During the most recent Amazon Prime Day event, digital commerce analytics captured a staggering $7.2 billion in total e-commerce spending within the broader retail ecosystem. Within this massive volume, BNPL solutions accounted for approximately 7.5 percent of all transactions, translating to roughly $540 million in deferred-payment spending—a 17.1 percent year-over-year increase. While BNPL offers immediate purchasing power, industry watchdogs and fintech executives have raised alarms regarding its long-term impact on consumer indebtedness. Unlike revolving credit lines reported uniformly to major credit bureaus, the fragmented nature of certain BNPL offerings can obscure total consumer debt loads, occasionally leading to missed payments and subsequent credit score damage.
The Chronology of Payment Innovation: From Single-Use to Smart Split Technology
The trajectory of alternative payment solutions has accelerated rapidly over the last half-decade. Initially, fintech startups focused heavily on single-use virtual cards designed primarily to enhance online security and privacy. These early iterations allowed consumers to generate burner card numbers for isolated transactions, shielding their primary banking details from potential data breaches.
However, as economic pressures mounted, the limitations of single-use architecture became apparent. Consumers required ongoing liquidity solutions that could integrate seamlessly with digital wallets like Apple Pay and Google Wallet for recurring subscriptions, everyday retail purchases, and multi-vendor shopping carts. This realization sparked the development of multi-use virtual cards capable of dividing a single transaction across multiple underlying funding sources, including traditional credit cards, debit accounts, and prepaid gift cards.
Looking toward the immediate future, the next phase of this chronological evolution centers on artificial intelligence and machine learning. Fintech developers are currently programming predictive algorithms designed to automate financial hygiene at the point of sale. Rather than requiring consumers to manually calculate debt-to-limit ratios—a tedious process that many overlook until negative credit score adjustments have already materialized—emerging AI engines aim to execute real-time credit optimization. For instance, forthcoming platforms are engineered to automatically analyze a user’s active credit balances and distribute upcoming purchases across various cards to maintain an optimal credit utilization ratio without manual user intervention.
Deconstructing Credit Utilization: The Math Behind the Score
At the core of modern personal finance management lies credit utilization—the ratio of a consumer’s revolving credit currently being used to their total available credit limit. According to standard credit scoring models such as FICO, credit utilization accounts for approximately 30 percent of an individual’s overall credit score, making it second only to payment history in terms of scoring weight.
Financial literacy experts universally advise maintaining a credit utilization rate below 30 percent to project financial health and creditworthiness to lenders. Conversely, utilization rates exceeding 60 percent can severely penalize a consumer’s credit profile, triggering higher interest rates on future loans or outright denials of credit. Despite the monumental importance of this metric, consumer awareness remains surprisingly low. Many individuals discover the adverse effects of high utilization only after their monthly statements close and their credit scores drop.
Industry responses to this educational deficit vary. Traditional financial institutions typically rely on static educational portals, blog posts, and periodic credit-monitoring alerts. However, fintech innovators argue that passive education is insufficient in a fast-paced digital economy. By embedding optimization logic directly into the transaction workflow, platforms seek to transform every purchase into an exercise in credit enhancement. By dynamically splitting transactions to keep individual card utilization safely beneath the critical 30 percent threshold, algorithmic payment tools attempt to align consumer purchasing power with long-term credit health.
Implications for Traditional Banks and Card Issuers
The rise of multi-use payment networks and AI-driven credit optimization presents both strategic challenges and unique opportunities for legacy financial institutions, commercial banks, and major credit card networks.
For decades, traditional issuers have waged expensive wars for customer acquisition, investing billions of dollars annually in rewards programs, sign-up bonuses, and promotional APR offers. The ultimate goal for any issuer is to become the consumer’s "top of wallet" card—the default payment method retrieved first for every purchase. However, this model introduces significant friction. To justify these massive customer acquisition costs, issuers often set high baseline requirements. Furthermore, once consumers hit specific annual spending thresholds or maximize tiered rewards on a particular card, they frequently abandon it in favor of competing offers, leaving banks with dormant accounts and stagnant revenue streams.
Alternative payment platforms propose a collaborative paradigm shift. By functioning as an orchestration layer above existing financial accounts, technologies that enable multi-card payment splits can effectively keep multiple traditional cards in active rotation simultaneously. In this ecosystem, legacy credit and debit cards retain their top-of-wallet status because the underlying routing technology allows them to participate in transactions they might otherwise miss due to single-card spending limits or low available balances.
Financial analysts note that this approach could reduce issuer default risks by distributing consumer debt across healthier credit utilization brackets. Nevertheless, it also challenges traditional banks to rethink their proprietary loyalty structures, urging them to embrace open-banking principles and interoperable payment infrastructure rather than relying solely on closed-loop rewards to retain customer loyalty.
Demographic Shifts and the Looming Credit Crunch for Younger Generations
As the financial services industry looks ahead over the next five years, demographic shifts will likely dictate the trajectory of credit utilization and reward optimization. Younger demographics, particularly Generation Z, exhibit markedly different psychological relationships with debt and traditional credit products compared to their Millennial, Gen X, and Boomer predecessors.
Market research indicates that younger consumers are significantly less likely to open traditional revolving credit card accounts, often preferring debit cards, cash-equivalent apps, or short-term installment loans. While this aversion to revolving debt stems partly from a cautious attitude toward high interest rates, it poses a severe systemic challenge within the United States financial architecture. In the U.S. economy, building a robust credit score is an indispensable prerequisite for major life milestones, including leasing an apartment, securing an affordable mortgage, obtaining auto insurance, and occasionally passing employer background checks.
Without early, deliberate engagement in credit-building behaviors, younger generations risk falling behind a financial curve that takes years to correct. When combined with elevated housing costs, stagnant entry-level wages, sticky inflation, and the impending burden of federal and private student loan repayments, the structural foundation for young adults is increasingly fragile.
Industry analysts suggest that the next half-decade will witness an intense market consolidation around financial products that simultaneously address affordability, budgeting, and credit visibility. Platforms that successfully merge frictionless payment flexibility with automated credit-building mechanics are positioned to capture significant market share among younger consumers navigating an increasingly expensive world.
Conclusion
The convergence of macroeconomic volatility, technological innovation, and changing generational attitudes has fundamentally altered the terrain of consumer finance. As traditional budgets are tested by inflation and high borrowing costs, the reliance on rigid payment structures is giving way to dynamic, software-driven alternatives. Through the integration of artificial intelligence, multi-use card architectures, and real-time credit optimization, the fintech sector is attempting to solve structural flaws in how consumers manage debt and rewards.
While legacy financial institutions face the imperative to modernize their top-of-wallet strategies and adapt to open-ecosystem demands, consumers stand to benefit from tools that bridge the gap between immediate purchasing necessity and long-term credit health. Ultimately, the future of the financial services ecosystem will depend on its ability to foster financial literacy and resilience organically at the point of sale, ensuring that the next generation of consumers can navigate economic headwinds without compromising their financial futures.