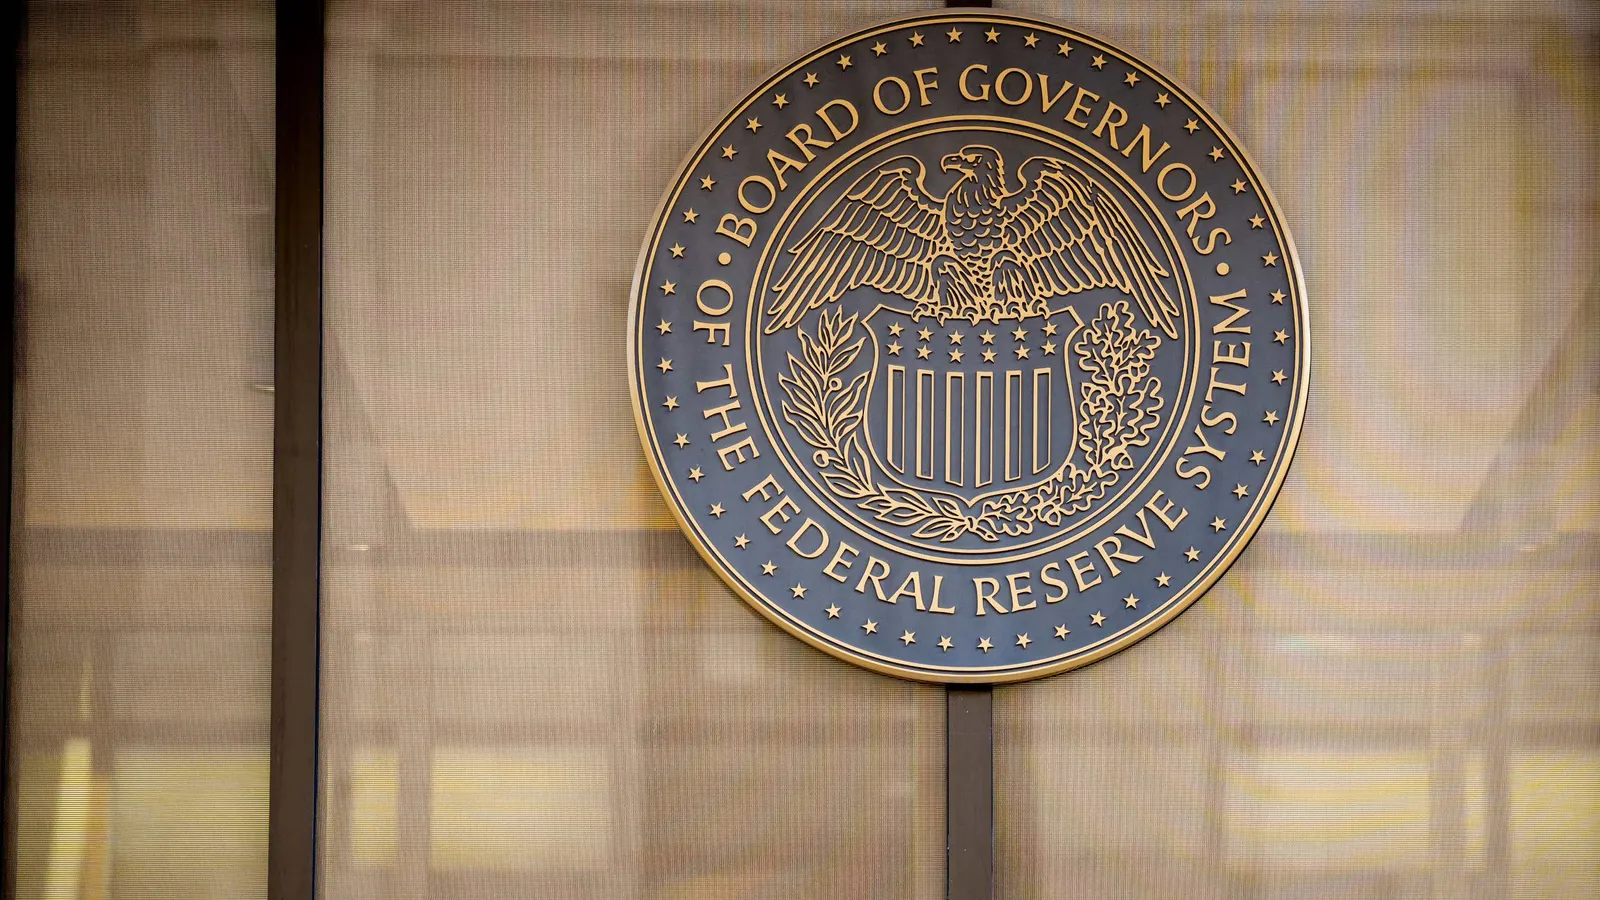
The Federal Reserve has officially unveiled a long-anticipated proposal aimed at establishing a rigorous regulatory framework for stablecoin issuers, marking a significant step toward integrating digital assets into the traditional financial perimeter. The proposed rules, released on September 25, 2026, mandate that issuers back their digital tokens with high-quality, liquid assets, such as U.S. Treasury bills, and introduce a formalized application process for banking institutions seeking to issue stablecoins. This move is a direct response to the requirements set forth by the Genius Act, a legislative mandate that obligates federal financial regulators to develop a comprehensive oversight structure for the rapidly evolving stablecoin market.
The proposal arrives at a critical juncture for the digital asset industry, as the Federal Reserve seeks to mitigate the systemic risks associated with assets that claim to maintain a one-to-one parity with the U.S. dollar. By imposing capital requirements, risk management standards, and specific operational protocols for firms that act as custodians of backing assets, the central bank is signaling a shift toward a more conservative and supervised approach to decentralized finance.
The Legislative Mandate and the Genius Act
The Genius Act serves as the cornerstone for current regulatory efforts, compelling the Treasury Department and various federal agencies to standardize the oversight of stablecoins. The act was designed to bridge the gap between burgeoning financial technology and established consumer protection laws. Despite the urgency implied by the legislation, the Federal Reserve’s timeline has drawn scrutiny; the Act required federal agencies to establish final regulations by July 2026.
The Fed’s entry into the rulemaking process is the latest in a series of institutional responses. The Office of the Comptroller of the Currency (OCC) and the National Credit Union Administration (NCUA) initiated their respective rule-making processes in February 2026. Subsequently, the Federal Deposit Insurance Corporation (FDIC) and the Treasury Department introduced their own proposals in April and August, respectively. To date, however, no federal agency has finalized these regulations, leaving the market in a state of regulatory transition that has prompted both caution and anticipation among industry participants.
Michael Barr on Market Integrity and Redemption
In an accompanying statement, Federal Reserve Governor Michael Barr emphasized that the legitimacy of stablecoins hinges entirely on their reliability. "Stablecoins will only be stable if they can be reliably and promptly redeemed at par in a range of conditions," Barr noted. He specifically highlighted the necessity of maintaining stability during periods of market stress, where even highly liquid government debt can face valuation pressure.
Barr’s comments reflect the central bank’s broader concern regarding "run risk"—the potential for a sudden, massive wave of redemption requests that could force an issuer to liquidate assets at a loss, thereby breaking the dollar peg. The proposed rules seek to institutionalize safeguards that would prevent such scenarios, requiring issuers to prove their operational resilience not just during calm markets, but throughout extreme economic volatility.
Structural Requirements and Oversight
The proposed regulatory framework covers several critical domains:

- Asset Backing: Issuers will be restricted to holding "high-quality, liquid assets." This effectively limits the use of volatile corporate debt or proprietary crypto-assets as collateral, favoring the safety and transparency of sovereign debt instruments.
- Capital and Liquidity Standards: The rules introduce capital requirements specifically designed to buffer against both credit and operational failures.
- Custodial Oversight: For firms supervised by the Federal Reserve that provide safekeeping services for backing assets, the proposal establishes clear operational standards to prevent commingling of funds and to ensure the segregation of digital and fiat assets.
- The Approval Pathway: For banks wishing to enter the stablecoin space, the Fed has outlined a structured application process. This includes defined timelines for appeals, public hearings, and final determinations, providing a predictable—if rigorous—pathway for institutional participation.
Chronology of Federal Stablecoin Rulemaking (2026)
- February 2026: The Office of the Comptroller of the Currency (OCC) and the National Credit Union Administration (NCUA) issue initial stablecoin regulatory proposals.
- April 2026: The Federal Deposit Insurance Corporation (FDIC) approves a proposal to implement Genius Act requirements, focusing on deposit insurance and insolvency standards.
- July 2026: The statutory deadline for federal agencies to finalize stablecoin regulations under the Genius Act passes without final rules in place.
- August 2026: The Treasury Department releases its proposed guidance, emphasizing cross-agency coordination.
- September 25, 2026: The Federal Reserve officially releases its proposed rules, opening a 60-day window for public comment.
Broader Implications for the Financial Ecosystem
The introduction of these rules signifies a maturation of the stablecoin market. By moving from a period of regulatory ambiguity to one of codified supervision, the Federal Reserve is effectively legitimizing stablecoins as a payment instrument, provided they meet strict safety standards.
For commercial banks, the rules offer a clearer roadmap for integration. Previously, many traditional financial institutions remained on the sidelines, fearing that the lack of federal guidance could lead to future legal or compliance pitfalls. With the Federal Reserve’s framework, banks now have a clearer understanding of the capital reserves and audit trails that would be required to issue a bank-grade stablecoin.
Conversely, for non-bank stablecoin issuers, the landscape is becoming more challenging. The cost of compliance with the Fed’s standards, combined with the administrative burden of filing for approval, will likely lead to industry consolidation. Smaller issuers may struggle to meet the capital requirements, potentially leading to a market dominated by a few large, well-capitalized firms that have the resources to adhere to these high regulatory hurdles.
Analysis of Risk and Market Stability
Financial analysts have pointed out that the Fed’s focus on "redemption at par" addresses the primary systemic risk associated with stablecoins: the threat of contagion. If a large stablecoin issuer were to face a liquidity crisis, the impact could spill over into the short-term funding markets, particularly the market for Treasury bills. By requiring issuers to hold these assets in a manner that ensures immediate liquidity, the Fed is attempting to protect the broader U.S. financial system from shocks originating in the crypto-asset sector.

However, the 60-day comment period—which will commence upon publication in the Federal Register—is expected to be highly contentious. Industry advocates are likely to argue that overly restrictive capital requirements could stifle innovation, while consumer protection groups may push for even more aggressive oversight, particularly regarding transparency and real-time reporting of backing assets.
Conclusion and Future Outlook
The Federal Reserve’s proposal is a pivotal development in the ongoing effort to integrate digital finance into the global monetary system. While the delay in meeting the Genius Act’s July deadline has caused some frustration, the depth of the proposed rules suggests that the central bank is prioritizing long-term stability over short-term speed. As the 60-day public comment window approaches, the discourse will likely center on the delicate balance between fostering a modern, efficient payment infrastructure and ensuring that the risks inherent in digital assets do not jeopardize the safety and soundness of the U.S. banking system. The outcome of these deliberations will set the regulatory tone for the next decade of digital financial services, influencing how businesses and households interact with programmable money.