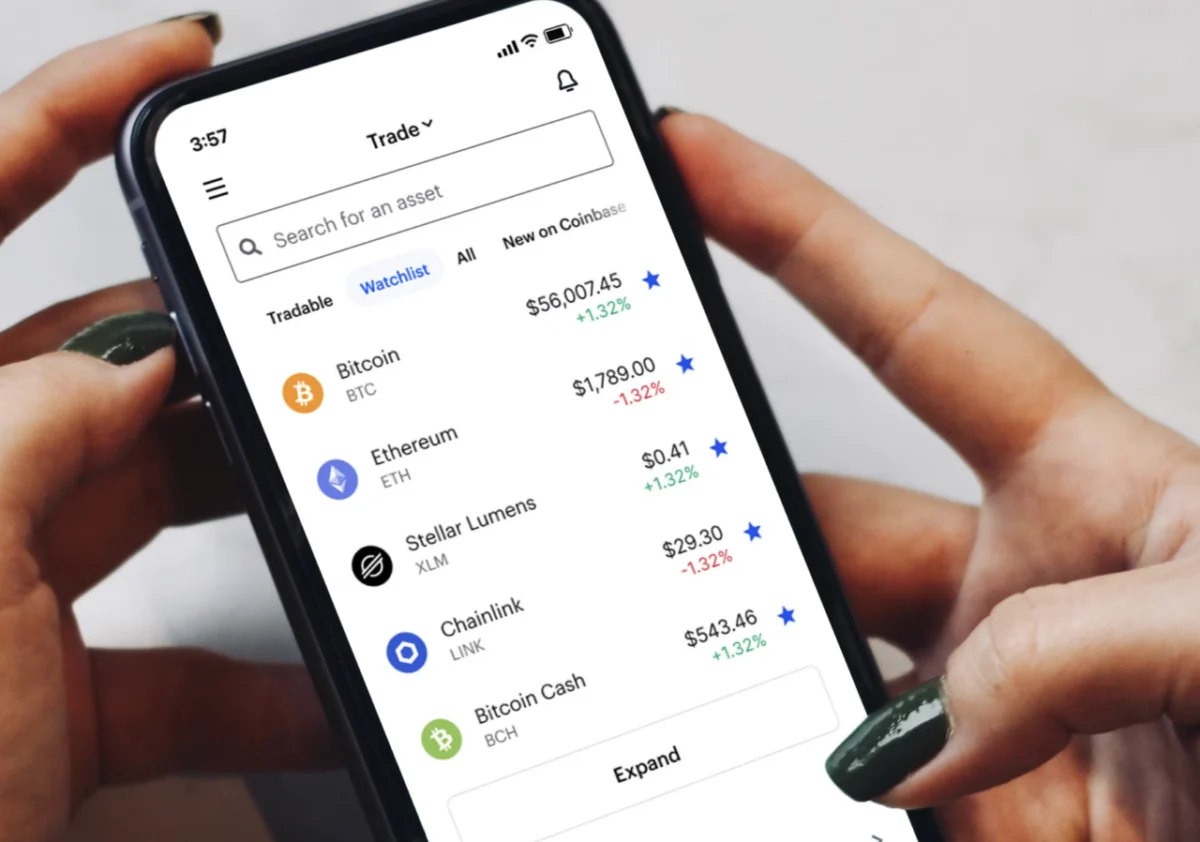
The landscape of retail and commercial banking is undergoing a profound structural shift as digital finance increasingly merges with traditional institutions. In a major development for the financial technology sector, cryptocurrency exchange giant Coinbase has announced a strategic partnership with Stablecore, a specialized DeFi banking infrastructure provider. The collaboration is designed to empower community banks, regional financial institutions, and credit unions to offer robust digital asset services directly through their legacy banking applications.
By bridging the gap between decentralized finance and traditional banking infrastructure, the partnership aims to overcome the technological barriers that have historically prevented smaller financial institutions from competing with digital-first fintechs. Under the agreement, Coinbase will leverage Stablecore’s modular network to extend comprehensive digital asset capabilities—including compliant trading, institutional-grade custody, and high-speed stablecoin payment solutions—to more than 3,000 banking and credit union partners across the United States.
Bridging Traditional Banking and the Decentralized Economy
For decades, the rise of cryptocurrencies and digital assets forced consumers to establish financial relationships outside the traditional banking ecosystem. To buy Bitcoin, trade altcoins, or utilize stablecoins for cross-border transactions, retail customers and corporate entities alike had to open separate accounts with centralized crypto exchanges or download specialized self-custody wallets. This fragmentation often left community banks and regional credit unions at a severe disadvantage, as they watched deposit capital flow away from their balance sheets and into the hands of digital-native platforms.
The new integration between Coinbase and Stablecore seeks to reverse this dynamic. The solution enables bank customers and credit union members to seamlessly participate in the digital asset economy without ever leaving their existing, trusted banking portals. Crucially, the infrastructure is engineered to allow traditional financial institutions to offer regulated digital asset products under their own proprietary brand names and within existing compliance frameworks, completely eliminating the need to overhaul their core banking technology stacks.
Alec Lovett, Head of Infrastructure Business at Coinbase, emphasized the strategic importance of empowering local financial institutions. “Community banks and credit unions shouldn’t have to choose between staying local and staying current,” Lovett stated. “Together with Stablecore, we are helping put them on the cutting edge of payments technology—cheaper, faster money movement, and the tools they need to stay strong for the communities they serve.”
The Evolution of Stablecore: Background and Market Positioning
Founded in 2025, Stablecore has rapidly carved out a vital niche within the fintech ecosystem by focusing exclusively on the needs of community and regional banks and credit unions. Based in Texas, the fintech enterprise recognized early on that smaller financial institutions lack the dedicated engineering resources required to independently build, secure, and regulate complex digital asset rails.
To solve this, Stablecore developed white-labeled, modular software solutions that integrate cleanly into legacy banking technology architectures. The platform acts as a unified bridge, consolidating the disparate components required for a traditional bank to safely handle tokenized deposits, manage stablecoin liquidity, and deliver retail-facing digital asset products.
Amarillo National Bank, a prominent Texas-based financial institution, has already stepped forward as one of the early pilot participants testing the new digital asset offering. By deploying the Stablecore-powered infrastructure, Amarillo National Bank can deliver advanced crypto and stablecoin functionalities to its local customer base while ensuring that vital deposit and lending relationships remain securely anchored within the community bank.
Alex Treece, Co-Founder and Chief Executive Officer of Stablecore, underscored the practical necessity of the firm’s architectural approach. “Banks and credit unions should not have to move to completely new technology platforms to support digital assets for their clients,” Treece noted. “We built Stablecore to bring together all of the pieces so they don’t have to.”
The Broader Trend of Financial Services Rebundling
The Coinbase-Stablecore partnership represents a textbook manifestation of a broader macroeconomic and technological phenomenon currently sweeping the financial services sector: the rebundling of banking capabilities.
Over the past fifteen years, the unbundling of finance was the dominant industry narrative. Specialized fintech startups carved away lucrative pieces of the traditional banking value chain—such as international remittances, consumer lending, investment management, and cryptocurrency trading—leaving traditional banks with low-margin deposit holding and legacy overhead.
Today, however, the pendulum is swinging back toward consolidation. Consumers increasingly demand a unified, single-pane-of-glass interface where they can manage their entire financial lives—checking accounts, mortgages, retirement investments, and digital assets—in one secure place. For community banks and credit unions, failing to provide digital asset services risks losing the next generation of account holders to fintech competitors.
By integrating infrastructure provided by a crypto native like Coinbase through a specialized banking middle-layer like Stablecore, traditional lenders can reclaim their status as the primary financial relationship for their customers. This model allows community institutions to modernize rapidly, capturing fee revenue and deposit liquidity that would otherwise have migrated to external crypto platforms.
Strategic Analysis: Coinbase Pivots from Competitor to Infrastructure Enabler
One of the most compelling aspects of this alliance is the shifting strategic positioning of Coinbase itself. As a direct-to-consumer cryptocurrency exchange, Coinbase has historically competed with traditional financial institutions for customer attention, deposits, and transaction volume. Retail users seeking exposure to digital assets typically opened accounts directly on the Coinbase platform or via its mobile application.
However, by supplying its market-leading infrastructure to Stablecore’s vast network of banks and credit unions, Coinbase is executing a sophisticated pivot. Rather than attempting to acquire and retain every retail crypto investor directly, Coinbase is positioning itself as the foundational plumbing underlying the entire digital asset economy.
This B2B (business-to-business) infrastructure play allows Coinbase to monetize its technology stack at scale, capturing transaction and custody volume originating from millions of traditional banking customers who might never have downloaded the Coinbase app directly. In this paradigm, Coinbase does not need to own the customer relationship; instead, it captures value by owning the infrastructure that powers the relationship.
For the participating banks, the arrangement provides an equally compelling value proposition. It allows them to defend their turf against digital-native disruptors by weaponizing their most powerful asset: local trust and established regulatory compliance.
Industry Implications and Future Outlook
As the regulatory framework surrounding digital assets and stablecoins continues to mature globally, initiatives that bring crypto services under the umbrella of regulated, insured depository institutions are likely to accelerate. Stablecoins, in particular, are increasingly recognized by central bankers and commercial lenders alike as a revolutionary medium for institutional settlement and cross-border commercial payments, offering near-instantaneous settlement times at a fraction of the cost of legacy wire networks.
The successful rollout of the Coinbase and Stablecore integration across thousands of community banks and credit unions will serve as a crucial bellwether for the industry. If regional institutions can effectively deploy these tools without compromising security, compliance, or user experience, it could fundamentally alter the competitive dynamics of American banking.
Ultimately, the partnership signals a maturing digital asset market where convergence, rather than antagonism, defines the relationship between decentralized finance and traditional banking institutions. As community banks gain secure, turn-key access to the crypto economy, the boundary separating traditional finance from the blockchain continues to dissolve, paving the way for a more integrated, resilient, and technologically advanced financial system.