The modern global economy is undergoing a structural transformation in how individuals earn, manage, and spend money. Traditional employment models—characterized by steady, predictable salaries paid bi-weekly or monthly by a single employer—are increasingly sharing space with a dynamic, decentralized workforce. Today, millions of workers earn income outside the boundaries of traditional 9-to-5 jobs, participating in the gig economy, taking on seasonal work, or operating as independent contractors and self-employed micro-entrepreneurs. While this economic shift has fostered unprecedented workplace flexibility, it has simultaneously exposed a critical fault line in the global financial system: the traditional credit scoring apparatus.
For decades, access to affordable credit has served as a cornerstone of economic mobility, enabling individuals to purchase homes, finance higher education, start small businesses, and weather financial emergencies. However, the legacy credit infrastructure was built for a bygone era. Millions of creditworthy consumers—particularly the unbanked, underbanked, and non-traditional earners—are routinely sidelined or penalized by automated underwriting systems because their financial realities do not conform to standard credit bureau reports.
Recognizing this systemic bottleneck, financial technology innovators, data analytics firms, and legacy credit bureaus are rapidly evolving. The focal point of this evolution is a paradigm shift in how lenders evaluate risk, moving away from a narrow reliance on historical debt management toward a holistic evaluation of an individual’s entire financial ecosystem. At the forefront of this movement is Fair Isaac Corporation (FICO), which used the FinovateFall 2026 conference to showcase how next-generation analytics and strategic partnerships are reshaping credit access.
The Evolution of Creditworthiness: Willingness Versus Ability to Pay
To understand the limitations of legacy credit scoring, industry experts emphasize the necessity of distinguishing between two fundamental pillars of credit risk: a borrower’s "willingness to pay" and their "ability to pay."
Traditional credit reports excel at capturing the former. Generated by major credit bureaus, a conventional credit report tracks how an individual has historically managed credit obligations, such as auto loans, mortgages, and credit cards. It details payment histories, credit utilization ratios, defaults, and bankruptcies. In essence, it answers the question: Based on past behavior, does this consumer make a consistent effort to honor debt obligations?
While invaluable, this historical lens has always contained a glaring blind spot. It fails to answer whether the consumer actually possesses the current financial bandwidth to absorb new debt. An individual with a thin credit file—perhaps a recent college graduate, a permanent gig-economy worker, or an immigrant building a financial identity from scratch—might possess pristine spending discipline and ample monthly cash flow, yet register a low or non-existent traditional credit score simply because they have few open credit lines.
Conversely, a consumer might have a long-standing credit history that signals a high willingness to pay, but experience a sudden, unrecorded drop in income that severely compromises their current liquidity. Traditional models often miss these real-time shifts, leading to either unwarranted credit denials for creditworthy individuals or risky extensions of capital to overextended borrowers.
The integration of cash flow data directly addresses this imbalance. By analyzing real-time banking transactions, income deposits, savings patterns, and recurring expense management, lenders gain empirical insight into a consumer’s true "ability to pay." This fusion of willingness and ability represents the next frontier in risk assessment, bridging the gap between historical credit behavior and contemporary financial reality.
The UltraFICO and Plaid Partnership: A Technological Milestone
A prime catalyst for this industry-wide transformation is the strategic partnership between FICO and Plaid, a leading open banking network. Launched earlier this year, the UltraFICO Score initiative represents a significant leap forward in alternative credit scoring methodology.
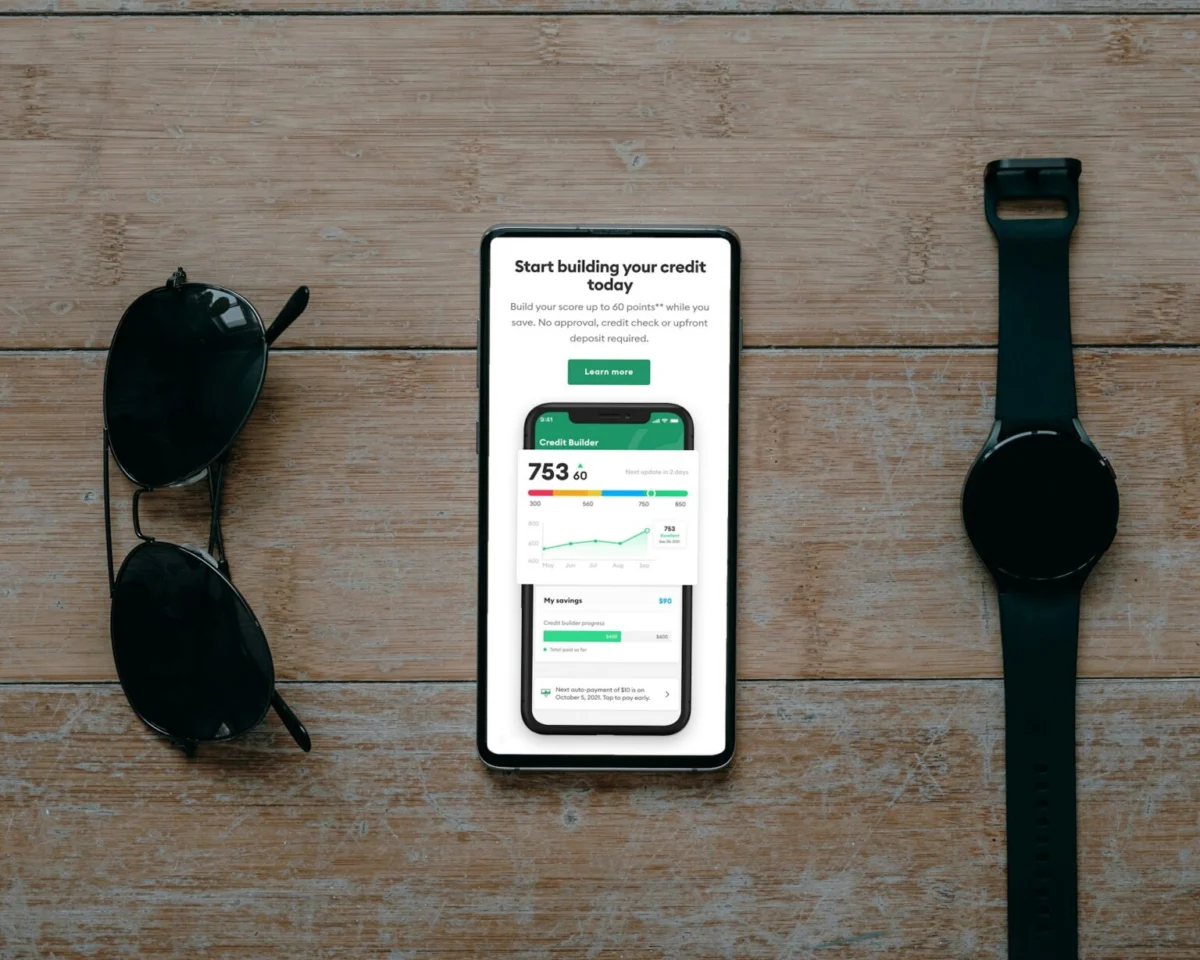
By leveraging secure open-finance application programming interfaces (APIs), the UltraFICO Score allows consumers to voluntarily link their checking, savings, or money market accounts to their credit evaluation process. The system analyzes cash flow data—such as the length of time bank accounts have been open, frequency and consistency of deposits, and the ability to maintain positive balances—and integrates these positive financial behaviors directly with traditional credit bureau data.
This collaborative approach empowers consumers to take an active role in shaping their credit profiles. For thin-file or subprime borrowers who manage their cash flow responsibly, the inclusion of banking data can boost their score, push them across underwriting thresholds, and unlock access to lower interest rates and prime credit products that would otherwise be out of reach.
During a featured discussion at FinovateFall 2026, Jaron Murphy, Head of Partnerships at FICO Scores, elaborated on the strategic importance of this development. Murphy underscored that the incorporation of cash flow analytics is not merely an incremental upgrade, but a fundamental reimagining of consumer evaluation.
"When you look at credit data and the credit report, it really shows what I call ‘willingness to pay,’" Murphy explained during the conference. "It’s looking at behavior to understand how willing the consumer is, based on past behavior and debt obligations, to repay this debt. There’s another part that’s always been missing though, and it’s that cash flow aspect. It’s the ability to pay, not just the willingness, but what is the consumer’s ability to pay, as well? That’s what really excites me about where we’re at today is being able to leverage cash flow data to understand consumers in new ways. And that’s what we’ve been embarking on."
The Expanding Role of Strategic Partnerships in Modern Lending
As Head of Partnerships at FICO Scores, Jaron Murphy occupies a critical nexus in the financial services ecosystem. His day-to-day responsibilities involve collaborating with key stakeholders across mortgage origination, consumer lending, and auto finance to expand the deployment and utility of FICO scoring models.
Murphy’s work focuses on developing robust distribution channels that introduce innovative credit solutions—such as UltraFICO—to new markets, financial institutions, and underserved demographics. In an increasingly competitive lending landscape, traditional banks and non-bank fintech lenders alike are seeking ways to expand their total addressable market without compromising risk management standards. By forging alliances with technology platforms like Plaid and embedding cash flow metrics into established credit infrastructures, FICO is enabling lenders to safely extend credit to segments of the population that legacy models previously misclassified as high risk.
The broader macroeconomic implications of these partnerships are profound. Financial inclusion is not solely a social imperative; it is an economic growth engine. When credit is democratized safely and accurately, consumer spending power increases, housing markets expand, small business entrepreneurship flourishes, and overall economic resilience is reinforced.
FICO: A Legacy of Analytics Meeting Modern Challenges
The company driving much of this technological evolution boasts a rich corporate history spanning seven decades. Founded in 1956 and headquartered in Bozeman, Montana, Fair Isaac Corporation pioneered the application of predictive analytics and data science to complex decision-making processes.
Over the past 70 years, FICO has evolved from a specialized analytics consultancy into the gold standard of consumer credit risk assessment. Today, FICO Scores are utilized by 90% of the top U.S. lenders, serving as the benchmark metric for credit evaluation across mortgages, auto loans, credit cards, and personal lending.
Beyond consumer credit scoring, FICO’s sophisticated enterprise solutions empower financial institutions, insurance providers, and major corporations to optimize operational decisions, combat sophisticated financial fraud, enhance enterprise risk management, and drive transparency across the financial lifecycle. As a Grade 4 sponsor of FinovateFall 2026, FICO demonstrated its ongoing commitment to engaging with the fintech community, highlighting how established market leaders can collaborate with agile technology innovators to solve enduring structural challenges.
Broader Industry Implications and the Road Ahead
The integration of cash flow data into mainstream credit scoring is rapidly transitioning from a forward-looking experiment to an industry-wide expectation. Regulators, consumer advocacy groups, and financial institutions are increasingly supportive of alternative data adoption, provided it adheres to strict standards of consumer privacy, data security, and algorithmic fairness.
For lenders, adopting cash flow-backed scoring models offers a distinct competitive advantage. In tightening credit cycles, lenders cannot afford to rely on blunt instruments that misprice risk or reject profitable, creditworthy borrowers. By gaining a 360-degree view of a consumer’s financial life—balancing historical debt repayment with real-time liquidity—financial institutions can make more nuanced, profitable, and inclusive lending decisions.
Looking ahead, the ongoing refinement of models like UltraFICO signals a promising horizon for financial services. As open banking regulations mature and data-sharing technologies become even more seamless, the barriers that have historically separated millions of deserving individuals from the formal financial system will continue to erode. Through the convergence of rigorous credit analytics, cash flow transparency, and strategic industry collaboration, the financial sector is steadily building a more inclusive, resilient, and accurate foundation for the future of lending.