Appalachian Community Capital (ACC), a prominent community development financial institution (CDFI) operating across the United States, has successfully raised $3.4 million in the initial tranche of its new community note series. The capital, secured from a coalition of mission-aligned institutional investors including Heron, Obran Capital Advisors, Trillium Asset Management, and Brown Advisory, marks a significant milestone in ACC’s ongoing efforts to channel flexible, long-term financing into historically underinvested rural communities throughout the Appalachian region.
The newly acquired funds will be deployed through ACC’s extensive network of 46 local lenders and community partners. This localized financing model is specifically designed to target critical infrastructure and economic growth sectors, ranging from small business development and affordable housing construction to community facilities, renewable energy transitions, and disaster recovery initiatives. As rural economies face mounting pressures from shifting industrial landscapes, environmental challenges, and historical economic neglect, this capital injection aims to provide grassroots organizations with the financial muscle necessary to foster sustainable, community-led recovery.
While the initial $3.4 million represents a strong start, ACC has outlined a far more ambitious long-term vision. The CDFI ultimately hopes to mobilize a staggering $250 million through the community investment note series. If successful, this multi-million-dollar mobilization effort could fundamentally transform the economic resilience of communities across the 13 states that comprise the Appalachian region, creating thousands of jobs and stabilizing essential local services.
The Genesis and Strategic Vision of ACC’s Community Notes
To understand the weight of ACC’s current fundraising initiative, it is necessary to examine the operational framework of the institution. Founded in 2015, Appalachian Community Capital was established to serve as a secondary market lender and financial intermediary for CDFIs operating within the Appalachian territory. Rather than lending directly to individual businesses or homebuyers, ACC operates as a "lender to lenders," providing debt and grant capital to trusted regional partners such as the Richmond, Virginia-based Locus, the Philadelphia-based Reinvestment Fund, and the South Carolina Community Loan Fund.
Since its inception a little over a decade ago, ACC has successfully deployed more than $50 million in debt and grants throughout the region. However, the leadership team recognized that traditional funding mechanisms—often bogged down by bureaucratic friction and rigid capital requirements—were failing to keep pace with the rapidly evolving needs of rural borrowers. In response, ACC officially initiated its community investment note series last year, designing a financial instrument tailored to bridge the gap between institutional impact investors and local, boots-on-the-ground CDFIs.
These community investment notes function as fixed-income securities that allow both institutional and accredited individual investors to put their capital to work in specific geographic areas. By purchasing these notes, investors provide ACC with the low-cost, patient capital required to issue long-term loans to local lenders. These local lenders, in turn, utilize their deep regional knowledge and established community trust to allocate funds where they are most urgently needed.
Voices from the Field: Investor Perspectives and Leadership Insights
The early success of the community note series has drawn praise from both ACC leadership and the participating institutional investors, who view the initiative as a model for modern impact investing.
"The need for flexible capital in rural and underserved communities is only growing," Daniel Wallace of Appalachian Community Capital stated in an interview with ImpactAlpha. "The early response to our ‘community investment notes’ gives us real confidence that there is investor appetite for this approach." Wallace emphasized that the modern economic landscape demands innovative financial products that bypass traditional urban-centric banking channels and direct liquidity straight to the communities that need it most.
Institutional investors participating in the initial round have echoed these sentiments, highlighting the unique structure of the notes as a direct pipeline to overlooked markets. Felelia Lucky of Heron noted that the community investment notes "offer a direct and practical way to get flexible dollars into the hands of CDFIs who already have the trust and track record to put them to work." Lucky added, "Capital works best when it’s rooted in the communities it’s meant to serve."
This sentiment was reinforced by Leo Freeman of Obran Capital Advisors, who underscored the historical context of the region’s economic struggles. "Investing in ACC gave our clients the opportunity to invest capital directly into an area of the US that has experienced systematic disinvestment," Freeman remarked. By framing the investment as an act of economic correction rather than mere philanthropy, Obran Capital and its peers are helping to shift the paradigm of how institutional wealth views rural America.
The Broader Socioeconomic Context of Appalachia
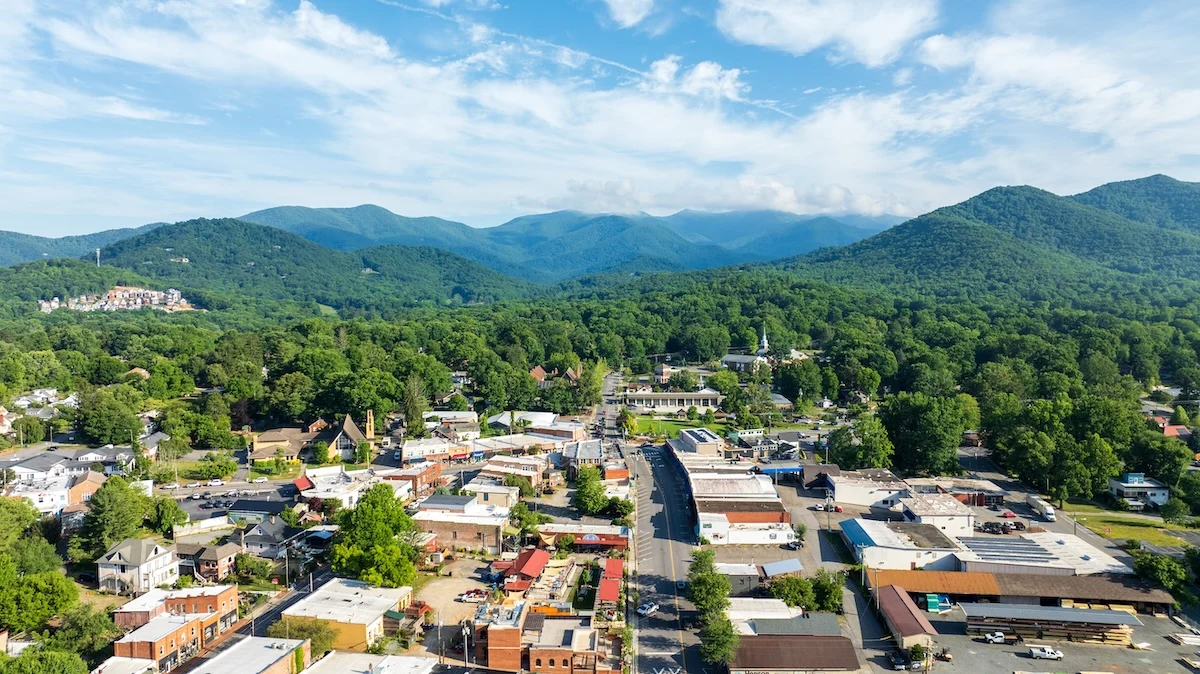
Appalachia has long battled economic vulnerabilities rooted in its historical reliance on extraction-based industries, primarily coal mining and heavy manufacturing. As global energy markets transition and automation reshapes industrial labor, many Appalachian counties have experienced prolonged periods of population decline, brain drain, crumbling infrastructure, and tax base erosion.
Compounding these structural challenges is a severe lack of traditional banking infrastructure. Over the past two decades, rural banking deserts have expanded significantly as major commercial banks closed physical branches in favor of digital banking and urban consolidation. Without local bank branches willing to take risks on rural enterprises, small business owners, real estate developers, and municipal leaders frequently find themselves locked out of conventional credit markets.
This is precisely the gap that Community Development Financial Institutions and intermediaries like ACC were created to fill. CDFIs are specialized financial institutions certified by the U.S. Department of the Treasury’s Community Development Financial Institutions Fund. They are explicitly mandated to provide financial services to low-income communities and people who lack adequate access to traditional financing. By pooling resources through community notes, ACC strengthens the balance sheets of these regional CDFIs, enabling them to absorb higher risks and offer more favorable loan terms to local borrowers.
Sector-Specific Impacts: Where the Capital Flows
The deployment of the $3.4 million raised in this initial tranche—and the eventual $250 million target—will not be restricted to a single economic sector. Instead, ACC’s network-based deployment strategy ensures that capital is distributed across five critical pillars of regional development:
-
Small Business and Entrepreneurship: Small businesses form the backbone of rural economies, yet access to working capital remains a persistent barrier. ACC-backed loans help local entrepreneurs launch new storefronts, upgrade equipment, hire local workers, and weather economic downturns.
-
Affordable Housing: The lack of safe, energy-efficient, and affordable housing is a primary driver of workforce migration out of Appalachia. Financing provided through network lenders supports the construction and rehabilitation of single-family homes and multi-family affordable housing developments.
-
Community Facilities: Vital public and non-profit infrastructure—such as rural healthcare clinics, childcare centers, educational facilities, and community gathering spaces—often struggle to secure commercial financing. CDFIs use flexible debt to fill these funding gaps.
-
Renewable Energy Transitions: As parts of Appalachia transition away from a fossil-fuel-dominated economy, investments in solar, wind, and biomass energy projects create new, sustainable job opportunities while lowering long-term energy costs for rural residents and businesses.
-
Disaster Recovery and Climate Resilience: Appalachia is increasingly vulnerable to extreme weather events, including severe flooding and landslides. Capital directed toward disaster recovery helps communities rebuild stronger, modernize stormwater management, and harden critical infrastructure against future climate shocks.
Implications for the Future of Impact Investing
The rollout of Appalachian Community Capital’s community investment note series arrives at a pivotal moment for the broader impact investing industry. For years, environmental, social, and governance (ESG) and impact portfolios have heavily favored urban technology ventures, clean energy projects on the coasts, and international development initiatives. Rural America, despite containing profound economic need and high-potential investment opportunities, has frequently been overlooked by mainstream institutional allocators due to perceived high transaction costs and a lack of standardized financial intermediaries.
By proving that institutional capital can be successfully aggregated and funneled into rural CDFIs at scale, ACC is establishing a replicable blueprint for rural investment across the United States. If ACC successfully mobilizes its targeted $250 million, it could serve as a powerful proof-of-concept for other regional intermediaries seeking to attract institutional wealth to America’s heartland.
Furthermore, the participation of diverse financial institutions—ranging from private wealth managers like Brown Advisory and Trillium Asset Management to foundation-backed investors like Heron—signals a growing maturation within the impact investing space. Investors are increasingly demanding measurable, place-based outcomes that address systemic inequalities rather than relying solely on generalized corporate sustainability metrics.
Looking Ahead: Next Steps for ACC and Its Network
As Appalachian Community Capital moves past its initial $3.4 million milestone, the organization’s leadership is turning its focus toward expanding the distribution of the community note series to a broader pool of accredited and institutional investors. The success of subsequent tranches will largely depend on the performance of the initial loans and the continuous demonstration of tangible, on-the-ground socioeconomic benefits across the 46 network communities.
For the local lenders within ACC’s network, the arrival of this flexible capital cannot come soon enough. With inflation, rising interest rates, and supply chain pressures continuing to strain rural economies, the availability of patient, mission-driven debt provides a vital lifeline. As these funds begin to circulate through main streets, construction sites, and renewable energy installations across the hills and valleys of Appalachia, they carry with them the potential to rewrite the economic narrative of a region long overdue for reinvestment.