As the 2026 fiscal year crosses its midpoint, Wealthfront has signaled a significant shift in its operational strategy, moving beyond its foundational automated investing roots to embrace a broader, more integrated financial ecosystem. The company, known for its robo-advisory services, has spent the first half of the year executing a series of infrastructure enhancements designed to underpin a new generation of products. This pivot reflects a broader industry trend toward "all-in-one" financial platforms, where the objective is to centralize banking, investing, and lending into a single, automated interface.
The Strategic Pivot: Infrastructure as the Foundation
The core of Wealthfront’s 2026 roadmap is not merely the introduction of consumer-facing features, but the underlying plumbing of its financial engine. By investing heavily in backend infrastructure, the firm is positioning itself to handle greater transaction volumes and more complex asset classes. This transition is essential for scaling its "build, borrow, and save" philosophy. According to company leadership, these enhancements are expected to facilitate a wave of new product launches slated for late 2026 and early 2027.
The importance of this technical foundation cannot be overstated. In an environment defined by rapid fluctuations in interest rates and shifting consumer demands, the ability to deploy new financial instruments—such as tax-optimized accounts or high-frequency trading integrations—requires a robust, scalable architecture. By upgrading its core systems, Wealthfront is reducing the latency between product conceptualization and market deployment.
New Horizons in Investing: Custodial Accounts and Global Equities
A major highlight of the year has been the expansion of the platform’s investment capabilities. The introduction of the Wealthfront Custodial Account is a significant development, addressing a long-standing demand for multigenerational wealth planning. Unlike traditional custodial accounts, which are often siloed from tax-loss harvesting and other automated optimization strategies, Wealthfront’s version is engineered to manage the tax burden proactively before ownership is transferred to the beneficiary.
Simultaneously, the firm has expanded its Stock Investing Account to include over 300 new securities. This expansion is particularly noteworthy for its inclusion of major international players, such as Taiwan Semiconductor (TSM), ASML Holdings (ASML), and Novo Nordisk (NVO). The inclusion of these foreign stocks allows retail investors to gain exposure to global growth sectors—specifically semiconductor manufacturing and pharmaceutical innovation—without needing to navigate the complexities of international brokerage accounts.
This shift toward individual stock selection alongside automated portfolios suggests a hybrid model, catering to both the "set-it-and-forget-it" investor and the active participant who wants to tilt their portfolio toward specific themes or companies. The addition of dividend reinvestment control—allowing users to either compound their earnings or sweep them into cash accounts—further empowers users to tailor their cash flow strategies to their immediate needs.
Financial Literacy and Market Intelligence
In an era of information overload, Wealthfront has entered the content space with the launch of its biweekly newsletter, Vested Interest. The publication serves as an educational bridge between the platform’s tools and the broader macroeconomy. By providing analysis on interest rate environments, home affordability, and the impact of artificial intelligence on market valuations, the firm is attempting to foster a more informed user base. Data suggests that platforms providing contextual economic education see higher user engagement and longer-term retention, as investors are less likely to react impulsively to market volatility when they are provided with clear, data-driven explanations of current trends.
Frictionless Life-Stage Transitions
Financial institutions have historically struggled with the operational friction involved in life-stage transitions, such as marriage, divorce, or bereavement. Wealthfront has moved to automate these processes, particularly regarding the movement of assets between Individual and Joint accounts. By enabling the transfer of assets without the need to liquidate—thereby avoiding capital gains tax triggers—the platform is solving a significant pain point for households managing shared finances.
Automating these workflows for difficult life events, such as divorce or the death of a spouse, represents a move toward empathetic engineering. While these features may not drive immediate revenue, they build deep brand loyalty and trust, which are critical in the competitive landscape of digital finance.
Maximizing Cash Utility: Yields and Automation
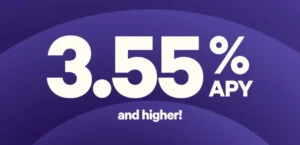
The Cash Account remains a centerpiece of the Wealthfront experience. In the current economic climate, where liquidity is highly valued, the firm has maintained a competitive base APY of 3.55% through its network of program banks. The inclusion of a 0.25% APY boost for users who maintain specific direct deposit or recurring investment thresholds is a calculated incentive program designed to lock in consistent user liquidity.
Beyond yield, the platform has introduced automated savings features that allow for "category-based" management. Users can now route interest into distinct "buckets," such as emergency or vacation funds, with visual progress tracking. This functionality, while seemingly simple, leverages behavioral economics to help users visualize their savings progress, a strategy proven to increase personal savings rates.
Furthermore, the integration of real-time payment rails like RTP and FedNow has fundamentally changed the speed at which users can interact with their money. By surpassing the limitations of traditional ACH transfers, Wealthfront is meeting the expectations of a modern consumer who demands immediate access to their funds.
Modernizing Security
The shift toward passkey authentication and biometric login (Face ID and Touch ID) reflects a necessary evolution in security. As cyber threats become more sophisticated, moving away from legacy password systems is a security best practice that also improves the user experience. By reducing login friction, the firm encourages more frequent interaction with the app, which in turn fosters better financial habits.
Disrupting the Home Lending Market
Wealthfront’s foray into home lending continues to be an outlier in the digital banking space. By removing the traditional mortgage broker and the associated high-pressure sales calls, the firm is attempting to commoditize the mortgage process. Offering rates approximately 50 basis points below the national average is a significant value proposition, though it remains restricted by geographic and credit-based criteria. The success of this model will depend on the firm’s ability to maintain high approval speeds while managing the regulatory overhead associated with the mortgage industry.
Future Implications and Market Analysis
Looking ahead to the remainder of 2026, the trajectory for Wealthfront is clear: it is evolving from a single-product robo-advisor into a comprehensive financial operating system. The implications of this are twofold. First, for the consumer, it provides a centralized dashboard that reduces the mental load of managing disparate financial accounts. Second, for the industry, it pressures traditional banks to modernize their own legacy infrastructures to compete with the speed and efficiency of a digitally native platform.
The firm’s reliance on automated operations and self-service models suggests that it is betting heavily on the fact that users prefer efficiency over human intervention. As long as the platform can maintain its security posture and continue to provide clear, actionable insights through products like Vested Interest, it is well-positioned to capture a larger share of the retail financial services market.
However, the path forward is not without challenges. The reliance on program banks for its cash sweep program and the regulatory complexities of the mortgage market require constant oversight. Furthermore, as the platform adds more features, the risk of "feature creep"—where an application becomes too complex for the average user—must be managed through careful UI/UX design.
In conclusion, the first half of 2026 has been a period of foundational growth for Wealthfront. By prioritizing infrastructure, automating complex financial transitions, and expanding its investment offerings, the company has created a robust framework for long-term growth. Whether these efforts will successfully translate into market dominance in the broader fintech sector remains to be seen, but the current strategy demonstrates a clear understanding of the modern consumer’s desire for a seamless, efficient, and intelligent financial life.