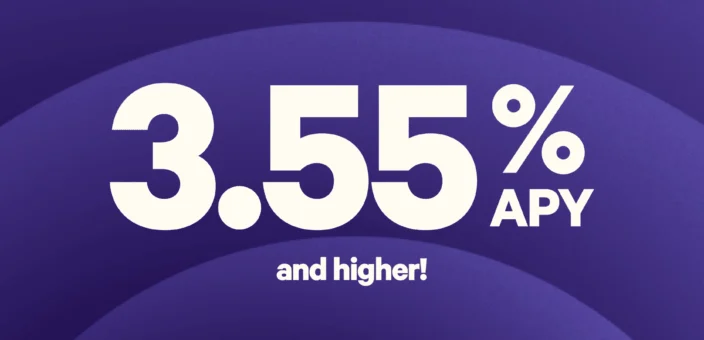
Wealthfront has officially increased the base annual percentage yield (APY) for its Cash Account clients to 3.55%, a move prompted by the Federal Reserve’s recent decision to raise the federal funds rate by 0.25 percentage points. This adjustment marks the latest in a series of shifts within the fintech sector as companies navigate the evolving interest rate environment. For depositors, the update offers a significantly higher return on liquid capital compared to the national average, which currently sits at approximately 0.39% according to data from the Federal Deposit Insurance Corporation (FDIC) as of early 2026.
The Mechanism of Wealthfront’s Yield Strategy
The core of Wealthfront’s banking-adjacent model lies in its partnership with a network of program banks. While Wealthfront is a brokerage firm and not a traditional bank, it utilizes a sweep program to move uninvested cash into these partner institutions. By aggregating deposits from its client base, Wealthfront is able to negotiate deposit rates that often exceed those available to individual retail consumers at traditional brick-and-mortar banks.
This structure allows Wealthfront to act as an intermediary, capturing the spread between the rates offered by institutional partners and the yield provided to the end user. When the Federal Reserve adjusts the federal funds rate, these partner banks typically update their interest rate offerings for deposits. Wealthfront’s decision to pass the 0.25% increase directly to its clients is intended to maintain competitiveness in a market where retail investors are increasingly sensitive to yield differentials.
Chronology of Recent Rate Developments
The financial landscape has been defined by volatility and strategic adjustments since the Federal Reserve began its campaign to manage inflation through interest rate policy.
- Mid-2025: Throughout the middle of the year, the Federal Reserve signaled a data-dependent approach to monetary policy, keeping the federal funds rate elevated to combat persistent inflationary pressures.
- Late Q3 2026: On September 16, 2026, the Federal Open Market Committee (FOMC) finalized a 0.25% hike, responding to updated labor market data and consumer price indices.
- September 18, 2026: Wealthfront formally announced the update to its Cash Account base rate, moving the yield to 3.55% APY. This transition was automated for all existing clients, requiring no action from account holders to receive the improved rate.
Maximizing Yields: The "Boost" Ecosystem
Beyond the base rate of 3.55%, Wealthfront maintains a multi-tiered promotional structure designed to incentivize specific financial behaviors. Clients can effectively increase their yield up to 4.55% by satisfying certain eligibility requirements. These criteria are primarily designed to encourage long-term financial stability and high-volume engagement with the platform.
To access the higher tiers of APY, users must engage with the platform’s "Recurring Deposit Plus Investing" program. Eligibility hinges on two primary paths:
- Direct Deposit: Maintaining a minimum of $1,000 in monthly recurring ACH direct deposits of income into the Cash Account.
- External Transfers: Setting up at least $2,500 per month in automated recurring electronic deposits from an external source into either the Cash Account or an associated investment account.
These incentives serve a dual purpose: they secure a reliable flow of capital for the brokerage and encourage users to consolidate their financial activities within the Wealthfront ecosystem. By linking the yield boost to both banking and investment behaviors, Wealthfront positions its Cash Account as a foundational hub for personal wealth management.
The Competitive Landscape and Market Context
The fintech industry’s push for higher yields has created a competitive arms race for customer deposits. As interest rates remain elevated, traditional banks have been slower to pass on rate hikes to savings account holders, keeping their own net interest margins high. Conversely, neobanks and automated investment platforms have used high-yield cash accounts as a primary acquisition tool to pull customers away from traditional institutions.
Financial analysts note that this trend represents a broader shift in consumer behavior. During periods of low interest rates, cash was often viewed as a "dead" asset, parked in non-interest-bearing checking accounts. In the current 2026 environment, however, investors are treating cash as a strategic asset class. Wealthfront’s offering is specifically designed to bridge the gap between short-term liquidity and long-term investment, providing a place where funds can earn meaningful interest while remaining ready for market entry.
Regulatory Disclosures and Risk Management
While the elevated APY is a significant benefit to clients, it is accompanied by a complex regulatory framework. Wealthfront emphasizes that it is not a bank, and its Cash Account is not a traditional bank deposit account. Instead, funds are swept into participating program banks, which are the entities responsible for providing the interest and the underlying FDIC insurance.
The FDIC pass-through insurance coverage is limited to $250,000 per ownership category per banking institution. Wealthfront mitigates this risk by partnering with multiple banks, allowing the platform to extend up to $8 million in aggregate coverage for individual accounts, and up to $16 million for joint accounts. However, the onus remains on the client to monitor their total deposits across these banks to ensure they do not exceed insurance thresholds.
Furthermore, while the cash is at the brokerage firm or in transit, it is covered by the Securities Investor Protection Corporation (SIPC), which protects against the failure of the brokerage itself, though it does not protect against the loss of the value of the investment or the failure of the program banks.
Implications for Personal Finance Management
The introduction of these higher rates reflects a maturing of the digital finance sector. By integrating features such as the Wealthfront Visa Debit Card, mobile check deposit, and the ability to organize funds into specific savings categories, the company is attempting to provide a comprehensive banking experience without the overhead of physical branch networks.
For the retail investor, the implications are two-fold. First, the 3.55% base rate—and the potential for 4.55%—provides a viable hedge against inflation for cash that would otherwise be stagnant. Second, the requirement for recurring deposits encourages the habit of "paying oneself first," a core tenet of long-term wealth accumulation.
As the Federal Reserve continues to evaluate the trajectory of the economy, analysts expect that interest rates may remain in a "higher for longer" posture, provided that inflation remains near the central bank’s targets. Consequently, the yields on cash accounts are likely to remain a central point of competition for fintech platforms. Wealthfront’s recent move indicates that they intend to stay at the forefront of this competition, leveraging their automated architecture to provide rapid responses to macroeconomic changes.
Conclusion: The Future of Digital Cash Management
Wealthfront’s latest announcement is more than just a rate hike; it is a signal of the evolving role of the brokerage firm in the daily financial life of the American consumer. By removing market risk from the cash management process while simultaneously boosting returns through banking partnerships, Wealthfront is effectively narrowing the divide between traditional savings accounts and investment brokerage accounts.
As users continue to seek out higher returns with minimal friction, the success of these programs will likely depend on the transparency of the sweep process and the reliability of the underlying partner banks. For the present, the increase to 3.55%—and the associated pathways to higher yields—offers a compelling argument for users to reconsider where they hold their short-term savings and everyday operating cash. Moving forward, the industry will watch closely to see how these automated platforms maintain their margins while continuing to offer market-leading yields in a high-interest rate environment.