As the fiscal year 2026 progresses, Wealthfront, the Palo Alto-based automated investment platform, has initiated a comprehensive suite of updates aimed at fundamentally altering how retail investors build, borrow, and manage their personal finances. Following a series of strategic infrastructure overhauls designed to bolster platform scalability and security, the firm has rolled out a succession of product enhancements that address the evolving needs of its client base, ranging from custodial wealth management to streamlined home financing and modernized liquidity solutions.
The recent flurry of activity represents a significant departure from standard iterative updates. By focusing heavily on backend stability, the company has cleared the path for a more modular approach to product development, enabling the rapid deployment of features that were previously restricted by technical limitations. This pivot toward "infrastructure-first" development is expected to yield even greater product diversification in the closing months of 2026.
Expanding the Horizons of Wealth Accumulation
Central to Wealthfront’s recent updates is the launch of the Wealthfront Custodial Account. Historically, custodial accounts—or Uniform Transfers to Minors Act (UTMA) accounts—have been characterized by administrative friction and limited investment options. Wealthfront’s iteration seeks to democratize access to sophisticated wealth management for the next generation. By integrating its signature automated investment engine, the account is engineered to automatically optimize for tax efficiency, a critical feature for parents looking to build long-term capital for their children’s future milestones, including home down payments or career startups, rather than just traditional educational expenses.
Parallel to this, the platform’s Stock Investing Account has undergone a substantial expansion. With the inclusion of over 300 new securities, the platform is addressing a long-standing demand for increased global exposure. The addition of high-profile international equities, such as Taiwan Semiconductor Manufacturing Company (TSM), ASML Holdings (ASML), and Novo Nordisk (NVO), reflects an acknowledgment of the increasingly global nature of the modern retail investor’s portfolio. The redesign of the search interface, coupled with enhanced dividend management tools—allowing users to choose between automatic reinvestment or sweeping proceeds into high-yield cash accounts—signals a commitment to providing a "one-stop-shop" experience that blends the simplicity of robo-advisory with the granularity of self-directed brokerage.
Bridging the Gap: Life Stage Transitions and Financial Consolidation
A notable challenge in retail finance is the administrative burden associated with major life transitions, such as marriage, divorce, or the death of a family member. Wealthfront has invested in automated operational workflows to minimize the manual labor typically associated with these events.
Specifically, the platform has introduced a seamless mechanism for migrating assets from an Individual Investing Account to a Joint Account. In the traditional financial sector, this move often necessitates the liquidation of assets, which triggers taxable events and disrupts long-term compounding. Wealthfront’s new "self-serve" transfer process allows for the movement of assets without triggering a gain or loss, a feature that provides significant utility for couples looking to consolidate their financial lives. This initiative is emblematic of a broader industry trend toward reducing the friction associated with account portability and inter-account mobility.
Maximizing Yields in a Competitive Interest Rate Environment
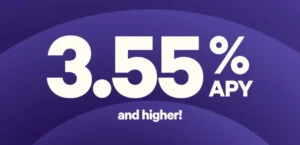
In the landscape of 2026, where monetary policy remains a focal point for the retail investor, Wealthfront has refined its Cash Account offerings to remain competitive against both traditional banks and high-yield fintech alternatives. The current offering features a 3.55% base APY, which is bolstered by a 0.25% yield incentive for clients who maintain specific direct deposit or recurring investment requirements.
The strategic rationale behind this structure is twofold: it encourages the "stickiness" of capital by incentivizing recurring behavior, and it provides a reliable, low-risk parking spot for liquid capital. Beyond interest rates, the integration of real-time payment networks, such as RTP and FedNow, has fundamentally altered the velocity of money on the platform. By moving away from legacy ACH transfer speeds toward near-instantaneous liquidity, Wealthfront is effectively positioning its Cash Account as a primary transaction hub rather than merely a passive holding account.
The Evolution of Home Lending
The mortgage sector has historically been one of the most sluggish areas of consumer finance, defined by high fees and opaque pricing models. Wealthfront’s home lending arm continues its efforts to disrupt this segment by utilizing a digital-first, zero-sales-call model. By stripping out the traditional commission-based structure of mortgage origination, the firm reports that it can offer rates approximately 50 basis points lower than the national average.
The implications for the borrower are substantial. In a high-interest rate environment, a 0.50% reduction in a mortgage rate can translate to tens of thousands of dollars in lifetime savings. By focusing on a self-serve digital experience, Wealthfront is targeting a demographic that is increasingly comfortable with managing high-stakes financial transactions through secure mobile interfaces rather than through intermediaries.
Analytical Perspective: The "Platform" Strategy
Industry analysts view Wealthfront’s 2026 trajectory as a classic example of "platform expansion." Having established a dominant position in automated index-based investing, the company is now vertically integrating its service offerings to capture a larger share of the household wallet. The introduction of the Vested Interest newsletter serves as a strategic content layer, designed to foster client engagement and provide necessary educational context for the firm’s evolving product ecosystem.
From a technical standpoint, the integration of passkey support and enhanced biometric authentication (Face ID/Touch ID) reflects a broader mandate across the fintech sector to prioritize security without sacrificing user experience. As the firm manages a larger percentage of client net worth, the pressure to maintain robust cybersecurity infrastructure has reached an all-time high.
Chronology of 2026 Developments
- Q1 2026: Initial focus on backend infrastructure upgrades to increase data processing capacity and reduce latency in account-to-account transfers.
- Early Q2 2026: Launch of the Custodial Account, expanding the firm’s reach into intergenerational wealth planning.
- Mid Q2 2026: Rollout of the Vested Interest newsletter to enhance investor literacy and market context.
- Q3 2026: Expansion of the Stock Investing Account, adding 300+ securities and refining dividend management tools.
- Late Q3 2026: Implementation of streamlined asset-transfer protocols for joint accounts, specifically targeting the removal of tax friction during account consolidation.
Future Outlook
Looking toward the remainder of 2026 and into 2027, the firm has signaled that further automation is on the horizon. While specific details remain guarded, the roadmap suggests continued efforts in supporting recurring investment strategies and further diversifying the stock and ETF offerings.
The broader implications of these updates are clear: the retail financial landscape is moving toward a highly automated, low-friction, and increasingly consolidated model. For Wealthfront, the challenge will be to maintain this pace of innovation while ensuring that the complexity of its expanded product suite does not undermine the simplicity that originally attracted its user base.
Disclosure and Regulatory Context
As with all financial platforms operating in the United States, Wealthfront’s recent updates are subject to a complex regulatory framework. It is essential to note that while the Cash Account provides high-yield opportunities, it is not a traditional bank account; rather, it is a cash sweep program where funds are held at program banks. Investment advisory services are provided by Wealthfront Advisers LLC, an SEC-registered investment adviser, while brokerage services are handled by Wealthfront Brokerage LLC, a member of FINRA/SIPC.
All investors are cautioned that the market remains volatile and that past performance—whether in stock investing or cash yield—is not indicative of future results. The firm’s recent focus on simplifying financial logistics for life events like divorce or death remains a significant, if often overlooked, contribution to the consumer fintech space, highlighting that for many, the value of a platform lies as much in its operational efficiency as in its investment returns. As Wealthfront enters the final quarter of the year, the industry will be watching to see if its infrastructure-first strategy can sustain the momentum required to challenge larger, incumbent financial institutions.