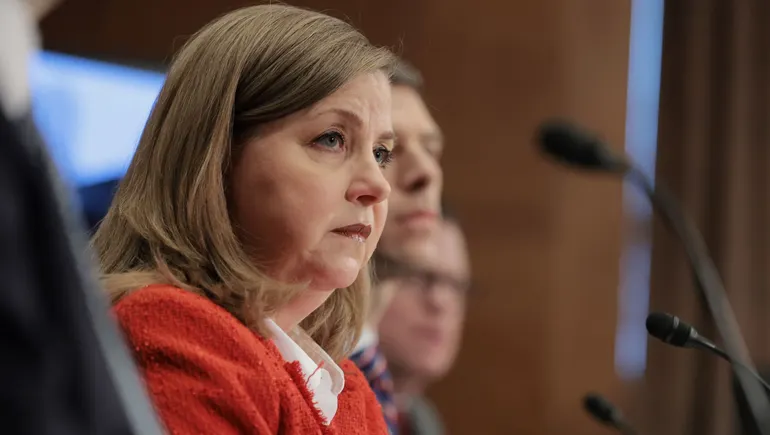
In a significant address delivered at a banking luncheon in London this past Friday, Federal Reserve Governor Michelle Bowman outlined a comprehensive roadmap for reforming the U.S. central bank’s approach to bank stress tests and supervisory oversight. Her remarks, which synthesized upcoming regulatory updates with a critical retrospective of the 2023 collapse of Silicon Valley Bank (SVB), suggest a shift toward greater transparency, proactive risk identification, and improved institutional accountability. As the Federal Reserve navigates a complex environment of evolving financial threats, Bowman’s comments underscore an urgent need to modernize the tools used to gauge the health of the nation’s largest financial institutions.
The proposed revisions represent the latest development in a long-standing debate over the efficacy of the Dodd-Frank Act’s stress testing requirements. For years, the banking industry has criticized the current framework for its perceived opacity and lack of dialogue between regulators and the supervised entities. By signaling a move toward more interactive scenario analysis and clarified capital requirements, the Fed appears to be responding to both industry pressure and the hard-learned lessons of the regional banking crisis that unfolded in the spring of 2023.
A Timeline for Regulatory Finalization
Governor Bowman confirmed that the Federal Reserve is entering the final stages of its policy-making cycle regarding bank capital requirements. The central bank is expected to announce final revisions to its stress-testing framework in the coming weeks. These updates will address key components of the Basel III Endgame proposals, including the risk-based capital requirements and the G-SIB (Global Systemically Important Bank) surcharge.
The urgency of these reforms is compounded by ongoing legal challenges. Earlier this month, a prominent financial advocacy group filed a lawsuit against the Federal Reserve and Governor Bowman, alleging procedural irregularities and improper influence in the rulemaking process for capital requirements. Despite these legal headwinds, Bowman emphasized that the Fed remains committed to finalizing these rules to provide the financial sector with the long-awaited certainty needed for strategic planning and capital allocation.
Evolving the Stress Testing Methodology
A core component of Bowman’s address was the integration of public feedback into the Fed’s annual stress-test scenarios. The current model, which has been criticized for failing to capture real-time market shifts, is slated for several technical adjustments. Among the most notable proposals is the "balance sheet freeze" concept. Under this model, a bank’s balance sheet would be effectively locked at a specific date prior to the release of the Fed’s stress scenarios, preventing the "gaming" of the system and ensuring that the test reflects a static, high-stress environment.
Furthermore, the Fed is considering a dual-scenario approach for global market shocks. By creating two distinct stress scenarios and applying the one that results in the larger loss, the regulator aims to better calibrate a bank’s stress capital buffer (SCB). This, Bowman argued, would move the industry away from an "opaque and unnecessarily unpredictable framework."
Looking toward the 2027 testing cycle, Bowman introduced a proposal to overhaul the model for evaluating noninterest income. As large banks increasingly rely on fee-based revenue—such as wealth management, investment banking, and market-making—the current models often fail to capture the volatility of these streams during periods of market turmoil. By seeking public comment on these revisions, the Fed is signaling a broader attempt to incorporate modern banking business models into its traditional capital adequacy assessments.
Retrospective Analysis: The Silicon Valley Bank Failure
Perhaps the most poignant portion of Bowman’s address was her analysis of the failure of Silicon Valley Bank (SVB). Utilizing the results of an independent review, she painted a picture of a supervisory failure characterized by inaction and bureaucratic inertia. According to the review, the Fed’s supervisory staff identified significant vulnerabilities within SVB as early as March 2022. These warnings, however, did not lead to prompt, decisive intervention.
Bowman noted that had the Fed’s proposed stress-test methodology been applied to SVB’s portfolio at the time, the results would have been stark. A simulation of a plausible recession scenario, factoring in rising interest rates and the fair-value assessment of held-to-maturity investment securities, would have shown SVB’s capital falling below regulatory minimums as early as the fourth quarter of 2021. The fact that this vulnerability was not acted upon highlights a systemic issue within the Fed: a culture of risk aversion where staff were hesitant to take corrective measures for fear of being wrong.
The review also pointed to a lack of clear accountability regarding decision-making hierarchies. When faced with ambiguous risk signals, the decentralized nature of the Fed’s supervisory apparatus resulted in a "wait and see" approach, which proved fatal when SVB faced a massive, rapid-onset liquidity run in March 2023.
Implications for the Future of Supervision
The implications of Bowman’s remarks extend far beyond the technical details of capital requirements. The shift toward "two-way communication" in scenario analysis suggests that the Fed wants to move away from a "black box" approach to supervision. By encouraging banks to design and assess their own performance in extreme scenarios, the Fed hopes to foster a culture where institutions take more ownership of their risk profiles.
"Fed stress tests should do more for our supervisors than calculate a single capital requirement," Bowman stated. "They should also identify a firm’s vulnerability to various material financial and nonfinancial risks before those risks emerge." This indicates that the central bank is moving toward a more qualitative, continuous monitoring model, rather than relying solely on the binary "pass-fail" results of annual quantitative exercises.
Industry analysts suggest that this shift could lead to a more nuanced regulatory environment. Banks that proactively identify and disclose their own vulnerabilities may find themselves under less aggressive supervisory scrutiny than those that maintain a more reactive posture. However, this also places a greater burden on bank boards and risk committees to demonstrate robust internal governance.
Context and Broader Financial Stability
The collapse of SVB in March 2023—followed by the failures of Signature Bank and First Republic Bank—triggered a period of significant instability in the U.S. banking sector. The rapid increase in interest rates by the Federal Reserve, intended to combat inflation, had the unintended consequence of devaluing the high-quality, long-term bonds held by these banks. The resulting unrealized losses, combined with an influx of uninsured deposits and high-speed digital banking capabilities, created a "perfect storm" that the existing regulatory framework was ill-equipped to handle.
The subsequent independent review, which Bowman referenced, serves as a cornerstone for the Fed’s current reform agenda. The review concluded that supervision was hampered by a lack of urgency, a reluctance to use existing enforcement tools, and a failure to adapt to the changing risk profile of a firm that had grown rapidly.
Conclusion and Path Forward
Governor Bowman’s London address serves as a clear acknowledgment that the Federal Reserve’s supervisory infrastructure must evolve to match the speed and complexity of modern global finance. By promising a more transparent, predictable, and interactive stress-testing framework, the Fed is attempting to restore public confidence that was severely shaken during the regional banking crisis.
As the central bank moves to finalize these rules, the eyes of the financial world will be on the implementation process. Whether these changes will be sufficient to prevent a repeat of the 2023 failures remains to be seen. However, the move to integrate historical lessons from the SVB collapse into the future of stress testing suggests that the Federal Reserve is at least prepared to address the structural and cultural gaps that have historically undermined its supervisory efforts. As Bowman concluded, the goal is not to assign blame for past failures, but to build a more resilient financial system that can withstand the inevitable stresses of the future. The coming weeks, as the Fed releases its final framework, will be a critical litmus test for the central bank’s ability to turn these promises into reality.