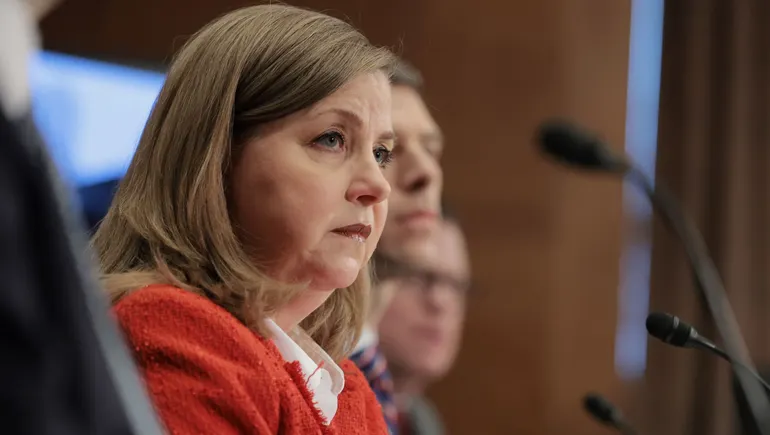
Federal Reserve Vice Chair for Supervision Michelle Bowman utilized a high-profile luncheon in London on Friday to signal a major transition in how the United States central bank oversees the nation’s largest financial institutions. Her remarks served a dual purpose: outlining a definitive timeline for long-awaited regulatory reforms and providing a sobering retrospective on the systemic failures that led to the collapse of Silicon Valley Bank (SVB) in 2023. By connecting the dots between current stress-testing methodologies and the institutional inertia that failed to prevent SVB’s demise, Bowman underscored a pivot toward a more proactive, diagnostic, and transparent supervisory culture.
A Looming Regulatory Deadline
The most immediate takeaway from Bowman’s address is the acceleration of the Fed’s regulatory agenda. Bowman confirmed that the Federal Reserve is entering the final stages of its deliberations regarding the stress testing framework, with official revisions expected to be published in the coming weeks. These changes are part of a broader package that includes finalized risk-based capital requirements and adjustments to the surcharges applied to global systemically important banks (G-SIBs).
This policy push arrives at a contentious time. The proposed changes to capital requirements—the so-called "Basel III Endgame" proposals initially introduced in March—have faced fierce pushback from the banking industry and, more recently, legal challenges. Last week, the advocacy group Better Markets filed a lawsuit against the Federal Reserve and Bowman herself, alleging that the rulemaking process surrounding these capital requirements was tainted by undisclosed meetings with banking executives. Despite the legal headwinds, Bowman’s comments suggest that the Fed remains committed to its stated timeline, aiming to modernize the framework rather than abandon it.
Refinement of the Stress Test Mechanism
At the heart of the proposed reforms is an effort to move away from what Bowman described as an "opaque and unnecessarily unpredictable" system. The Federal Reserve has been soliciting public input on how to make stress tests more representative of actual market volatility.
Bowman highlighted two specific, high-impact proposals currently under review. The first involves the implementation of a "balance sheet freeze" date. Under this model, banks would have their balance sheets effectively locked at a specific point in time prior to the release of the Fed’s annual stress scenarios. This would allow for a cleaner, more controlled assessment of risk without the interference of dynamic mid-test portfolio changes.
The second, perhaps more significant, recommendation involves the creation of a "dual shock" scenario model. Currently, the Fed applies a set of stress scenarios to gauge how a bank’s capital buffers would hold up under duress. The new proposal suggests running two distinct global market shock scenarios simultaneously, with the final stress capital buffer calculated based on whichever scenario results in the larger loss. By forcing banks to prepare for the most severe permutation of multiple market shocks, the Fed hopes to build a more resilient capital foundation.
Looking further ahead, Bowman signaled that 2027 will see the introduction of a new, more granular model for evaluating noninterest income. This category—encompassing revenue from wealth management, investment banking, market making, and fee-based services—has become an increasingly volatile component of large bank earnings. By subjecting these income streams to more rigorous stress modeling, the Fed intends to close the gap between traditional credit risk assessment and the complexities of modern, diversified financial services.
The Lessons of Silicon Valley Bank
Bowman’s critique of the status quo was rooted in the failure of Silicon Valley Bank, which sent shockwaves through the global financial system in March 2023. The SVB collapse exposed significant blind spots in the Fed’s supervisory approach, specifically regarding how interest rate risk and concentration risk are monitored during periods of aggressive monetary policy tightening.
Reflecting on the timeline of the SVB crisis, Bowman noted that had the Fed’s proposed analytical rigor been in place, the institution’s vulnerabilities would have been glaringly obvious much earlier. "A plausible recession scenario, with rising interest rates and investment securities measured at fair value, would have shown the firm’s capital falling below minimum required levels as early as the fourth quarter of 2021," she stated.
The independent review commissioned by the Fed, which Bowman discussed at length, paints a picture of a supervisory body hampered by its own internal culture. The review concluded that supervisory staff were aware of the risks surrounding SVB’s portfolio—specifically its heavy concentration in long-duration securities—as early as March 2022. However, this knowledge did not translate into corrective action.
Key findings from the independent review include:
- Cultural Risk Aversion: A pervasive belief among staff that failing to act was safer than taking an action that could later be deemed incorrect or overly burdensome.
- Ambiguity in Command: A lack of clear institutional authority regarding who possessed the mandate to trigger mandatory corrective actions, leading to paralysis during critical decision-making windows.
- Fragmented Oversight: A failure to integrate disparate data points regarding SVB’s liquidity position and its interest rate risk exposure into a unified, actionable supervisory strategy.
Implications for Future Supervision
Bowman’s speech signals a shift in the Fed’s philosophy toward "two-way" communication. She argues that scenario analysis should not merely be a compliance exercise for banks to report to the Fed; it should be a dialogue that helps supervisors identify risks before they manifest into liquidity crises.
"The Fed’s stress tests should do more for our supervisors than calculate a single capital requirement," Bowman noted. "Fed stress tests should also identify a firm’s vulnerability to various material financial and nonfinancial risks before those risks emerge."
This transition implies a more intrusive, forward-looking supervisory approach. Rather than relying on static formulas, the Fed is expected to utilize the information gathered from these enhanced tests to inform targeted supervisory attention across the portfolios of the nation’s largest banks.
The broader implications of these changes are substantial. For the banking sector, the "coming weeks" of finalization will determine the cost of capital for years to come. For the Federal Reserve, the successful implementation of these reforms is a matter of restoring public confidence in its regulatory mandate. As Bowman emphasized, the SVB collapse was a systemic failure that transcended the bank itself; it was a failure of the supervisory apparatus to adapt to a high-interest-rate environment.
Contextualizing the Regulatory Environment
To understand the weight of Bowman’s comments, one must look at the macro-financial landscape. The era of near-zero interest rates, which lasted for over a decade, masked many of the risks that became lethal for SVB once the Federal Reserve began its rapid cycle of rate hikes in 2022. Banks that had locked in long-term assets at low yields found themselves holding "underwater" portfolios as the value of those assets plummeted in the face of higher market rates.
The upcoming changes to the stress test framework represent the Fed’s attempt to institutionalize a "high-for-longer" risk awareness. By forcing banks to simulate scenarios where rates remain elevated and market liquidity dries up, the Fed is attempting to ensure that no bank is caught as unprepared as SVB was.
Furthermore, the legal scrutiny from groups like Better Markets highlights the delicate balance the Fed must strike. Regulators are under pressure from both sides: one, to ensure the safety and soundness of the banking system through robust capital requirements, and two, to ensure that those requirements do not stifle economic growth or create an environment where only the largest, most entrenched banks can survive.
As the Federal Reserve moves to finalize these rules, the industry will be watching closely to see how much of the "two-way" communication Bowman promised actually translates into regulatory relief versus increased administrative burden. One thing is certain: the era of the "one-size-fits-all" stress test is coming to an end, replaced by a mandate that prioritizes diagnostic foresight over procedural compliance. For Bowman and the Board of Governors, the goal is clear: ensuring that the next time a regional bank faces a liquidity crisis, the supervisory authorities are not just watching, but acting.