
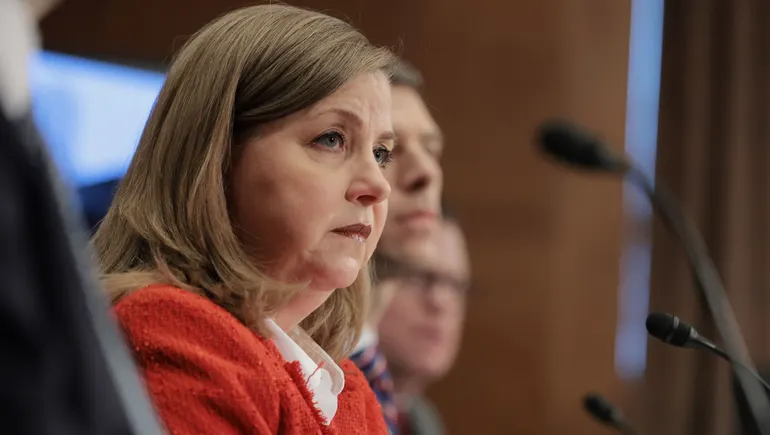
Speaking before an influential gathering of financial leaders and policymakers in London on Friday, Federal Reserve Vice Chair for Supervision Michelle Bowman delivered a comprehensive address that bridged the central bank’s ongoing regulatory evolution with the stark lessons of past financial crises. Her remarks offered a rare, dual-focus perspective, simultaneously unveiling prospective overhauls to the nation’s bank stress-testing frameworks and dissecting the institutional missteps that precipitated the spectacular collapse of Silicon Valley Bank (SVB) in the spring of 2023.
Against a backdrop of heightened legal scrutiny and a rapidly shifting macroeconomic environment, Bowman’s address sought to reassure international markets while acknowledging the urgent need for structural introspection within America’s central banking system. By connecting modernized regulatory mechanisms directly to historical supervisory failures, the Vice Chair signaled a pivot toward a more predictable, transparent, and responsive supervisory regime.
The London luncheon served as a critical platform for detailing the Federal Reserve’s upcoming policy trajectory. As financial institutions grapple with persistent interest rate volatility, liquidity pressures, and evolving compliance mandates, Bowman’s disclosures provide crucial visibility into how the world’s most powerful central bank intends to police systemic risk in the years ahead.
A Crucial Timeline for Regulatory Finalization
The immediate horizon for American banking regulation is exceptionally crowded. According to Bowman, the Federal Reserve is poised to issue final revisions to its core stress-testing framework in the coming weeks. These modifications represent the culmination of years of iterative debate regarding how the central bank measures capital adequacy and institutional resilience under adverse economic conditions.
Concurrently, Bowman indicated that the central bank expects to finalize pending alterations to risk-based capital requirements and the specific surcharge applied to global systemically important banks (G-SIBs). These capital rule changes, which were initially proposed in March, are designed to ensure that the largest financial institutions maintain adequate loss-absorbing buffers to withstand severe macroeconomic shocks without requiring taxpayer-funded interventions.
However, this regulatory ambition has not proceeded without friction. The capital-requirement overhaul has become a battleground for legal and political disputes. Just last week, a prominent advocacy group filed a lawsuit targeting both the Federal Reserve and individual officials, including Bowman herself. The legal challenge alleges that the rulemaking process surrounding the capital requirement adjustments was compromised by improper procedural steps and closed-door meetings with chief executive officers. Despite these legal headwinds, the leadership of the Fed appears determined to press forward with its policy agenda, signaling that the structural modernization of banking supervision will remain a top institutional priority.
Rethinking the Mechanics of Stress Testing
A central pillar of Bowman’s address focused on refining the operational mechanics of the Fed’s annual stress tests. For years, major banking institutions have criticized the current testing apparatus for its lack of transparency, often describing the scenarios and scoring methodologies as a "black box" that produces unpredictable capital requirements. Bowman acknowledged these concerns directly, vowing that the upcoming reforms will finally close the book on an opaque and unnecessarily unpredictable framework.
To achieve this, Bowman highlighted two significant public comments submitted during the rule-making process that the Fed is actively considering for incorporation:
- Balance Sheet Freezing Dates: One proposal suggests establishing a fixed, standardized date on which participating banks must freeze their balance sheets immediately prior to the release of the Fed’s annual stress-test scenarios. Under this proposal, the balance sheets would be unfrozen shortly afterward, providing a more consistent and distortion-free baseline against which supervisory scenarios can be modeled.
- Dual Global Market Shock Scenarios: Another recommendation advises the creation of two distinct global market shock scenarios within the test architecture. The higher projected loss resulting from these two scenarios would then be utilized to calculate the bank’s stress capital buffer, thereby ensuring a more conservative and robust defensive posture against sudden international liquidity freezes or asset price collapses.
Furthermore, Bowman announced that the Fed is seeking public commentary on an additional methodological revision slated for the 2027 stress testing cycle. This specific change involves a redesigned model to evaluate noninterest income—encompassing the fee-based and trading revenues that large financial institutions generate from wealth management, investment banking, and market-making operations. As diversified revenue streams play an increasingly vital role in bank balance sheets, ensuring accurate risk assessment in these sectors is deemed paramount.
Beyond technical adjustments, Bowman made a passionate case for transforming the stress-testing paradigm from a rigid compliance exercise into a collaborative, communicative dialogue.
"Scenario analysis is powerful on its own," Bowman remarked during the luncheon. "It becomes even more powerful when it is not a one-way exercise."
She advocated for a framework where large banks, which already design and assess their own predicted performance under severe economic stress, share deeper insights with regulators. The ultimate objective, according to Bowman, is to ensure that stress tests do much more than merely calculate a single statutory capital requirement. Instead, the tests must actively diagnose a firm’s latent vulnerabilities to both financial and nonfinancial risks long before those risks materialize into systemic threats, thereby allowing supervisors to deploy resources more effectively across large bank portfolios.
Revisiting the Silicon Valley Bank Collapse
To illustrate the practical necessity of this enriched supervisory approach, Bowman turned her analytical lens toward the most infamous banking failure of the decade: the March 2023 collapse of Silicon Valley Bank. The failure of the Santa Clara-based institution, driven by acute interest rate risk and an unhedged portfolio of held-to-maturity securities, sent shockwaves through the global financial system and triggered emergency federal interventions to stem contagion across regional banks.
In a companion assessment released concurrently with her stress-test remarks, Bowman detailed the findings of a comprehensive independent review into the SVB debacle. The revelations paint a troubling picture of institutional inertia and regulatory oversight failure.
According to the review, the Federal Reserve’s supervisory staff knew, or definitively should have known, of SVB’s severe vulnerabilities as early as March 2022—a full year before the institution imploded. Despite possessing this critical data, supervisory staff failed to take prompt, decisive, and mandatory action to compel SVB management to mitigate its extreme interest rate risk exposure and deposit concentration.
Bowman pointed to deeper cultural pathologies within the central bank as primary drivers of this inaction. The independent review identified a long-standing, pervasive culture of risk aversion among Fed staff, where personnel frequently operated under the implicit assumption that maintaining the status quo and taking no action was safer than risking a controversial or potentially incorrect intervention. Additionally, the review highlighted paralyzing ambiguity regarding chain of command, noting that supervisory staff were frequently unsure who possessed the ultimate authority to make the final call on enforcing corrective actions.
Emphasizing that the tragedy of SVB was not attributable to a single bad actor or isolated entity, Bowman stressed the broader reputational damage inflicted upon the regulatory apparatus.
"It fundamentally shook public confidence in the effectiveness of bank supervision," Bowman stated. "That loss of confidence demands our response. This review is not about assigning blame. Instead, it is about learning lessons from the past to avoid repeating them in the future."
Broader Implications for the Financial Sector
The convergence of proposed stress-test reforms, capital rule finalizations, and a brutally honest post-mortem on supervisory failures signals a transitional era for American banking oversight. As the Federal Reserve attempts to rebuild credibility in the wake of the 2023 regional banking crisis, the regulatory community finds itself walking a delicate tightrope.
On one hand, banking industry trade groups and institutional executives have consistently warned that excessively stringent capital requirements and rigid stress-testing models could restrict credit creation, diminish market liquidity, and place American lenders at a competitive disadvantage globally. The ongoing litigation spearheaded by advocacy groups further underscores the intense polarization surrounding these rule changes, reflecting fears that regulatory overreach could penalize sound financial management.
On the other hand, policymakers like Bowman are acutely aware that under-regulation and supervisory timidity carry catastrophic systemic costs. Had the Fed’s proposed analytical enhancements been operational during the run-up to the SVB collapse, the trajectory of the crisis might have been entirely different. Bowman noted that a plausible recession scenario—incorporating rising interest rates and investment securities measured strictly at fair value—would have revealed SVB’s capital reserves falling below mandatory minimum required levels as early as the fourth quarter of 2021.
By integrating these retrospective insights into forward-looking regulatory reforms, the Federal Reserve hopes to institutionalize a culture of proactive vigilance. The transition toward dynamic, multi-scenario stress testing, coupled with a concerted effort to dismantle bureaucratic paralysis within supervisory ranks, represents an ambitious attempt to future-proof the banking system.
As the central bank prepares to finalize its rules in the coming weeks, financial markets, compliance officers, and legal teams will be watching closely. The success or failure of these reforms will ultimately determine whether the Federal Reserve can successfully reconcile the competing demands of robust financial stability and efficient, transparent capital allocation in an increasingly volatile global economy.
