The financial services landscape has long struggled to connect with female consumers, frequently relying on clinical, technical specifications or historically patriarchal messaging that alienates rather than empowers. However, new consumer insights suggest a profound paradigm shift in how women conceptualise and communicate their financial trajectories. A recent interactive poll conducted by Open Banking-powered personal finance platform PocketSmith has revealed a resounding consumer preference for messaging that embraces themes of personal reinvention, intentional growth, and life transitions over rigid, traditional financial terminology.
The poll, which surveyed 270 women ranging in age from their early twenties to their mid-sixties, was designed and deployed by PocketSmith’s Chief Marketing Officer, Dora Yip, and her executive marketing team. Unveiled during a high-profile women’s wealth symposium held in Sydney earlier this month, the findings challenge long-held industry assumptions that financial progress must strictly adhere to a linear, predictable timeline tied to specific age brackets or traditional milestones. Instead, the data paints a vibrant portrait of financial journeys defined by fluidity, personal evolution, and deliberate chapters of change.
Deconstructing the Wealth Journey: A Literary Metaphor
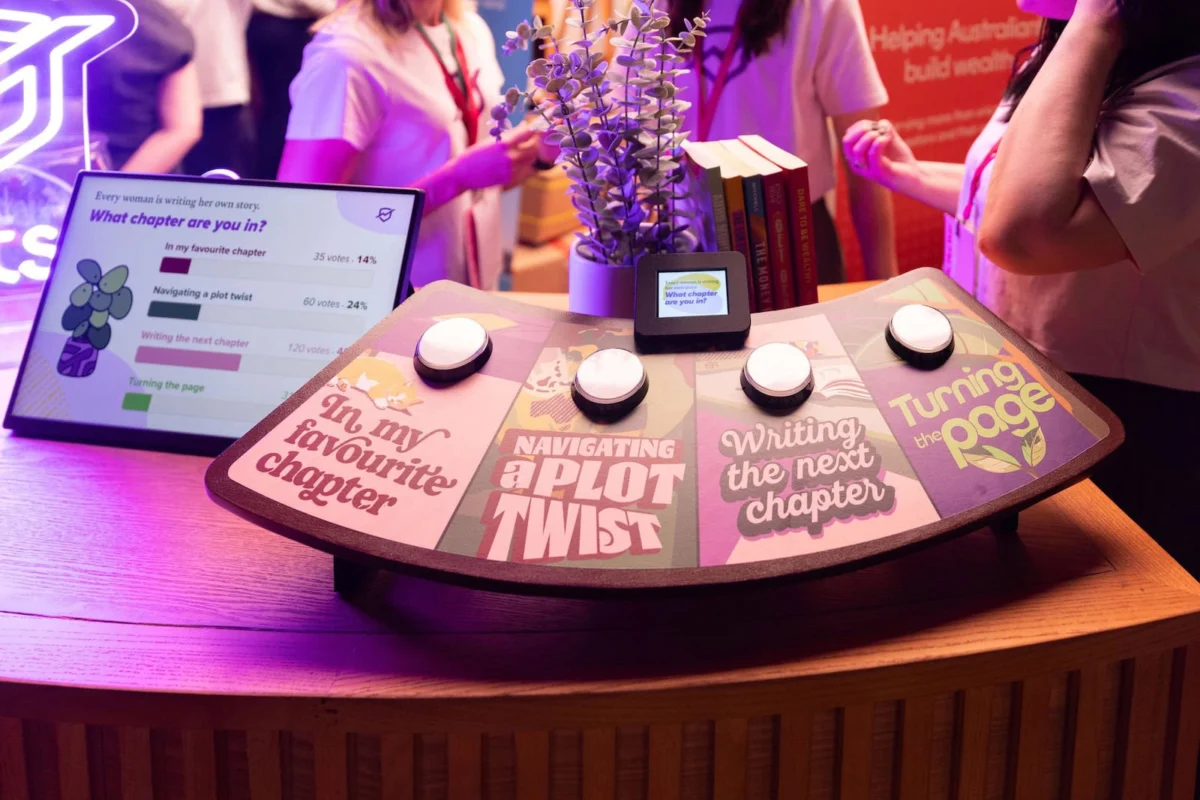
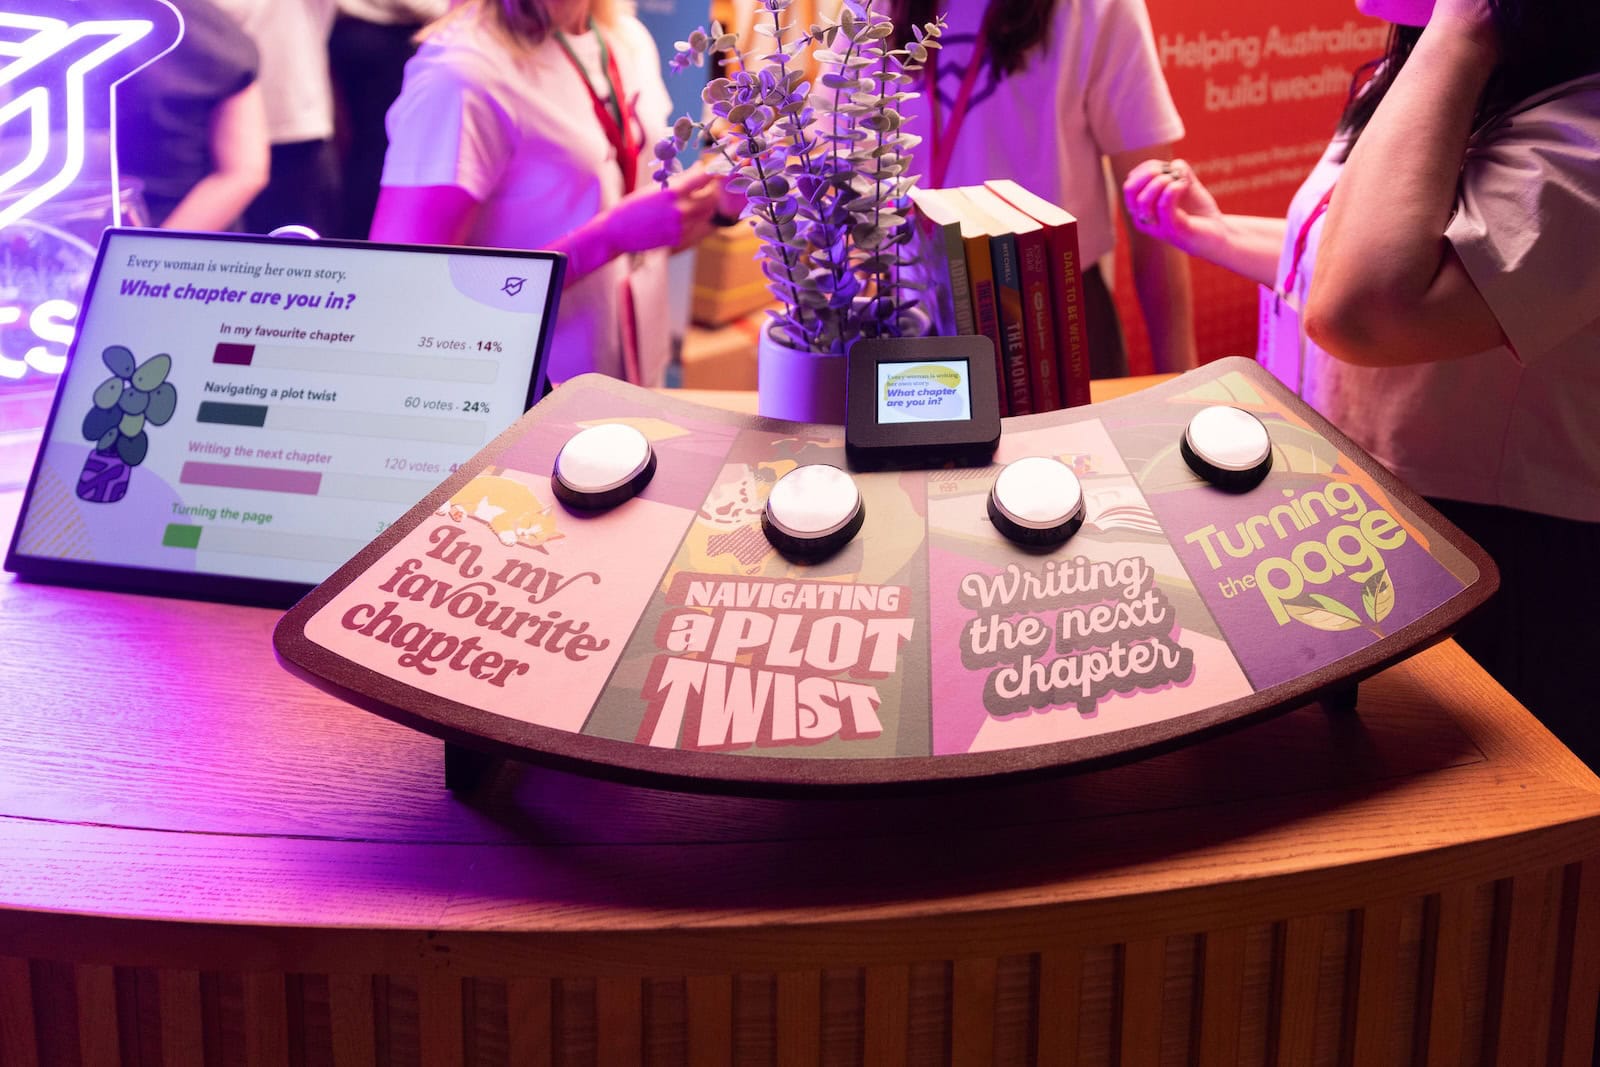
During the Sydney wealth event, attendees were invited to participate in a conceptual exercise designed to locate their current position within their individual wealth creation stories. Utilising the overarching metaphor of writing a book, participants were asked to select from four distinct narrative options that best reflected their psychological and financial state of being.
The results offered a compelling look into the mindset of modern female investors and savers. Fully half of the respondents—50%—chose the option of writing the next chapter, indicating an active, forward-looking approach to managing their money and future assets. Meanwhile, 23% of the cohort identified as navigating a plot twist, a category predominantly populated by individuals dealing with unexpected life disruptions, most notably relationship breakdowns and divorce. Furthermore, 14% of respondents reported being in their favourite chapter, reflecting a sense of stability, satisfaction, and peak achievement. Finally, 13% described their current phase as turning the page, symbolising a clean break from past financial habits or constraints to embrace a fresh start.
According to Yip, the overwhelming popularity of the "writing the next chapter" descriptor underscores a broader industry failure in communication. The data highlights a critical disconnect between the language typically deployed by financial institutions and the emotional reality experienced by consumers navigating their financial lives.
"Our poll shows women prefer a positive, intentional approach to their finances, with ‘writing the next chapter’ emerging as the most popular description of their current journey," Yip stated. "What stands out to us in the PocketSmith marketing team is that you have to give women language they can relate to. In Open Banking, the language is often focused on technical features, whereas in traditional financial marketing it can be transactional, even patriarchal. Our poll shows women are especially drawn to messaging around reinvention and taking control."
Real-World Manifestations of Financial Reinvention
To fully understand what "writing the next chapter" entails in practice, the survey examined the tangible life events and financial decisions prompting women to select this narrative. The responses revealed a diverse cross-section of modern life choices that defy conventional, linear financial planning models.
For younger demographics within the cohort—such as those in their twenties and thirties—reinvention frequently manifested as securing a first residential property with the strategic assistance of mortgage financing, or making deliberate lifestyle pivots, such as exiting full-time corporate employment to embrace the flexibility of becoming a digital nomad. Conversely, for older participants in their fifties and sixties, the next chapter often involved strategic downsizing—transitioning from a traditional, empty-nest family home into a high-end luxury apartment, thereby reallocating capital and simplifying lifestyle overheads.
These diverse milestones illustrate that financial planning tools must be flexible enough to accommodate non-traditional life paths. Open Banking infrastructure, which allows secure, real-time sharing of financial data between institutions, plays an instrumental role in facilitating this adaptability. By granting users granular visibility over their financial ecosystems, platforms like PocketSmith enable individuals to run complex financial scenarios, forecast future outcomes, and execute major life transitions with heightened confidence.
"Open Banking and fintech tools can support women to make informed decisions and plan their next chapter with greater confidence," Yip explained. "Having visibility over your money, and the ability to explore different financial scenarios, can help to shape those moments of reinvention while retaining control."
Addressing the Plot Twist: Financial Resilience After Relationship Breakdown
While half of the survey respondents focused on proactive wealth expansion, a significant portion—nearly a quarter of the group—reported navigating a plot twist. Qualitative follow-up revealed that the vast majority of these respondents were managing the financial fallout of a recent relationship breakdown or marital dissolution.
The intersection of gender, financial literacy, and relationship dissolution is a heavily researched area within socio-economic studies. Academic literature consistently demonstrates that women often experience a disproportionate decline in standard of living following a divorce, particularly if household financial management was previously delegated entirely to a partner. However, acquiring robust financial literacy and technological tools to manage money independently serves as a powerful buffer against long-term financial insecurity.
Yip emphasized the psychological and practical importance of digital financial tools during such periods of acute vulnerability. Drawing on broader academic findings, she noted that women equipped with higher financial literacy and direct control over their assets recover significantly faster from major life shocks like divorce.
"We know from academic research that women with higher financial literacy are better placed to recover from divorce," Yip said. "For women who previously relied on a partner to make financial decisions, there is something incredibly empowering about being in control."
By utilizing applications that aggregate accounts, monitor spending patterns, and provide automated forecasting, newly single individuals can quickly establish a baseline of financial independence. This digital empowerment reduces the intimidation factor often associated with solo financial administration and replaces anxiety with actionable data.
The Broader Implications for Fintech and Open Banking Marketing
The findings from PocketSmith’s Sydney poll arrive at a critical juncture for the global financial technology sector. As Open Banking matures from a regulatory mandate into a consumer-facing reality, fintech companies face mounting pressure to demonstrate tangible value to everyday users. For years, the sector’s marketing playbook has relied heavily on product-centric feature dumping—highlighting Application Programming Interface (API) speeds, encryption protocols, and automated transaction categorisation.
However, consumer research increasingly shows that technical specifications alone do not drive sustained engagement or brand loyalty, particularly among demographic segments that have historically felt underserved or overlooked by traditional banking institutions. Financial wellness is fundamentally emotional, tied closely to concepts of security, autonomy, and life goals. By reframing product utility through relatable, human-centric narratives, fintech providers can bridge the empathy gap that has long characterized the financial sector.
Industry analysts suggest that PocketSmith’s approach could serve as a benchmark for other financial service providers seeking to refine their customer acquisition and retention strategies. Tailoring user onboarding, educational content, and in-app messaging to reflect emotional inflection points—such as career transitions, property acquisitions, or post-divorce financial re-entry—can dramatically improve user adoption rates and long-term financial outcomes.
PocketSmith: Scaling Global Reach Through User-Centric Design
The release of these consumer insights coincides with a period of significant corporate momentum for PocketSmith. Earlier this year, the company achieved major industry recognition when it was awarded "Best App" at the prestigious Open Banking Expo Awards 2026, validating its technical excellence and user-first design philosophy.
Headquartered in New Zealand, PocketSmith operates as a bootstrapped, profitable enterprise with an impressive 18-year operational history. Despite the capital-intensive nature of the modern fintech sector, the company has scaled sustainably, expanding its footprint to serve approximately 396,000 customers across 190 countries. This global reach is facilitated by the platform’s capacity to seamlessly sync bank feeds from more than 14,000 financial institutions worldwide.
PocketSmith’s core value proposition revolves around its comprehensive suite of money management tools, summarized by its central brand promise: providing all the features necessary for individuals to comprehensively understand and master their finances. Key functionalities include highly customizable transaction categorisation, sophisticated "what-if" scenario analysis, and long-term forecasting capabilities that allow users to map out their financial futures decades in advance.
As the fintech ecosystem continues to evolve, companies that successfully marry robust Open Banking technology with empathetic, narrative-driven marketing will likely capture the loyalty of an increasingly discerning consumer base. For PocketSmith, the Sydney poll has provided empirical validation that understanding the human story behind the numbers is just as important as the algorithms processing them.