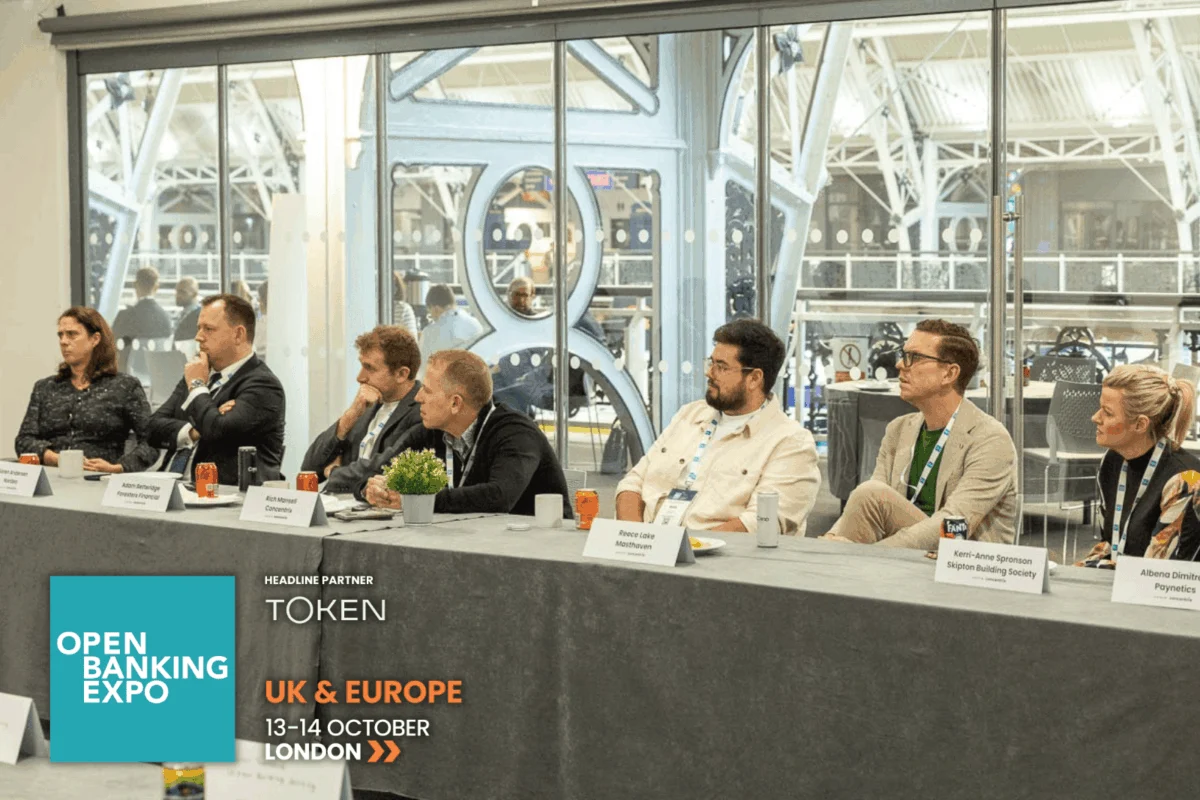
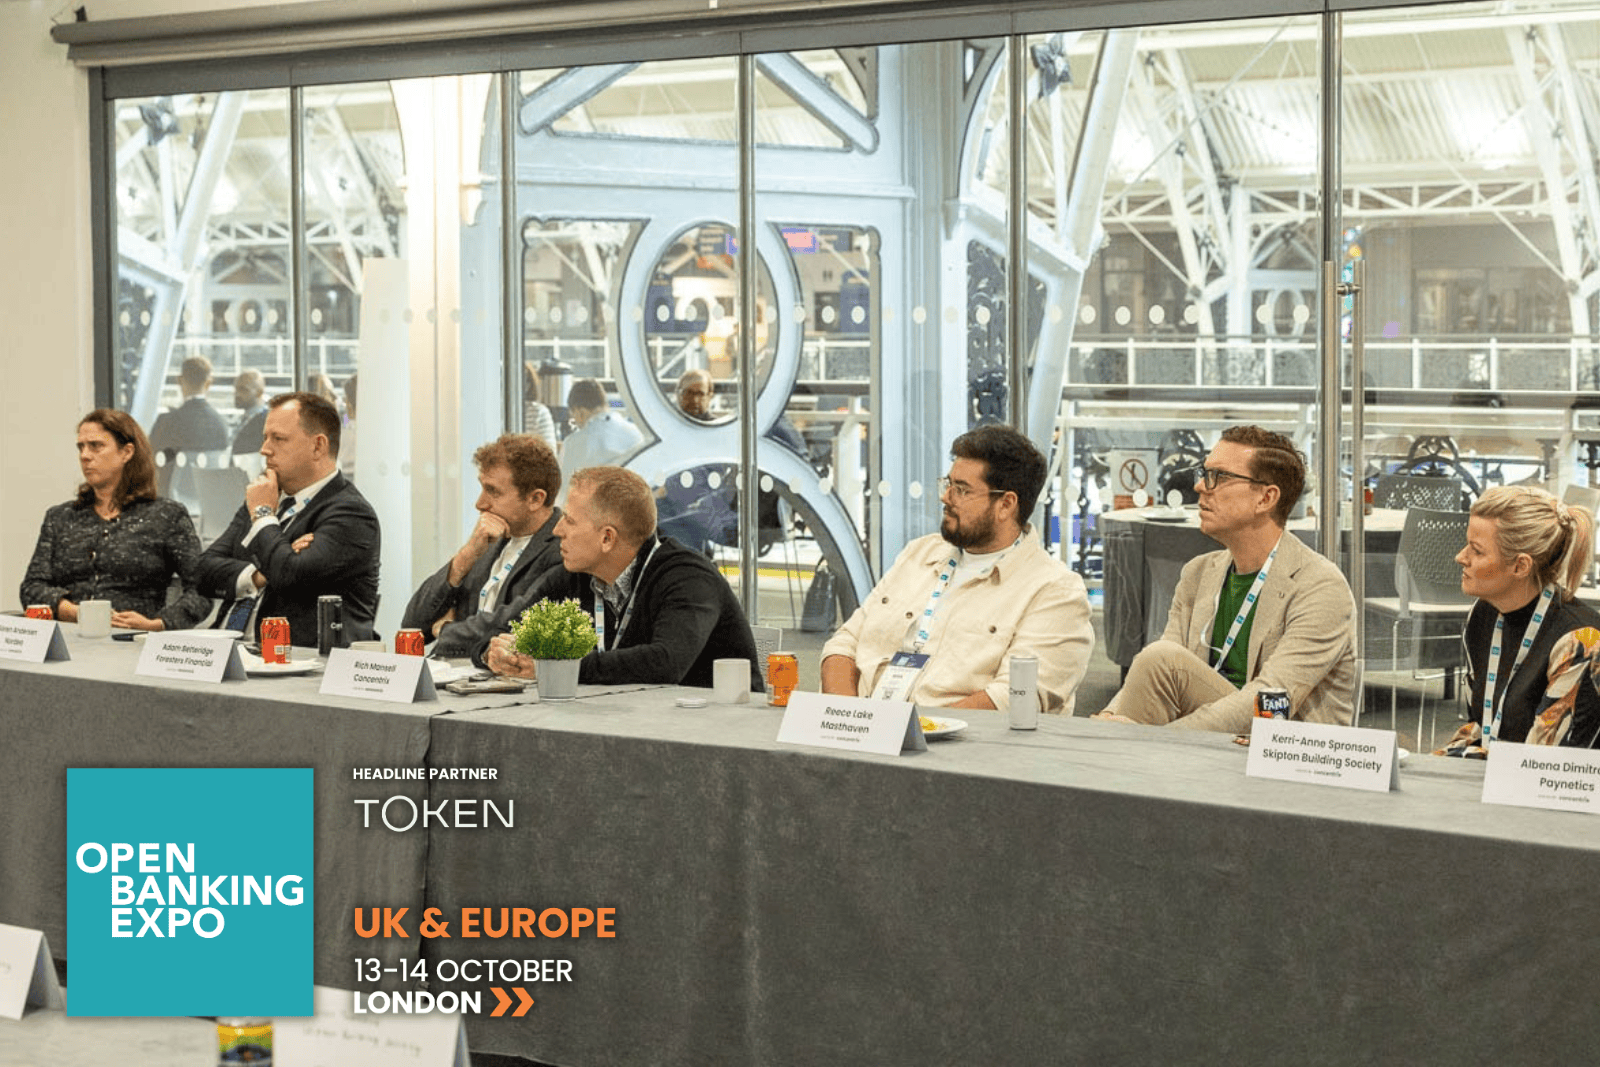
The financial services industry stands at a critical juncture in the evolution of open banking and smart data, forcing institutions to move past the initial hurdle of infrastructure building and confront a more demanding mandate: translating customer data access into tangible, measurable, and consumer-centric outcomes. This core strategic dilemma served as the focal point for an exclusive, closed-door roundtable discussion hosted by global business services and technology leader Concentrix at the Open Banking Expo UK & Europe 2026.
Conducted under the Chatham House Rule, the high-level symposium gathered senior decision-makers from across the spectrum of European finance. Attendees included executives from tier-one commercial banks, regional building societies, specialist lenders, consumer finance providers, emerging payment processors, and financial technology companies. Representing diverse operational backgrounds—ranging from digital transformation and data intelligence to customer proposition design—these leaders convened to address one of the sector’s most persistent and complex operational bottlenecks: how to bridge the gap between technical feasibility and scalable commercial value.
The dialogue centered on the transition from a proof of concept (PoC) model to a proof of value (PoV) framework. While the early years of open banking were heavily defined by regulatory compliance, API standardisation, and consent management, the modern financial landscape demands that massive inflows of consumer data be actively converted into simpler, more intuitive customer experiences and stronger operational efficiencies.
Background and Evolution: Moving Beyond Regulatory Compliance
To understand the urgency of the discussions at the Open Banking Expo 2026, one must examine the developmental trajectory of open finance over the past decade. Initiated largely by regulatory mandates such as Europe’s Revised Payment Services Directive (PSD2) and the United Kingdom’s Open Banking implementation remedies, the primary focus of the ecosystem was structural. Financial institutions were legally and technologically compelled to build secure conduits for data sharing, establish robust security protocols, and create standardised application programming interfaces (APIs).
By the mid-2020s, that foundational infrastructure had matured significantly. Millions of consumers and businesses were routinely sharing account data to secure loans, manage personal budgets, and execute rapid digital payments. However, as the volume of available data expanded exponentially—and as regulatory bodies began laying the groundwork for broader smart data legislation encompassing mortgages, savings, insurance, and pensions—a distinct friction point emerged. Access to data, while necessary, was proving insufficient on its own to guarantee commercial success or meaningful customer satisfaction.
Industry analysts note that financial institutions historically built products around internal legacy architectures and the datasets they could easily harvest. The roundtable discussion underscored a fundamental paradigm shift: modern financial service providers must invert this approach, designing solutions backward from the actual, lived financial problems their customers face daily.
Closing the Gap Between Insight and Action
A dominant theme throughout the closed-door session was the persistent disconnect between possessing sophisticated analytical datasets and executing timely, relevant operational responses. Modern banks and fintech firms possess immense computing power and advanced data lakes, yet translating raw streams of transactional data into proactive customer support remains an intricate challenge.
For instance, identifying through open banking analytics that a customer is drifting toward financial distress or overdraft territory holds little intrinsic value unless that insight triggers an immediate, empathetic, and compliant institutional response. This might manifest as proactive budgeting advice, an early restructuring offer, or a streamlined hardship application process before the consumer misses a payment. Similarly, while richer financial histories allow lenders to make more accurate risk assessments, the true test of this capability is whether it demonstrably reduces lending decision times, eliminates unfair bias, lowers borrowing costs, or broadens financial inclusion for underserved demographics.
The consensus among the assembled leaders was clear: the underlying complexity of data integration, machine learning scoring models, and multi-system workflows must remain entirely invisible to the end user. Introducing friction through clunky interfaces or delayed decision-making risks alienating consumers who increasingly expect instantaneous, Amazon-like digital experiences from their financial partners.
The Challenge of Scaling: Proof of Concept Versus Proof of Value
A significant portion of the roundtable debate was dedicated to the stark realities of scaling digital innovations. For years, financial institutions have engaged in continuous cycles of experimentation, launching isolated proofs of concept to test emerging artificial intelligence models or novel data-sharing use cases.
While these proofs of concept successfully demonstrate technical viability in controlled sandbox environments, they frequently fail to transition into enterprise-wide deployments. Scaling requires institutions to navigate heavy regulatory burdens, rigorous internal governance frameworks, fragmented legacy IT stacks, and stringent risk management protocols. Furthermore, scaling demands a verifiable return on investment (ROI).
Industry veterans at the event emphasized that success metrics must fundamentally evolve. Organisations can no longer measure project success merely by tracking the sheer volume of API calls, the number of active data connections, or the mathematical complexity of an artificial intelligence algorithm. Instead, executive boards are demanding proof of value metrics: measurable reductions in customer effort, shorter dispute or loan resolution times, lower operational costs, and tangible enhancements in consumer financial wellbeing—particularly for vulnerable populations.
Adam Cox on the Maturation of the Market
Reflecting on the themes of the expo and the strategic trajectory of the sector, Adam Cox, co-founder and managing director of Open Banking Expo, highlighted the necessity of shifting focus toward tangible outcomes.
"Open Banking has spent years proving what’s technically possible. The next challenge is demonstrating what that actually means for customers and businesses," Cox stated.
"What’s particularly encouraging is the breadth of the financial services industry now engaging in these conversations. We’re moving beyond discussions about access to data and towards how that data can improve decisions, simplify experiences and deliver genuine commercial value," he continued. "That’s where the next phase of growth will come from, and why bringing different parts of the industry together to tackle these challenges is so important."
Delegated Banking and the Automation Frontier
Looking toward the immediate horizon, the roundtable participants explored the emerging concept of "delegated banking." This paradigm envisages a financial ecosystem where permissioned customer data, advanced predictive intelligence, and secure automation operate in concert to preemptively simplify everyday financial decisions and execute routine tasks on the consumer’s behalf.
Rather than forcing retail and commercial customers to constantly monitor complex financial metrics, interpret shifting interest rates, and manually navigate multi-step administrative processes, delegated banking systems leverage automation to anticipate needs, surface optimal choices, and execute pre-approved actions. Practical use cases discussed included automated micro-savings transfers, dynamic debt consolidation, predictive cash-flow management, and proactive switching of underperforming utility or financial products.
However, the introduction of widespread automation inevitably brings complex questions regarding trust, transparency, and accountability to the forefront. Consumers must retain absolute clarity and control over how their data is deployed, what parameters govern automated actions, and how algorithms arrive at specific financial recommendations.
Crucially, the roundtable participants agreed that technology cannot entirely replace human empathy and discretion. In scenarios involving acute financial distress, complex debt management, or vulnerable life events, the presence of skilled human advisors remains indispensable. The ultimate commercial opportunity for financial institutions lies not in completely automating human interaction out of the equation, but in establishing a harmonious equilibrium between advanced machine capability and empathetic human expertise.
Rich Mansell on Balancing AI, Governance, and Trust
As artificial intelligence becomes deeply embedded across front-end customer service channels and back-end risk assessment models, the imperatives of governance, explainability, and regulatory compliance have intensified. Financial regulators across the UK and Europe maintain a zero-tolerance approach toward opaque algorithmic decision-making, requiring institutions to maintain absolute auditability for every automated action.
Rich Mansell, senior director and sector lead for banking and financial services at Concentrix, underscored that trust must serve as the bedrock of any smart data proposition.
"The real opportunity in Open Banking is not just access to data, but turning that data into action that improves customer outcomes," Mansell observed.
"Organisations succeeding at scale are combining data, AI and operational expertise to simplify journeys, reduce friction and deliver measurable value," Mansell added. "As AI-driven services grow, strong governance, explainability and human oversight remain essential to building trust and accountability."
If smart data and open banking frameworks are to achieve mass consumer adoption, public confidence must extend beyond the mere security of data transmission. Customers must implicitly trust that the analytical insights derived from their personal histories are being used ethically to benefit their financial health rather than solely to maximize institutional revenue. Trust cannot be treated as an afterthought or a compliance checkbox; it must be deliberately woven into every phase of the customer journey, from initial consent granularity to final automated execution.
Will Thompson on Aligning Innovation with Execution
The overarching sentiment of the Concentrix-hosted roundtable was one of pragmatic optimism. The foundational plumbing of open banking is largely established, and the analytical power of artificial intelligence is virtually limitless. Yet, the definitive winners of the next decade will not be those who boast the most complex technological stacks, but those who successfully align technological innovation with genuine consumer demand and flawless operational execution.
Summarizing the strategic imperatives facing the financial services sector, Will Thompson, consulting director at Concentrix, noted: "Open Banking has reached a point where success depends less on access alone and more on the ability to turn capability into commercially viable services."
"The organisations that lead will be those that connect innovation with clear customer needs and scalable execution," Thompson concluded.
As the industry advances through 2026 and beyond, the true measure of open banking and smart data will not rest on the sheer quantity of financial information made accessible across digital pipes. Instead, success will be judged by a much higher standard: whether that information successfully empowers everyday people to make wiser financial decisions, access fairer and more appropriate products, and navigate their economic lives with enduring confidence and security.