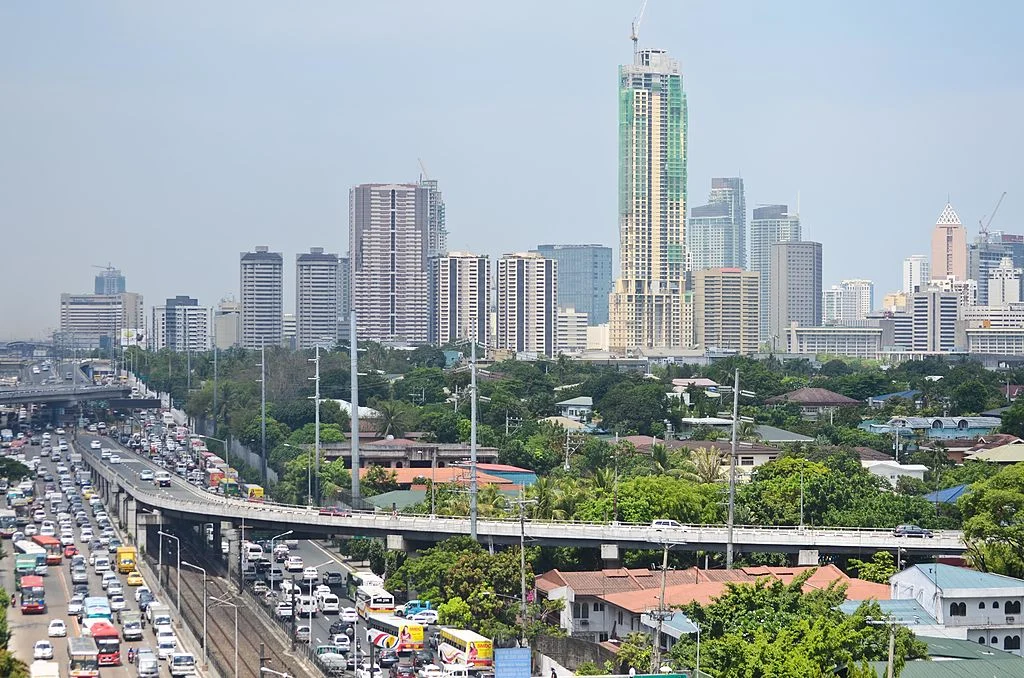
The Philippines has rapidly transformed into one of the most dynamic financial markets in Asia, characterized by a staggering migration from cash-based transactions to a digital-first economy. This evolution is underpinned by a massive expansion in retail digital payments, which grew from a negligible 1% of transaction volume in 2013 to 57.4% by 2024. However, this meteoric rise has created a complex regulatory environment, prompting the Bangko Sentral ng Pilipinas (BSP) to implement stringent new measures—most notably the Anti-Financial Account Scamming Act (AFASA)—to curb the surge in fraud that accompanies such high-speed digital adoption.
A Chronology of Financial Transformation and Oversight
The current regulatory climate is the culmination of over a decade of rapid fintech adoption. To understand the gravity of the recent shifts, one must look at the timeline of the Philippines’ journey through the global financial monitoring ecosystem:
- 2013–2020: The Philippines experiences a slow but steady digital transformation, heavily influenced by the "unbanked" population gaining access to mobile wallets.
- June 2021: The Financial Action Task Force (FATF) places the Philippines on its "grey list," citing deficiencies in anti-money laundering and counter-terrorism financing (AML/CTF) controls.
- December 2022: The Anti-Money Laundering Council (AMLC) releases a landmark Typologies Brief, highlighting the rising threat of "money mules" using electronic cash cards and ATM networks to launder illicit funds.
- July 20, 2024: The Anti-Financial Account Scamming Act (AFASA) is signed into law, signaling a legislative pivot toward criminalizing the misuse of financial accounts.
- February 2025: Following significant legislative and enforcement reforms, the FATF removes the Philippines from its grey list, recognizing the country’s strengthened commitment to financial integrity.
- June 2026: Full implementation of AFASA and associated BSP Circulars, forcing financial institutions to shift from reactive reporting to real-time transaction intervention.
- September 2026: The BSP issues Circular 1240, tightening capital requirements for rural and thrift banks that operate with the functionality of digital banks.
The Double-Edged Sword of Digital Adoption
The Philippines possesses a unique economic driver that separates it from many of its regional neighbors: the Overseas Filipino Worker (OFW) remittance corridor. In 2025, cash remittances reached a record US$35.63 billion, accounting for approximately 7.3% of the national GDP. Historically, these funds were processed over the counter. Today, the vast majority are funneled through digital channels, providing a steady, reliable stream of liquidity into the accounts of ordinary citizens.
While this flow of capital has fostered significant innovation, it has also created a "fertile" environment for financial crime. The rapid onboarding of millions of users—often prioritized for the sake of financial inclusion—created gaps in Customer Due Diligence (CDD). Data from the BSP reveals that the registered e-money account base plummeted from 324 million in 2023 to 197 million in 2024. This 39% reduction was not a sign of declining market interest, but rather a necessary "housekeeping" measure by the central bank to deactivate unverified, dormant, or fraudulent accounts.
Industry analysts note that this high volume of account turnover is the primary breeding ground for "muling." When account verification standards are compromised by the speed of acquisition, bad actors exploit the system by purchasing legitimate, verified accounts from individuals to facilitate the movement of illicit proceeds.
Legislative Response: The AFASA Framework
The introduction of the Anti-Financial Account Scamming Act represents a fundamental shift in the Philippine legal framework. AFASA does not merely target the perpetrator of a scam; it targets the financial instrument itself. Under the law, any individual involved in the lending, renting, or selling of a financial account faces between six and eight years of imprisonment.
For financial institutions, the compliance burden has increased significantly under BSP Circular 1215. Banks are now required to maintain real-time fraud monitoring systems capable of placing temporary holds on funds deemed "disputed." A transaction is now legally defined as disputed if there are reasonable grounds to suspect it is unusual for the customer, lacks clear economic purpose, originates from an illegal source, or is the result of social engineering.
This requirement essentially mandates that institutions move away from static "check-the-box" compliance and toward behavioral analysis. Because social engineering—the manipulation of individuals into divulging sensitive information—often bypasses traditional security, institutions must now analyze how an account behaves over time rather than relying solely on the data provided during the initial onboarding phase.
The Challenge for Market Entrants
The regulatory tightening is also impacting how foreign fintech groups enter the Philippine market. In previous years, firms from Singapore, Indonesia, and elsewhere utilized a strategy of acquiring small rural or thrift banks to bypass the lengthy licensing process for digital banks. These entities would then scale these rural charters into national digital platforms.
The BSP’s September 2026 mandate, Circular 1240, has effectively closed this regulatory arbitrage. Any thrift, rural, or cooperative bank operating with the scale and features of a digital bank must now meet a minimum capitalization threshold of PHP 1 billion. This rule applies retroactively to acquisitions intended to facilitate technology-driven banking models.
For international firms looking to expand into the Philippines, the message is clear: the era of "regulatory light" expansion is over. Acquirers must now conduct deep-dive audits of customer books inherited from smaller institutions, as they are now legally liable for the quality of verification performed by those previous owners.
Toward an Integrated Compliance Future
The path forward for compliance teams in the Philippines is the transition toward a consolidated financial crime risk management framework. The silos that previously separated transaction monitoring, fraud detection, and customer risk scoring are becoming obsolete under the new regulatory regime.
Effective compliance now requires a three-pillar approach:
- Risk Indicia Screening: Constant evaluation of the customer base against emerging risk markers.
- Dynamic Risk Scoring: Updating customer profiles based on actual behavioral data rather than static onboarding information.
- Real-Time Intervention: Utilizing AI-driven tools to detect and halt suspicious transactions before they clear, aligning with the "act inside the transaction" requirement of AFASA.
The implications for the broader Philippine economy are significant. While the cost of compliance has risen, the long-term benefit is a more resilient and trusted financial system. By curbing the prevalence of money mules and fraudulent accounts, the BSP aims to protect the integrity of the digital payment rails that the country’s future economic growth depends upon.
As the Philippines continues to navigate this transition, the success of the financial sector will likely be measured by its ability to balance technological speed with institutional vigilance. For global players, the Philippines remains an attractive market, but one that demands a sophisticated, technology-led approach to regulatory alignment. The transition from an era of rapid, unchecked growth to one of sustainable, secure digital finance is the defining challenge of the current decade for the Philippine banking sector.