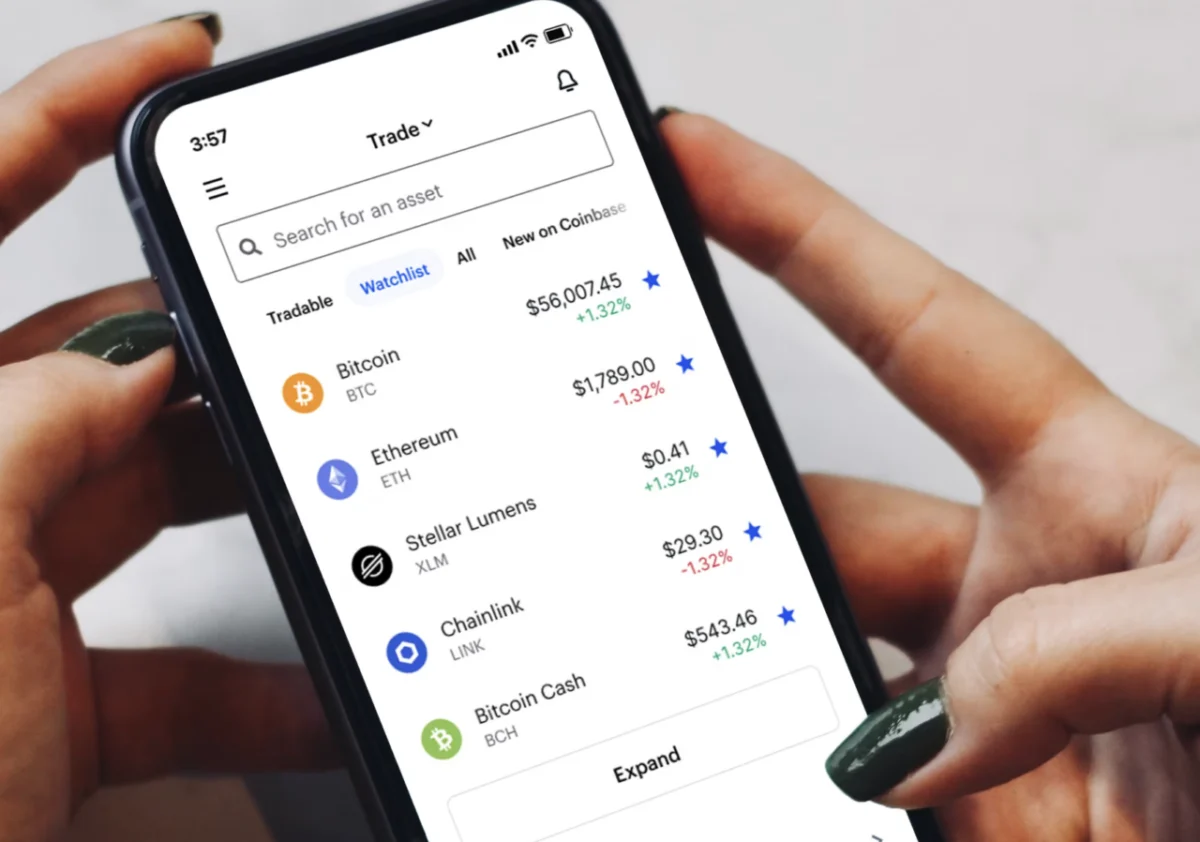
The intersection of traditional finance and the decentralized digital economy has reached a significant milestone, as major cryptocurrency exchange platform Coinbase announces a strategic partnership with digital asset banking infrastructure provider Stablecore. This collaboration aims to empower thousands of community banks, regional financial institutions, and credit unions across the United States to seamlessly integrate cryptocurrency trading, secure custody solutions, and stablecoin payment systems directly into their legacy banking platforms.
By leveraging Stablecore’s white-labeled financial infrastructure, this alliance bridges the operational gap between traditional banking frameworks and blockchain technology. The joint initiative is designed to allow more than 3,000 community financial institutions to offer comprehensive digital asset products without undergoing costly and disruptive technology overhauls. Consequently, everyday bank customers and credit union members will gain the ability to interact with the decentralized financial ecosystem natively, eliminating the historical friction of managing separate accounts across disparate third-party crypto exchanges.
Main Facts of the Collaboration
Under the terms of the agreement, Coinbase will supply its industry-leading digital asset infrastructure—encompassing liquidity, trade execution, and regulatory-compliant custody solutions—to Stablecore’s extensive network of financial partners. Stablecore, a specialized fintech founded in 2025, acts as the connective tissue, seamlessly embedding these advanced capabilities into the existing core software systems that regional banks and credit unions already utilize.
The primary objective of the rollout is customer retention and localized empowerment. Historically, consumers looking to buy, sell, or hold digital assets had to establish independent accounts with centralized exchanges or decentralized finance applications, pulling deposits away from local institutions. The new integration reverses this trend by enabling regional banks to provide these services under their own proprietary brand names. Early adopters, such as Amarillo National Bank in Texas, are already piloting the technology, proving that community-level institutions can successfully launch competitive digital asset offerings while safeguarding their core deposit and lending relationships.
Chronology and Background Context
The groundwork for this partnership reflects the rapid maturation of the digital asset industry over the past decade and a half. Since the genesis of Bitcoin in 2009, the cryptocurrency market operated largely as a parallel financial system, disconnected from the traditional banking sector. Throughout the 2010s and early 2020s, commercial banks viewed digital assets primarily through a lens of regulatory risk, compliance uncertainty, and technological incompatibility.
However, the rapid consumer adoption of cryptocurrencies and stablecoins created an urgent imperative for mainstream financial institutions to adapt. Between 2020 and 2024, regulatory clarity surrounding digital assets began to evolve, opening doors for institutional participation. Stablecore was subsequently established in 2025 in Texas specifically to address the technological isolation facing community banks and credit unions, which often lack the massive engineering budgets of Wall Street megabanks.
By 2026, the demand for stablecoin-based cross-border payments and tokenized deposits reached a tipping point. Recognizing that community lenders were at risk of losing a generation of digitally native customers to standalone fintechs, Coinbase and Stablecore accelerated negotiations. The resulting partnership marks a definitive shift: instead of bypassing traditional banks, the world of decentralized finance is actively utilizing the community banking sector as a primary distribution channel.
Supporting Data and Market Dynamics
The urgency of this partnership is underscored by compelling market data regarding consumer behavior and deposit retention. According to various industry analyses, over 20% of the U.S. adult population has interacted with digital assets at some point. More importantly, younger demographics—specifically Millennials and Generation Z—view financial services through an integrated lens, expecting their primary checking and savings accounts to accommodate both traditional fiat currency and digital tokens.
Community banks and credit unions represent the bedrock of the American financial system, holding trillions of dollars in local deposits and providing essential small-business lending. Yet, prior to infrastructure solutions like Stablecore, these institutions faced a stark competitive disadvantage against national financial technology giants and tier-one money center banks. By granting over 3,000 institutions instant access to Coinbase’s liquidity and security infrastructure, the partnership immediately neutralizes the technological moat that previously favored massive Wall Street entities and standalone crypto brokerages.
Furthermore, the integration focuses heavily on stablecoins—cryptocurrencies pegged to fiat currencies like the U.S. dollar—which have emerged as one of the fastest-growing use cases in global commerce. Stablecoins enable near-instantaneous, low-cost settlement times compared to legacy wire transfers and ACH networks. By embedding stablecoin capabilities into regional banking apps, the partnership positions community lenders at the forefront of next-generation payments technology.
Official Responses and Industry Perspectives
Leadership from both organizations emphasized the democratization of financial technology as a driving force behind the collaboration. Executives noted that community lenders should not be penalized for their localized focus or smaller operational scales.
"Community banks and credit unions shouldn’t have to choose between staying local and staying current," stated Alec Lovett, Head of Infrastructure Business at Coinbase. "Together with Stablecore, we are helping put them on the cutting edge of payments technology—cheaper, faster money movement, and the tools they need to stay strong for the communities they serve."
Lovett’s sentiments highlight Coinbase’s strategic pivot toward infrastructure-as-a-service. Rather than viewing traditional banks as ideological opponents, the exchange is positioning itself as an essential backend utility for the entire financial sector.
Echoing this perspective, Alex Treece, Co-Founder and CEO of Stablecore, stressed the importance of architectural simplicity for regional financial institutions. "Banks and credit unions should not have to move to completely new technology platforms to support digital assets for their clients," Treece explained. "We built Stablecore to bring together all of the pieces so they don’t have to."
By handling the complex regulatory, security, and integration layers behind the scenes, Stablecore ensures that regional compliance officers and IT departments can adopt digital asset products with minimal friction.
Broader Impact and Industry Implications
The Coinbase and Stablecore alliance is a prime manifestation of a broader macroeconomic trend known in financial circles as the "rebundling" of banking services. Over the past decade, the unbundling of finance saw specialized fintech startups strip away specific banking functions—such as payments, investing, lending, and crypto trading—offering them through standalone applications. While this introduced high-performing digital tools to consumers, it fragmented the customer experience and eroded the primary bank-customer relationship.
Today, the industry is experiencing a counter-movement. Consumers increasingly favor consolidated dashboards where they can view and manage their entire financial lives in one place. By embedding crypto trading, custody, and stablecoin utilities directly into community bank applications, Stablecore and Coinbase are actively reversing fragmentation.
From a strategic standpoint, Coinbase’s role in this partnership reveals a sophisticated business model evolution. As a consumer-facing exchange, Coinbase traditionally competed directly with banks for retail deposits and trading fees. However, by powering the infrastructure for thousands of community banks, Coinbase diversifies its revenue streams into B2B infrastructure. If retail customers choose to trade crypto through their local credit union rather than the Coinbase mobile app, Coinbase still monetizes the underlying transaction volume and custody services.
For community banks and credit unions, the implications are equally profound. Defending against deposit outflows has become a primary operational challenge in an era of high interest rates and aggressive fintech competition. Offering digital asset services allows these institutions to modernize their value proposition, attract younger demographics who prioritize cryptocurrency access, and reinforce their status as the central hub of their customers’ financial lives.
Fact-Based Analysis of Challenges and Future Outlook
Despite the promising alignment of technology and market demand, several challenges remain as this digital asset offering scales across the Stablecore network. Regulatory oversight surrounding digital assets in the United States continues to evolve, requiring constant vigilance from participating financial institutions. Community banks operate under strict federal and state regulatory frameworks governed by agencies such as the FDIC, the Federal Reserve, and the OCC. While Stablecore and Coinbase provide compliant frameworks, individual banks must ensure their risk management practices adequately oversee third-party digital asset operations.
Additionally, consumer education will play a critical role in the successful adoption of these tools. While digital-native generations are familiar with cryptocurrency, the average customer of a regional credit union may require guidance to understand concepts such as stablecoin transfers and digital asset custody. Successful deployment will depend heavily on the customer support and educational resources provided alongside the software integration.
Looking forward, the success of the Coinbase-Stablecore initiative could establish a new blueprint for regional banking technology. As tokenization, blockchain settlement rails, and digital currencies become increasingly central to the global financial architecture, the ability of local institutions to offer these services will determine their long-term viability. By bridging the gap between Silicon Valley crypto innovation and Main Street banking, this partnership signals that the future of digital assets is not necessarily a replacement for traditional banking, but rather an integrated feature of it.