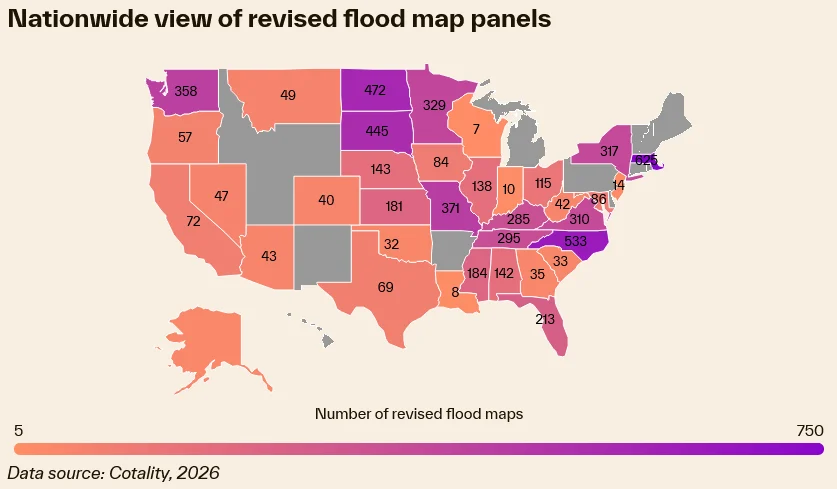
The Federal Emergency Management Agency (FEMA) has finalized updates to its flood insurance rate maps (FIRMs) across more than 100 communities in 12 states, triggering an immediate regulatory requirement for thousands of homeowners. According to a comprehensive alert published this week by business intelligence firm Cotality, property owners now situated within the newly designated Special Flood Hazard Area (SFHA) must secure mandatory flood insurance coverage within a 45-day window to maintain compliance with mortgage lending requirements. This sudden shift in geographical risk designation places a significant financial burden on families already contending with the rising costs of homeownership and housing instability.
The Geography of Risk: Impacted Regions
The reclassification of these properties is not uniform, but it is concentrated in regions that have historically been susceptible to extreme weather events. The data provided by Cotality highlights that the impact is most severe in coastal and riverine regions where topographic changes and improved hydrological modeling have necessitated a recalculation of flood risk.
Escambia County, Florida, stands as the most significantly affected jurisdiction, with 2,344 properties transitioned into the SFHA. This region, already accustomed to the destructive potential of hurricanes and tropical storms, faces a compounding crisis as homeowners adjust to the necessity of federal flood insurance coverage. Other areas seeing substantial volume include Pender County, North Carolina (678 properties), and Chattanooga, Tennessee (635 properties). The inclusion of inland areas like Ithaca, New York, and Methuen, Massachusetts, with 428 properties each, underscores the reality that flood risk is no longer confined to traditional coastal zones but is an expanding threat across the American interior.
Chronology and Regulatory Context
FEMA’s mapping process is a multi-year, rigorous technical endeavor that involves analyzing historical weather data, topography, and local development trends. However, the transition from draft map to finalized, legally binding document often occurs with little warning for the average homeowner.
The process typically begins with a discovery phase, followed by a detailed engineering analysis and the release of preliminary maps. Stakeholders and local government officials are granted an appeal period; however, public awareness during this phase is historically low. Once the final letters of map revision or updated FIRMs are issued, the 45-day countdown begins for lenders to notify borrowers. For many homeowners, the first notice of their new high-risk status arrives via a letter from their mortgage servicer, often after the policy change has already been formalized at the federal level.
Financial Vulnerability and Escrow Pressures
The timing of these updates is particularly precarious for vulnerable populations. Cotality’s research reveals a disturbing trend regarding the financial health of households currently entering the SFHA. For roughly 10% of homeowners in these affected areas, the total amount paid into escrow accounts—which covers property taxes, hazard insurance, and now, mandatory flood insurance—already exceeds the principal and interest payments on their mortgage.
This creates a "cost-of-housing" trap. When flood insurance is added to an existing escrow account, monthly payments spike, often leading to escrow shortages that must be addressed by the homeowner in a lump sum or through significantly higher monthly payments. For households utilizing FHA loans or other low-down-payment programs, this sudden increase in non-negotiable costs can be the tipping point toward financial delinquency.
The Correlation Between Premiums and Defaults
Historical data from the Gulf Coast—a region that has served as a laboratory for the intersection of climate risk and mortgage stability—illustrates the long-term dangers of these policy shifts. In states like Louisiana, Mississippi, and Texas, economic research has identified a direct correlation between major environmental events, the subsequent surge in insurance premiums, and an uptick in mortgage defaults.
When the cost of insuring a home against floods increases, the underlying asset becomes less affordable, and the homeowner’s equity is effectively eroded by the high cost of protection. If the insurance cost makes the monthly mortgage payment unsustainable, the likelihood of a homeowner falling into arrears increases, potentially leading to foreclosure. This cycle of "climate-induced delinquency" is a growing concern for financial institutions and federal housing authorities alike.
Official Responses and Industry Outlook
Howard Botts, chief scientist at Cotality, emphasized the importance of transparency in this process. "Stability is invaluable, and having the most accurate view of risk will mean millions more homeowners are prepared when the storm inevitably arrives," Botts stated in the firm’s alert. "Preparation leads to community resilience, which can lessen the burden of recovery."
However, industry experts suggest that the current communication framework is inadequate. Because notifications to homeowners are not strictly mandated in a way that ensures widespread public awareness, thousands of families are left in the dark until the financial impact hits their bank accounts. Critics argue that a more proactive approach—involving local municipalities, real estate agents, and mortgage originators—is necessary to ensure that prospective buyers and current owners understand the long-term fiscal liabilities associated with their properties.
Broader Implications for the Housing Market
The implications of these map changes extend far beyond individual household budgets. As FEMA updates its maps to reflect current climate realities, the "high-risk" designation is effectively being applied to properties that were previously considered safe. This creates a ripple effect throughout the housing market:
- Property Valuation: Homes now designated as high-risk may see a stagnation or decline in market value, as potential buyers factor in the cost of mandatory flood insurance when making offers.
- Mortgage Servicing: Lenders are required to monitor these maps continuously. Increased administrative costs associated with force-placing insurance on delinquent accounts represent a significant operational burden for mortgage servicers.
- Infrastructure Investment: Communities with large numbers of properties in the SFHA may find themselves under pressure to invest in costly flood mitigation infrastructure, such as levees or improved drainage systems, to help homeowners transition out of the high-risk designation.
Future Risk Assessment and Mitigation
As environmental conditions continue to evolve, the frequency of FEMA map updates is expected to increase. The reliance on historical data is being phased out in favor of predictive modeling that accounts for sea-level rise and the increasing intensity of precipitation events. For mortgage loan providers and institutional investors, this necessitates a shift in how they assess long-term collateral risk.
"It is essential to ensure stakeholders, like mortgage loan providers, forecast future environmental outcomes and assess long-term risk," the Cotality report concluded. "Homeowners shouldn’t be left in the dark on the true costs of homeownership."
Moving forward, the goal for policymakers and industry leaders is to balance the need for accurate risk identification with the necessity of protecting homeowners from sudden, unsustainable financial shocks. Without enhanced communication protocols and potential subsidies for vulnerable populations, the ongoing update of flood maps threatens to exacerbate the existing affordability crisis, turning the essential protection of insurance into an insurmountable hurdle for the most at-risk members of the housing market.
As the 45-day mandate takes effect for the latest cohort of affected homeowners, the focus remains on whether these individuals can secure the necessary coverage and whether their financial institutions will offer the flexibility required to navigate this sudden transition. The intersection of environmental science and financial regulation remains one of the most critical challenges facing the stability of the American housing sector in the coming decade.