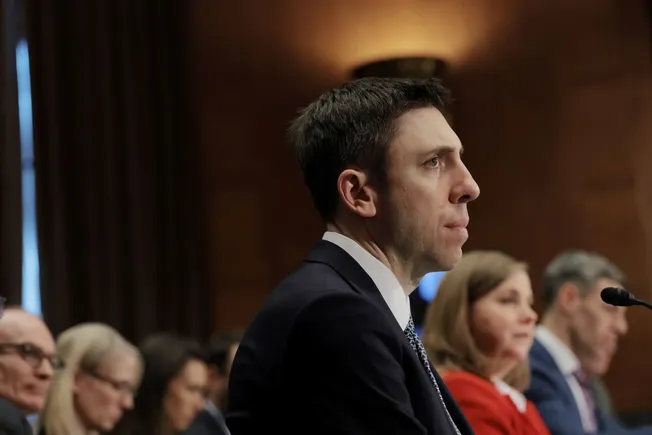
The Federal Deposit Insurance Corporation (FDIC) has unveiled a sweeping proposal designed to comprehensively reform the framework under which it assesses and processes bank merger applications. This initiative, spearheaded by FDIC Chairman Travis Hill, represents a significant pivot toward reducing bureaucratic friction in the banking sector. By aiming to improve the speed, transparency, and predictability of the regulatory approval process, the FDIC is attempting to modernize its oversight to match the realities of a rapidly evolving digital and consolidated financial landscape.
The proposed reforms, announced Thursday, come after a period of intense scrutiny regarding how federal regulators handle the increasing frequency of bank consolidations. For years, industry participants have lamented that the protracted nature of the merger review process acts as an implicit tax on growth, hindering strategic planning and creating unnecessary market uncertainty.
A Chronology of Regulatory Reform
The move to accelerate merger reviews has been a centerpiece of Chairman Travis Hill’s agenda since he assumed his current role in January 2025. Upon taking office, Hill identified the modernization of the merger application pipeline as one of his 15 core priorities for the agency. Since that time, the FDIC has been methodically working to streamline its internal operations.
The results of these preliminary efforts are already visible in the agency’s performance metrics. In 2023 and 2024, the FDIC averaged 107 days from the initial receipt of a merger application to a final agency action. Under Hill’s leadership, that timeframe has been reduced to an average of 64 days during the current calendar year. The new proposal seeks to codify these improvements while introducing structural changes to prevent future backlogs.
Core Components of the Proposal
The FDIC’s latest proposal introduces several technical but impactful adjustments to the regulatory framework. One of the most significant changes involves placing stricter constraints on the agency’s ability to remove an application from expedited processing. By limiting the arbitrary use of extended review periods, the FDIC aims to provide applicant banks with a more reliable timeline for their strategic activities.
Additionally, the proposal introduces a "proportionality" approach to filing requirements. Under this new model, the complexity and rigor of the documentation requested by the FDIC would be tailored based on the specific risk profile of the transaction and the attributes of the acquiring institution. Furthermore, the agency intends to implement a mandatory "before-and-after" analysis, which will require applicants to demonstrate how the proposed deal will specifically contribute to financial stability.
Chairman Hill underscored the necessity of these changes, arguing that the current system is detrimental to both the institutions and the broader economy. "A long process is damaging in many ways," Hill said in a statement. "It creates uncertainty for employees and customers, it constrains long-term planning and investment, it makes post-merger integration more challenging and costly, and it potentially leaves the merging entities in a vulnerable position."
Economic Rationale and Industry Sentiment
The banking industry has reacted to the news with cautious optimism. For years, lobbyists and bank executives have argued that the regulatory environment failed to account for the competitive realities of the modern era, where community banks must contend with non-bank fintech competitors and large national institutions alike.
Randy Benjenk, a partner at the law firm Covington & Burling, noted that the proposal directly addresses long-standing industry requests. "The proposal is encouraging, particularly in its effort to take a realistic look at who actually competes with banks in local markets," Benjenk said. He added that the shift toward recognizing non-bank competition is a long-overdue acknowledgment of how consumer behavior has migrated to digital platforms.
However, analysts point out that the FDIC’s reach is inherently limited by the multi-layered nature of the U.S. regulatory system. Most bank-to-bank mergers require sign-off from the Federal Reserve, which often conducts its own exhaustive review process. Unless the Federal Reserve implements parallel reforms, the time-saving benefits of the FDIC’s new rules may be muted in larger transactions.
Nevertheless, there is a clear "near-term payoff" for internal corporate reorganizations. Many banks have deferred necessary housekeeping—such as merging redundant legal entities—due to the administrative burden of the approval process. A faster FDIC turnaround could unlock a wave of efficiency-driven corporate restructuring that has been stalled for years.
Addressing the State-National Bank Parity Gap
Alongside the merger reforms, the FDIC has introduced a proposed rule aimed at ensuring parity between state-chartered and national banks. This initiative is a response to recent state-level legislation and litigation that has clouded the legal landscape regarding the applicability of state laws to out-of-state financial institutions.
The FDIC, as the primary federal regulator for state-chartered banks, seeks to prevent competitive imbalances. The proposed rule mandates that if a state’s laws are deemed inapplicable to a national bank, those same standards should not apply to an out-of-state, state-chartered bank offering services in that state, regardless of whether the bank maintains a physical retail branch there.
"Non-branch financial services have proliferated, as technological innovations dramatically altered the banking landscape," Hill stated. "Today, state-chartered banks commonly serve customers in host states without establishing branches in those states." This proposed rule serves as a recognition of this shift, ensuring that the regulatory burden is consistent regardless of the bank’s charter type or physical footprint.
Future Implications and The Path Forward
The broader goal of these reforms is to ensure the long-term viability of small and mid-sized banks. Chairman Hill is a vocal proponent of fostering a healthy, competitive environment rather than imposing blanket prohibitions on consolidation. "Placing artificial constraints on merger activity is the wrong answer to address industry consolidation," Hill said. "Instead, we should continue our efforts to reinvigorate the pipeline for new bank entrants and streamline excess regulation and supervision so that small banks can remain competitive."
The proposed rules are now entering a public comment period, which will last for 60 days following their publication in the Federal Register. During this window, the FDIC will collect feedback from stakeholders, consumer advocacy groups, and industry experts. The agency will then review these comments before finalizing the rules, a process that will likely see intense debate regarding the balance between consumer protection and institutional efficiency.
Contextual Analysis: The Regulatory Landscape
The timing of these proposals is notable. As the banking sector grapples with the transition to digital-first services, the regulatory framework has often been criticized for being "stuck in the past." By explicitly noting that current frameworks are outdated, the FDIC is signaling a shift toward a more agile, risk-based approach to supervision.
The data supports the need for such a shift. The decline in the number of small, community-based financial institutions over the last decade has sparked fears about the availability of credit in rural and underserved areas. While the FDIC’s proposals will not solve all the structural challenges facing these institutions, they represent a meaningful step toward reducing the cost of compliance, which often falls disproportionately on smaller firms.
Ultimately, the FDIC’s proposal is a balancing act. On one hand, it seeks to enable banks to scale and adapt through mergers. On the other, it must ensure that such transactions do not compromise the stability of the financial system or lead to excessive market concentration. Whether these reforms achieve the intended "speed and certainty" will largely depend on how the FDIC manages the transition and, crucially, whether other regulators follow suit.
For now, the banking industry remains on watch. The next two months of public comment will reveal the extent to which these proposals align with the broader goals of the Biden-Harris administration’s financial regulators and the competitive pressures facing the nation’s lenders. If implemented effectively, these changes could mark the beginning of a more flexible, technology-aware era for the U.S. banking regulatory regime.