The current housing market landscape is dominated by a singular narrative: mortgage rates have climbed to their highest levels in over a year, prompting a wave of hesitation among prospective homeowners. As rates for 30-year fixed-rate mortgages hover consistently above the 6.5% threshold, many potential buyers are opting to remain on the sidelines, waiting for a retreat that market analysts suggest may never materialize. This hesitation, while understandable, is frequently rooted in a skewed perception of what constitutes a “normal” interest rate environment. For a generation of homebuyers who reached adulthood during the post-2008 era of near-zero interest rates, the current climate feels like a punishing anomaly rather than a return to long-term historical averages.
A Generation Shaped by Extraordinary Policy
To understand the current anxiety, one must examine the demographic profile of today’s market participants. Recent analysis indicates that the average age of a first-time homebuyer in the United States reached approximately 32 in 2025. This cohort entered their formative adult years around 2011, a period characterized by the Federal Reserve’s aggressive efforts to stabilize the economy following the Global Financial Crisis. For these individuals, the "new normal" was an environment where interest rates were artificially suppressed to stimulate lending and investment.
This period was, by any objective historical standard, an aberration. From 1971 through the present, the average 30-year fixed-rate mortgage has fluctuated significantly, with the long-term historical average hovering near 7.68%. When viewed through this lens, the current rates, while elevated compared to the 2020-2021 period, are actually below the multi-decade average. The belief that rates will inevitably return to the 3% range ignores the structural economic conditions that made those lows possible.
Chronology of the Low-Rate Era
The path to the current rate environment is marked by two distinct global emergencies that forced the Federal Reserve to intervene with unprecedented monetary policy.
- 2008-2015: The Post-Crisis Expansion. Following the collapse of the housing bubble and the subsequent global financial instability, the Federal Reserve cut the federal funds rate from 5.25% in late 2007 to a range of 0% to 0.25% by December 2008. This policy remained in place for seven years, providing the foundation for an era of cheap credit.
- 2016-2019: The Attempted Normalization. The Federal Reserve initiated a series of gradual rate hikes, attempting to return to a more standard monetary posture. By December 2018, the target rate had peaked at 2.37%. However, global economic headwinds led to a softening of this stance by late 2019.
- 2020-2022: The Pandemic Intervention. The onset of the COVID-19 pandemic prompted a return to zero-bound interest rates. As the economy shuttered, the Fed sought to prevent a total financial collapse, driving mortgage rates to historic lows.
- 2022-Present: The Inflationary Pivot. As supply chain disruptions and fiscal stimulus fueled a surge in inflation, the Federal Reserve began a rapid series of rate hikes starting in March 2022. While the Fed has since moderated its policy, it has maintained a "higher for longer" stance to ensure that inflation returns to its 2% target.
The Federal Reserve’s Dual Mandate and Current Strategy
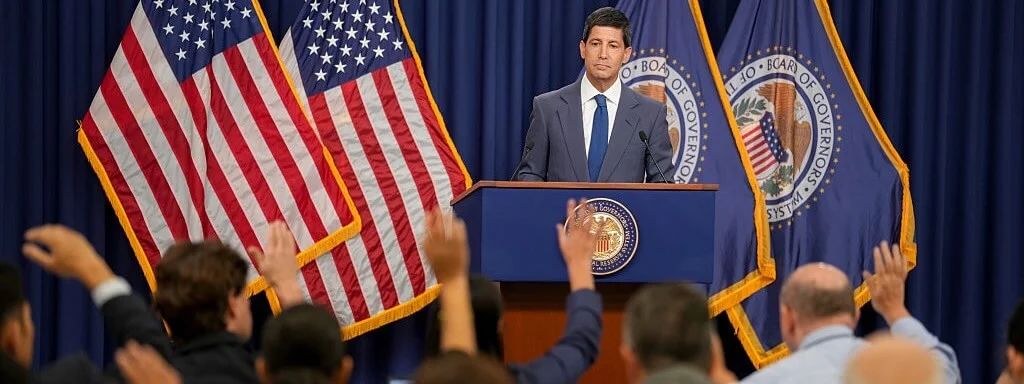
The current monetary strategy, overseen by Fed Chair Kevin Warsh, emphasizes a strict commitment to price stability. During the June 2026 policy meeting, Warsh signaled that the Federal Reserve’s primary objective remains the containment of inflation. The central bank is wary of allowing inflationary expectations to become embedded in the consumer psyche, which would necessitate even more aggressive interventions in the future.
While the Fed’s dual mandate requires it to balance inflation control with maximum employment, the labor market has proven remarkably resilient. With unemployment remaining steady and projections suggesting this trend will persist through 2028, the Fed faces less pressure to slash rates to support the labor force. Furthermore, robust GDP growth and sustained retail sales suggest that the economy remains sufficiently liquid to withstand the current interest rate environment, removing the immediate impetus for a dovish pivot.
The Hidden Costs of Waiting
Many prospective buyers operate under the assumption that if they wait for rates to fall, they will achieve a superior financial outcome. However, this strategy overlooks the mechanics of housing supply and demand. If mortgage rates were to drop significantly, the sudden influx of pent-up demand would likely outpace the current supply of housing inventory.
Historical evidence from the 2020-2021 housing boom illustrates this risk. As rates plummeted to historic lows, national home prices surged by approximately 14% within a single year, and by nearly 35% within two years. Even a modest 10% increase in home prices can effectively negate the monthly savings gained from a lower interest rate.
Consider a hypothetical scenario: A home priced at $500,000 with a 20% down payment ($100,000) at a 6.7% interest rate results in a monthly principal and interest payment of roughly $2,502. If that same home’s value increases to $550,000 due to heightened demand following a rate drop, the buyer would need a $110,000 down payment. Even at a lower rate, the increased principal and higher property taxes—which generally scale with home value—would erode the majority of the monthly savings. Furthermore, other fixed costs, such as homeowners insurance and private mortgage insurance, often increase in tandem with home valuations.
Broader Economic Implications
The decision to delay a home purchase is often framed as a prudent financial move, but it carries significant opportunity costs. For renters, the "waiting game" involves continued exposure to rising rental costs without the benefit of equity accumulation. In contrast, purchasing a home at current rates allows a buyer to begin building home equity immediately.
Financial advisors frequently point out that a mortgage is not a permanent financial commitment in the same way a lease is. If interest rates do decline in the future, homeowners have the option to refinance their existing loans. While refinancing involves transaction costs and requires meeting lender qualifications, it provides a hedge against the risk of rising home prices. By entering the market now, buyers lock in the purchase price of the asset; by waiting, they expose themselves to the volatility of a market that could become increasingly expensive.
Conclusion: Evaluating the Path Forward
The data suggests that the "low-rate" era was an anomalous period driven by extraordinary global crises that policymakers hope not to repeat. Relying on a return to those conditions is not a sound long-term strategy for wealth management or homeownership. The current economic reality—characterized by stable employment and persistent, if moderated, inflation—suggests that interest rates will likely remain in their current range for the foreseeable future.
For those in a position to purchase, the most logical path is to evaluate affordability based on current rates rather than speculative future ones. By focusing on the fundamentals of the property and one’s own financial capacity, buyers can make informed decisions that prioritize long-term stability over short-term market timing. Ultimately, the best time to buy a home is when a buyer finds a property that fits their needs and budget, with the understanding that the financial landscape is subject to change, and the flexibility to refinance remains a potential tool for the future.