For more than 80 years, the Securities and Exchange Commission’s Rule 14a-8 has served as the cornerstone of American corporate governance, providing a structured mechanism for shareholders to influence corporate policy and hold management accountable. However, a proposed regulatory shift by the SEC to potentially rescind or radically alter this rule has ignited a firestorm of debate among institutional investors, corporate boards, and legal scholars. While proponents of the change argue that the proxy process has become overly cluttered with social and environmental proposals, critics—led by groups like United Church Funds—warn that eliminating this federal framework would fundamentally undermine the democratic nature of public ownership in the United States.
The Historical Context and Evolution of Rule 14a-8
Established in the aftermath of the Great Depression, the Securities Exchange Act of 1934 aimed to restore investor confidence by mandating transparency. Rule 14a-8, which formalizes the process by which shareholders can submit proposals for inclusion in a company’s proxy statement, emerged as a vital tool for ensuring that directors remain responsive to the interests of those who provide the capital.
Throughout the mid-20th century, the rule was sparingly used, primarily for governance issues such as executive compensation or board structure. However, the 1970s marked a turning point in shareholder activism. Faith-based organizations and institutional investors utilized the proxy process to address systemic moral concerns, most notably by pressuring U.S. corporations to divest from South Africa during the height of the apartheid regime. This period established the precedent that "ordinary business" could encompass matters of significant social policy, a standard that has expanded to include climate change, data privacy, and worker safety in the modern era.
The Current Regulatory Impasse
The SEC’s current proposal, framed as a "reforming" measure, comes at a time when the volume of shareholder proposals has reached historic highs. According to data from the Proxy Monitor and various ESG research firms, the number of environmental and social (E&S) proposals submitted to U.S. public companies has increased by approximately 30% over the last five years.
Corporate management teams have increasingly complained that this surge represents an "activist" overreach, arguing that shareholders are using the proxy process to pursue narrow political agendas that may not align with the fiduciary duty to maximize long-term shareholder value. Conversely, investors argue that these E&S factors—such as supply chain resilience, carbon footprint, and board diversity—are material to a company’s long-term risk profile.
The SEC faces the difficult task of balancing these competing interests. The proposed rescission or modification of the rule would, in effect, shift the burden of proposal eligibility from federal oversight to a fragmented state-by-state approach.
The Fragmented Future: State Law vs. Federal Oversight
A primary concern among institutional investors is the potential for a "race to the bottom" regarding shareholder rights. Some states have already begun to move ahead of the federal government in restructuring these requirements. Texas, for instance, has pioneered legislation allowing corporations to implement significantly higher hurdles for shareholder engagement, including requirements for massive equity stakes—up to $1 million or 3% of voting shares—before a proposal can even be considered for the ballot.
If the federal standard under Rule 14a-8 is removed, the regulatory landscape would become a patchwork of state-level statutes. Legal experts suggest this would create significant compliance costs for institutional investors who hold diversified portfolios across various jurisdictions. Furthermore, it would likely disenfranchise smaller, long-term investors, as the cost of entry would be pushed out of reach for anyone but the largest hedge funds or state pension funds.
Implications for the 2027 Proxy Season
The uncertainty surrounding the SEC’s timeline has created a vacuum of predictability for the 2027 proxy season. With the public comment period concluding on November 20, 2026, many market participants are bracing for a period of litigation. Regardless of the SEC’s final decision, legal challenges are widely expected, potentially freezing any new rules in the courts for years.
The impact on corporate governance would be immediate. If the federal "safety valve" of Rule 14a-8 is removed, companies may find themselves facing an increase in direct litigation or private negotiation, as shareholders would be forced to seek alternative avenues to express their grievances. This could lead to less transparency, as proxy ballots—which are currently public and accessible—would be replaced by private settlements and backroom deals.
Proposed Alternatives: A Middle Ground?
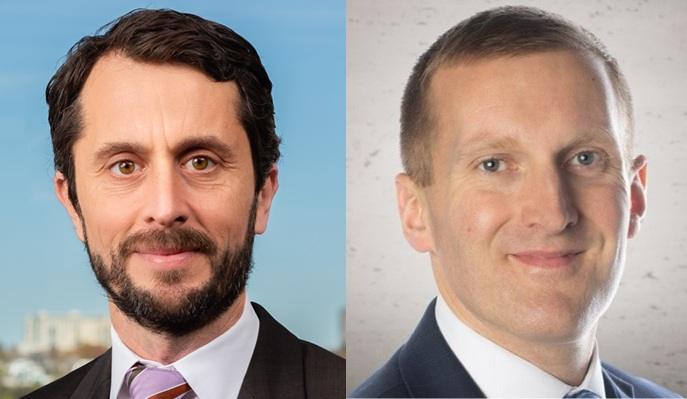
In their recent submission to the SEC, representatives from United Church Funds, including Director of Responsible Investing Matthew Illian and General Counsel Noah Tabor, proposed a constructive alternative to total rescission. They argue for the creation of an independent "Shareholder Proposal Review Service."
This proposed entity, operating within a federal framework, would serve as a clearinghouse for eligibility disputes. By utilizing a time-limited working group consisting of SEC staff, corporate counsel, and investor advocates, such a service could resolve disputes over whether a proposal is "material" or "merely political" in a timely, consistent, and cost-effective manner. This would alleviate the administrative burden on the SEC’s Division of Corporation Finance, which currently spends a significant portion of its resources adjudicating "no-action" requests—the process by which companies ask the SEC for permission to exclude a proposal.
The Economic Argument for Engagement
Critics of current shareholder activism often cite the "nuisance factor" of filing costs and management time. However, a 2025 study by the Journal of Corporate Finance suggests that companies that engage with shareholder proposals—even those that are ultimately rejected—tend to experience lower levels of "governance shock" over a five-year horizon. The findings imply that the proxy process acts as a pressure-release valve, allowing management to identify emerging risks before they manifest as full-blown operational or reputation crises.
For many investors, the ability to vote on proposals is not merely about the specific topic at hand, but about the preservation of the "shareholder-board" dialogue. When shareholders are denied the ability to place issues on the proxy, they often resort to divestment or proxy contests to replace board members, both of which are significantly more disruptive to corporate stability than a non-binding resolution.
A Call for Public Deliberation
As the November 20, 2026, deadline approaches, there is a growing consensus among transparency advocates that the SEC’s approach is insufficient. Simply collecting written comments is viewed by many as a "check-the-box" exercise for a policy shift that carries profound consequences for the American financial system.
Organizations across the investment spectrum are calling for the Commission to host public hearings or formal roundtables. Such forums would allow for a granular examination of the practical consequences of altering Rule 14a-8, particularly regarding how it would affect mid-cap and small-cap companies that lack the legal resources to navigate a new, complex regulatory environment.
Conclusion: Reform, Don’t Demolish
The consensus among seasoned observers is that while Rule 14a-8 is a product of a different era, its core function remains essential. The rule is undoubtedly imperfect; it has been used to advance frivolous motions and has occasionally been manipulated by special interest groups. However, to dismantle it in the name of efficiency is to discard one of the most effective tools for maintaining market integrity.
Modernization is necessary. The SEC should focus on updating the definitions of "ordinary business" and "economic relevance" to reflect the modern global economy, rather than stripping away the platform that enables the owner-manager dialogue. As the agency weighs its options, the focus must remain on the preservation of a functioning forum for accountability. If the goal of the Commission is to protect investors and maintain fair, orderly, and efficient markets, then the path forward is clear: improve the process, modernize the standards, and ensure that the voice of the shareholder continues to be heard in the boardroom. The alternative—a total loss of federal oversight—risks turning the proxy ballot into a relic of the past, to the detriment of long-term corporate health and investor trust.