
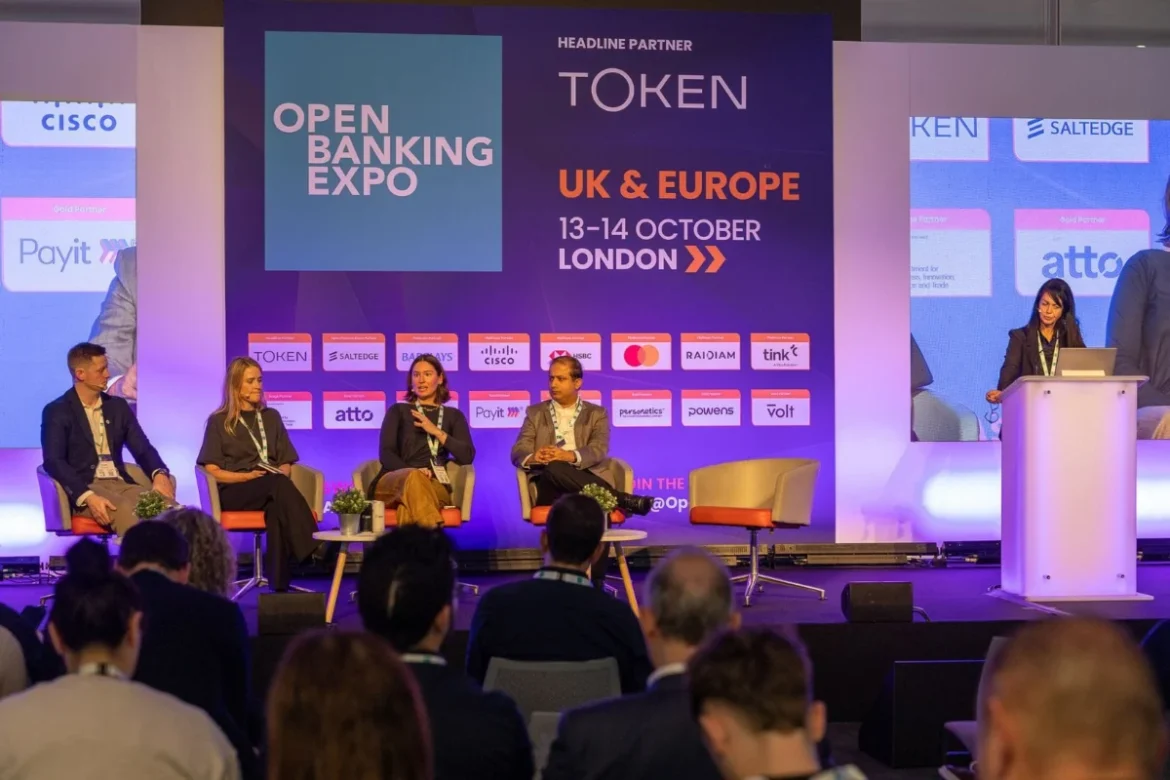
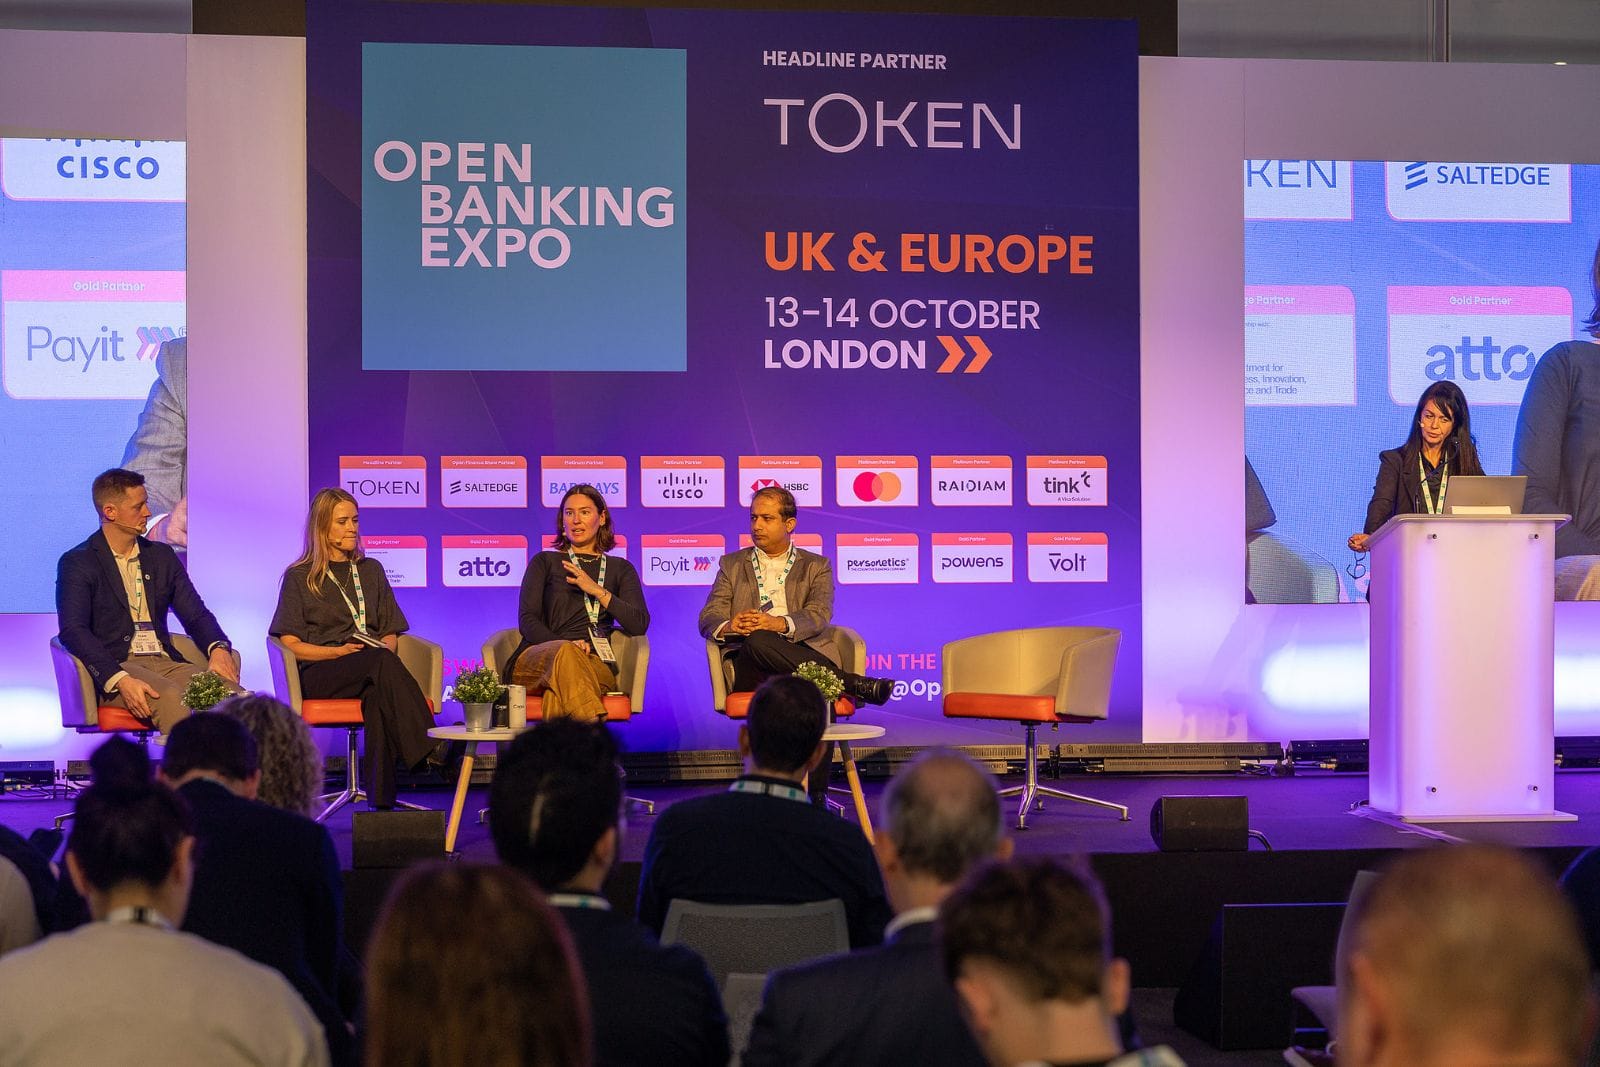
Open Banking payments face a critical juncture in their evolution, requiring substantial improvements in transaction data granularity, baseline reliability, and systemic consistency before they can truly challenge traditional card networks for mainstream dominance. Speaking at the prestigious Open Banking Expo UK & Europe 2026, leading figures from financial institutions and fintech giants—including Plaid, Barclays, HSBC, and Open Banking Limited—converged on the reality that while account-to-account (A2O) infrastructure has matured significantly, critical functional gaps still hinder mass corporate and consumer adoption.
The high-profile panel discussions, held against the backdrop of the UK government’s evolving National Payments Vision and a push toward a unified payments framework, highlighted both the immense modernization potential and the pragmatic operational hurdles facing the financial services ecosystem. While regulatory frameworks have successfully unlocked the initial wave of account-to-account capabilities, industry stakeholders agree that the next phase requires a laser-like focus on operational resilience, rich data transmission, and seamless cross-border interoperability.
Background and Context: The Evolution of the UK’s Payment Landscape
To understand the urgency of the debates at the Open Banking Expo 2026, one must examine the trajectory of the UK’s open banking regime. Launched initially in 2018 under a mandate from the Competition and Markets Authority (CMA) following the implementation of the second Payment Services Directive (PSD2), the UK’s open banking framework quickly became a global benchmark. By enabling third-party providers (TPPs) to securely access consumer bank accounts with explicit consent, the ecosystem catalyzed a generation of fintech startups offering personal finance management, digital lending, and streamlined payment initiation services (PIS).
However, despite reaching milestones of millions of active users, open banking payments have historically competed against deeply entrenched legacy card infrastructures. Visa and Mastercard offer near-universal acceptance, robust consumer protection frameworks, predictable cross-border functionality, and deeply integrated loyalty schemes. For open banking to transcend its current niche—predominantly used for specific bill payments, digital wallet top-ups, and niche e-commerce checkouts—it must achieve parity with, or superiority over, these legacy rails in everyday consumer and business scenarios.
The introduction of the UK’s National Payments Vision serves as the current strategic blueprint for addressing these legacy shortcomings. By encouraging a unified payments framework, policymakers aim to modernize domestic infrastructure, foster secure innovation, and protect financial stability. Yet, as industry executives made clear at the 2026 expo, regulatory vision must be matched by rigorous commercial execution.
The Roadblocks to Scale: Consistency, Limits, and Reliability
During a Main Stage debate moderated by Amanda Harrison, senior advisor at fscom, the panel dissected the friction points preventing businesses from fully embracing Pay by Bank solutions. Chris Corbett, head of product for the UK and Europe at Plaid, didn’t mince words regarding the current market reality. He emphasized that businesses require absolute confidence that alternative payment methods will function reliably across all operational use cases before they are willing to phase out traditional alternatives.
"There are very few people, for example, that just offer pay by bank and no other methods. And until you can do that, I think you’ve got a gap," Corbett stated during the session. He pointed out that fragmented payment limits, inconsistent technical standards across different banking institutions, and varying reliability metrics continue to act as major deterrents for enterprise-level deployment.
Crucially, Corbett argued that reliability must be treated as a foundational utility rather than a competitive differentiator among payment service providers. If a consumer attempts a Pay by Bank transaction and experiences a timeout or a rejected payment due to backend bank inconsistencies, the psychological barrier to returning to that payment method rises exponentially. For merchants operating high-volume checkouts, even a fractional increase in transaction failure rates compared to card rails is commercially unacceptable.
Transforming Payments into Data Products
While consumer checkouts represent the most visible face of open banking, the corporate and treasury landscape represents its most lucrative frontier. Michelle Stanley, director of digital banking at Barclays, argued that the modernization of payment infrastructure must move beyond mere speed enhancements to focus on the holistic utility of the transaction data itself.
"I think success should mean that we stop actually talking about the payment," Stanley told delegates, signaling a future where seamless execution becomes invisible, leaving businesses to focus on the accompanying value. For corporate treasury teams, the holy grail is the synthesis of payment certainty with rich, structured transaction data that enables automated reconciliation, instantaneous cash-flow visibility, and optimized working capital management.
Stanley highlighted that account-to-account payments currently lag behind traditional card schemes and specialized corporate messaging standards in the sheer volume and structure of data attached to each transfer. "We need to see payments as a data product," she asserted. Enhanced payment data payloads—leveraging ISO 20022 messaging standards—can drastically improve corporate fraud detection, automate complex enterprise workflows, and provide granular visibility into cash movements. Furthermore, Stanley underscored the necessity of international interoperability, noting that cross-border payments must eventually become as frictionless and transparent as domestic transactions to meet the demands of globalized commerce.
Variable Recurring Payments as a Defining Milestone
As the industry looks for measurable benchmarks of success under the National Payments Vision, the panel identified commercial Variable Recurring Payments (VRPs) as the ultimate stress test for the open banking ecosystem. VRPs allow customers to securely connect a third-party provider to their bank account to make recurring payments of varying amounts, offering a modern, API-driven alternative to traditional Direct Debits and standing orders.
Plaid’s Chris Corbett suggested that the emerging commercial VRP scheme—facilitated by the UK Payments Initiative—will provide a clear litmus test for the industry’s collaborative capability. His ambition is for recurring payments to rapidly scale into the largest segment of Pay by Bank transactions, proving that both the technical architecture and commercial incentives are robustly aligned.
Emily Rayment, head of public policy at Open Banking Limited, added that common technical standards have already proven their worth by lowering barriers to entry for fintech innovators. However, she stressed that these standards must maintain sufficient flexibility to accommodate rapidly evolving technological landscapes. Looking ahead, Rayment pointed to the integration of Open Banking payments directly into digital wallets as a potentially transformative development. By embedding A2O capabilities into widely used wallet ecosystems, consumers could soon experience open banking payments with the same familiarity and ease currently reserved for Apple Pay or Google Pay.
Artificial Intelligence: Opportunities, Consent, and Liability
No forward-looking discussion on financial technology in 2026 can exclude the impact of artificial intelligence. The panel explored the complex intersection between open banking data architectures and generative AI, identifying both unprecedented consumer benefits and new regulatory gray areas.
Citing internal research conducted by Plaid, Chris Corbett noted that half of UK consumers are already utilizing AI-powered tools to manage their finances, make budgetary decisions, or evaluate financial products. This trend creates a fertile ground for combining rich open banking transaction data with intelligent financial assistants, allowing for hyper-personalized banking experiences.
However, Open Banking Limited’s Emily Rayment injected a note of caution regarding the rise of "agentic payments"—transactions initiated autonomously by AI agents on behalf of consumers. While technically feasible, agentic payments introduce profound legal and operational questions surrounding user consent, authentication protocols, and liability allocation. If an AI agent executes an erroneous or fraudulent payment using an open banking connection, determining fault across banks, TPPs, and software developers remains an unresolved regulatory challenge.
Coordinating Modernization and Protecting Systemic Resilience
Balancing rapid innovation with the unshakeable stability of the financial system requires meticulous orchestration. Sovon Chatterjee, director of payment products at HSBC, emphasized that modernization efforts must not compromise the operational resilience of legacy infrastructure that underpins daily economic activity.
Chatterjee called for transparent implementation roadmaps, sustained cross-industry collaboration, and realistic timelines that allow financial institutions and corporate merchants to adapt smoothly to new architectures. Framing the National Payments Vision as a generational turning point, Chatterjee delivered a rallying cry to the sector: "National Payments Vision is once in a generation kind of opportunity. Let’s make the most of it."
Fact-Based Analysis of Implications
The insights emerging from the Open Banking Expo UK & Europe 2026 point to a maturing industry transitioning from a phase of regulatory compliance and basic connectivity to one focused on commercial viability and enterprise-grade value.
The implications of this shift are profound. For fintech providers and payment initiators, competing purely on the novelty of "bank-to-bank" transfers is no longer sufficient. Survival and growth necessitate closing the reliability gap with card networks, standardizing payment limits, and offering near-zero downtime. For traditional banks, the imperative is to monetize infrastructure upgrades by packaging payments with richer data payloads that appeal directly to corporate treasurers and CFOs.
Ultimately, the consensus among the industry’s senior leadership is clear: the success of the UK’s next-generation payment ecosystem will not be measured by the sheer volume of new standards introduced, but by whether the resulting infrastructure delivers demonstrably safer, more dependable, and more efficient financial transactions for every end-user and enterprise across the economy.
