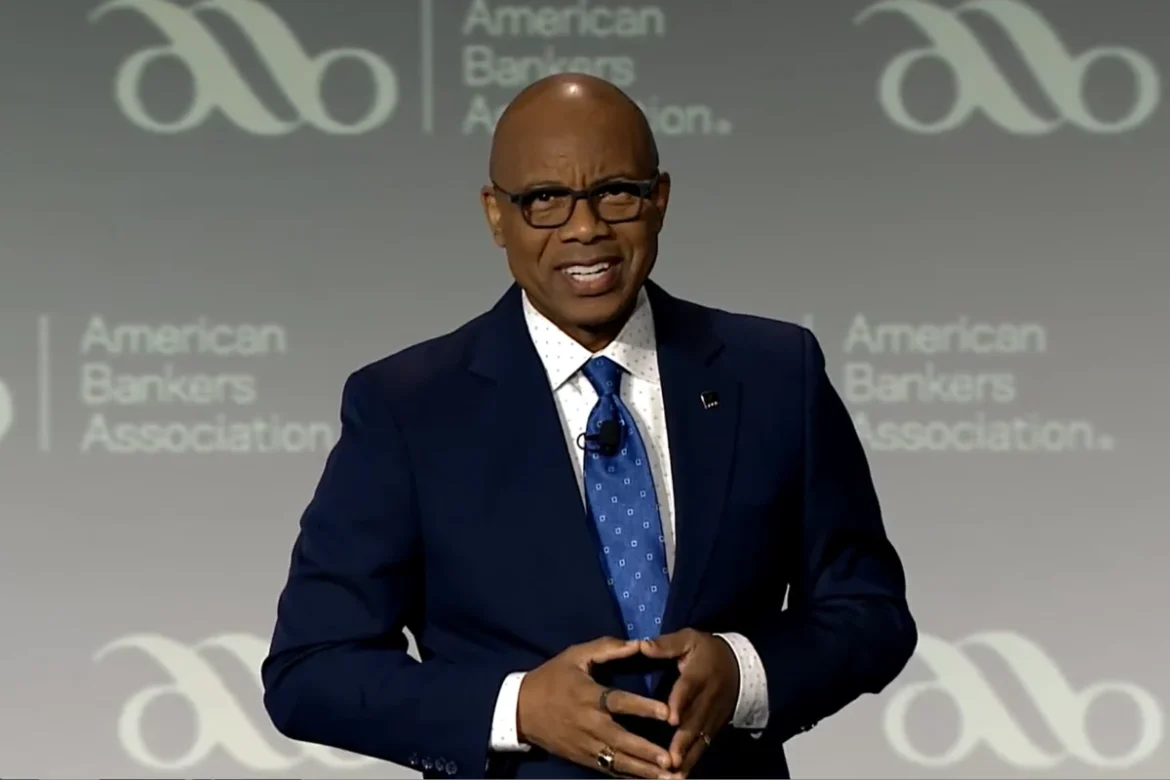
In a capstone address delivered at the American Bankers Association (ABA) Annual Convention, Kenneth Kelly, Chairman and CEO of Detroit-based First Independence Bank, concluded his tenure as ABA Chairman by outlining a definitive roadmap for the industry’s future. Addressing an audience of financial leaders, regulators, and policy experts, Kelly reflected on a transformative year marked by rapid technological disruption and a complex regulatory landscape, urging his colleagues to remain committed to a tripartite strategy of “advocating, innovating, and partnering.”
The speech served as a formal bookend to a term characterized by aggressive efforts to bridge the gap between traditional banking infrastructure and the burgeoning digital economy. As Kelly prepares to transition out of the leadership role, his message underscored the necessity of collective action in navigating the shifting sands of global finance.
A Year of Regulatory and Technological Transition
The past twelve months have been defined by a concerted effort by the ABA to reshape the federal regulatory framework. Under Kelly’s chairmanship, the organization intensified its lobbying efforts to “right-size” banking regulations, particularly those established in the wake of the 2008 financial crisis. The industry’s argument has been that legacy regulations, while intended to promote stability, have inadvertently created barriers to entry for smaller community banks and hindered the agility of larger institutions in the face of non-bank competition.
Kelly highlighted the organization’s persistent advocacy for a more nuanced approach to digital asset regulation. The central concern for the ABA has been the “level playing field” argument: the belief that banks, which operate under stringent capital requirements and consumer protection mandates, are at a competitive disadvantage when compared to crypto-native companies that have historically operated with fewer oversight requirements.
“The objective is not to stifle progress, but to ensure that the rules of the road are applied equitably,” Kelly noted during his address. “When we allow regulatory arbitrage to persist, we don’t just hurt the banking sector; we expose consumers to systemic risks that we are uniquely equipped to manage.”
The Chronology of an Active Term
The ABA’s strategic initiatives under Kelly’s leadership followed a clear, multi-phased timeline of development.
- Q4 2025: Regulatory Engagement: The term began with a heightened focus on the Basel III endgame and the impact of capital requirement increases on credit availability. Kelly spearheaded a series of roundtables that engaged both the Federal Reserve and the Office of the Comptroller of the Currency (OCC).
- Q1 2026: The Digital Asset Push: As the crypto market saw renewed volatility, the ABA accelerated its policy white papers on stablecoins, advocating for a federal framework that integrates digital currency into the existing banking system rather than treating it as an isolated silo.
- Q2 2026: The AI Integration: Recognizing that artificial intelligence was no longer a nascent tool but an operational imperative, the ABA launched task forces focused on the ethical use of AI in fraud detection and credit underwriting.
- Q3 2026: Workforce Development: Understanding that the “talent war” was affecting the sector’s ability to compete with Big Tech, the ABA expanded its professional development programs, focusing on technical upskilling for bank employees.
- Q4 2026: The Closing Mandate: The annual meeting served as the culmination of these efforts, with Kelly calling for the institutionalization of the collaborative spirit fostered during his tenure.
Data-Driven Challenges in the Modern Banking Landscape
The urgency of Kelly’s message is grounded in tangible industry data. According to recent FDIC reports, the community banking sector—represented by many of the ABA’s core members—has faced a consistent tightening of net interest margins (NIM) throughout 2026. This pressure is compounded by the rise of fintech competitors who operate with lower overhead costs due to the absence of physical branch networks.
Furthermore, the threat of financial fraud has reached an inflection point. Industry analysts report that fraud-related losses in the U.S. banking system topped $15 billion in the most recent fiscal year, largely driven by sophisticated AI-generated phishing and synthetic identity fraud. Kelly’s emphasis on “partnering” is directly linked to these figures; he advocated for greater data-sharing between financial institutions to build a defensive perimeter that no single bank could maintain alone.
Regarding the digital asset landscape, the data reflects the ABA’s concern. While bank-led digital payment initiatives have grown by approximately 18% year-over-year, the volume of transactions processed through decentralized finance (DeFi) protocols has seen even steeper growth, often without the benefit of the AML (Anti-Money Laundering) and KYC (Know Your Customer) safeguards that are the bedrock of the traditional banking system.

Official Responses and Industry Sentiment
The response from the broader banking community has been one of broad consensus. Representatives from both regional and national banks have praised Kelly’s tenure for prioritizing the “unifying” role of the ABA.
“Ken’s leadership style was defined by inclusion,” noted one executive from a top-ten U.S. bank. “He recognized that the needs of a small rural community bank in Michigan are fundamentally linked to the global strategy of a money-center bank. His call to innovate isn’t just about software; it’s about innovating how we represent ourselves in Washington.”
Regulators, while often at odds with industry lobbying groups, have signaled an openness to the collaboration Kelly proposed. Several officials have recently commented on the necessity of “public-private partnerships” in addressing cybersecurity threats, echoing the sentiment Kelly expressed regarding the need to share resources to fight fraud.
Broader Impact and Implications for the Future
The implications of Kelly’s final speech reach beyond the walls of the convention hall. By positioning “advocacy, innovation, and partnership” as the three pillars of future banking, Kelly is setting a mandate for his successor. The shift toward a more proactive, rather than reactive, posture is a recognition that the industry is in the midst of a generational transition.
The “innovation” pillar, in particular, carries significant weight. As banks look toward 2027 and beyond, the integration of generative AI into customer service and back-office operations is expected to become the primary differentiator between successful institutions and those that stagnate. Kelly’s emphasis on workforce development suggests that the industry recognizes that technology is only as effective as the human talent directing it.
Furthermore, the focus on “partnership” is an acknowledgement of the reality that banking is becoming increasingly modular. Banking-as-a-Service (BaaS) and partnerships between traditional lenders and fintech startups have become the new normal. Kelly’s message effectively gives the “green light” to his constituents to lean into these partnerships, provided they are built on a foundation of sound risk management and regulatory compliance.
Conclusion: The Strength of the Collective
As Kelly handed the reins to his successor, his final remarks were intended to leave the industry with a sense of purpose. By emphasizing that the banking sector is “strongest when we’re working together,” he sought to counteract the fragmentation that often occurs during periods of intense economic pressure.
The challenges facing the industry—from the evolution of digital payments to the complexities of climate-related financial risk—are too large for any single institution to address in isolation. Kelly’s tenure, therefore, stands as a blueprint for institutional cohesion. As the banking industry moves into the next calendar year, the “Kelly doctrine” of advocacy, innovation, and partnership is expected to remain the North Star for the ABA’s policy agenda, providing a framework for banks to remain both profitable and essential in an era of rapid change.
The task ahead for the American banking sector is significant, yet the consensus among observers is that the foundation laid during this year of transition has provided the necessary stability to face these challenges. Whether through the implementation of new cybersecurity protocols or the ongoing dialogue with Capitol Hill, the call to action remains clear: the industry must not only adapt to the future but actively participate in its construction.