
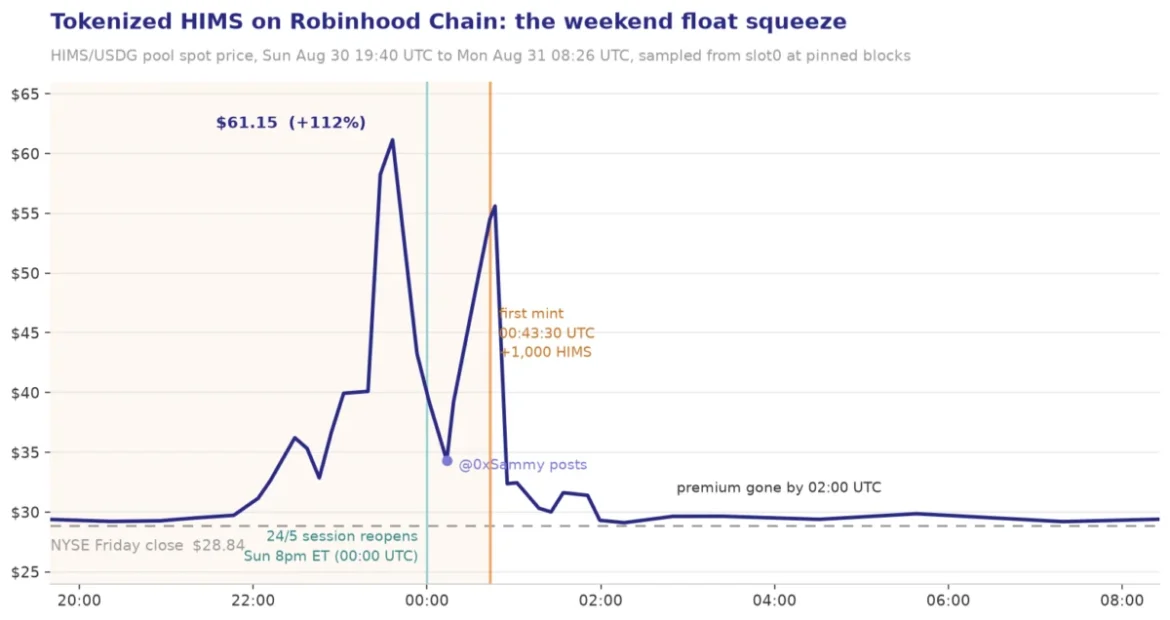
At 23:36:14 UTC on Sunday, August 30, 2026, the tokenized Hims & Hers (HIMS) stock on the Robinhood Chain recorded a price of $61.15 within its primary liquidity pool, a figure that stood in stark contrast to the $28.84 closing price of the underlying equity on the New York Stock Exchange (NYSE) just two days prior. This dramatic price dislocation was not triggered by any material news concerning the pharmaceutical company itself, nor was it a result of volatility in the traditional equity markets. Instead, the incident served as a high-stakes demonstration of the fragility inherent in tokenized real-world assets (RWAs) when the liquidity of a synthetic wrapper is tethered to the speculative mechanics of a memecoin ecosystem during non-market hours.
The event, which saw the tokenized HIMS asset trade at a premium of over 100% against its net asset value (NAV), was orchestrated by a memecoin known as BONER. By routing nearly all of its liquidity through a BONER/HIMS trading pair, the memecoin effectively weaponized the tokenized stock, turning a small, on-chain supply of equity wrappers into the primary collateral for a speculative retail frenzy.
A Chronology of the Squeeze
The mechanics of the disruption began to manifest in the late hours of the weekend. As of the close of the NYSE on Friday, August 28, the on-chain float of HIMS was relatively thin, totaling approximately 15,226 tokens. This supply, while intended to reflect the broader performance of the publicly traded equity, was subject to a rigid issuance schedule. Because the underlying shares are held by a Robinhood subsidiary, the token supply can only be expanded when the traditional stock market is open, allowing for the hedging of new token issuance.
The squeeze unfolded in three distinct phases:
- The Buildup (August 28–30): Following the Friday close, the on-chain float was further constrained by redemption activity. Two separate burns occurred on Friday evening, reducing the total supply by 900 tokens. As the weekend progressed, market-making wallets remained largely devoid of inventory, relying on a "just-in-time" minting model that was incapacitated by the weekend closure of the equity markets.
- The Peak (August 30, 22:00–23:53 UTC): At approximately 22:00 UTC on Sunday, buying pressure for the BONER token began to accelerate. Because the BONER/HIMS pool held the vast majority of the on-chain HIMS liquidity, the demand for the memecoin acted as a forced buy order for the tokenized stock. By 23:36 UTC, the price hit its zenith of $61.15.
- The Unwind (August 31, 00:43–02:00 UTC): The equity session on the Robinhood Chain reopened at 00:00 UTC on Monday. Once the issuer was able to purchase the underlying shares to back new token issuance, the minting process commenced. At 00:43:30 UTC, the first batch of 1,000 tokens was injected into the ecosystem. Over the next two hours, the issuer minted nearly 19,000 tokens, flooding the market and effectively collapsing the premium. By 02:00 UTC, the HIMS token had returned to within 2% of its Friday NYSE close.
Structural Vulnerabilities in Tokenized Finance
The Robinhood Chain, launched in July 2026 as an Arbitrum Orbit L2, was designed to bring the efficiency of decentralized finance (DeFi) to equity trading. However, the BONER incident highlights a fundamental disconnect: while the stock tokens are composable and freely transferable, their issuance is tethered to a traditional, permissioned financial schedule.
The "liquidity question" that has plagued developers since the chain’s inception—how to maintain a peg to a reference price that is only active for 6.5 hours a day—was answered definitively. When a tokenized asset has a small float and is utilized as a base currency for memecoin liquidity, the price of the stock token is no longer determined by the underlying company’s fundamental value. Instead, it is dictated by the algorithmic supply-and-demand constraints of the AMM (Automated Market Maker).
For the issuer, the arbitrage was theoretically lucrative. By minting new tokens at the $28.84 NAV and selling them into the inflated $61.15 market, the broker captured the spread. For the retail traders caught on the wrong side of the squeeze, the experience was a cautionary tale in "float exhaustion."

The Memecoin-Equity Feedback Loop
The relationship between BONER and HIMS illustrates a sophisticated, albeit predatory, market structure. By creating a liquidity pool where BONER is paired directly against HIMS, the developers ensured that any trader attempting to buy the memecoin would inherently impact the price of the equity wrapper. This is not a novel concept; earlier in the year, a GameStop-themed memecoin attempted a similar strategy. However, the HIMS event was particularly effective due to the small size of the on-chain float, which made it easier for speculative capital to overwhelm the pool’s depth.
Data analysis from the event indicates that at the height of the squeeze, roughly 94% of the on-chain HIMS supply was locked within Uniswap v4 pools. With such a low percentage of the float available for arbitrage, the price became hypersensitive to even minor trade volumes. This created a "reflexive" market cap for the memecoin: as the price of HIMS climbed, the displayed valuation of BONER grew, attracting further speculative inflow and creating a self-reinforcing cycle of price distortion.
Regulatory and Operational Implications
From a professional standpoint, this event underscores the risks of a "two-tier" market. Because Robinhood’s tokenized stock offerings are generally restricted from U.S. retail investors—the very demographic most likely to engage with high-volatility memecoin projects—there is a stark lack of institutional arbitrageurs present to "short" or dampen these localized spikes. The memecoins, by contrast, operate with few such restrictions, creating an environment where the "pricing leg" of the asset is essentially unregulated and disconnected from the underlying equity reality.
The silence of the issuer throughout the weekend was not a sign of operational failure, but rather a structural limitation. Without the ability to trade the underlying HIMS stock on the NYSE, the issuer lacked the capacity to hedge, and therefore could not mint. This "closed-window" status is a feature of the current RWA design, but as this event demonstrates, it leaves the chain vulnerable to manipulation.
Future Outlook and Risk Mitigation
Market observers and blockchain analysts are now looking toward the next iteration of such "float corners." With the playbook now public, small-cap stocks listed on the Robinhood Chain are being viewed as potential targets for similar liquidity traps.
Moving forward, potential mitigations include:
- Pre-minting or holding a larger buffer of "standing inventory" to absorb volatility when traditional markets are closed.
- Implementing circuit breakers on the AMM that prevent extreme deviations from the last known NYSE price.
- Increasing the transparency of the "mint window" to ensure that market participants are aware of when the issuer can re-supply the float.
The episode concluded without affecting the actual Hims & Hers company, proving that the volatility was contained entirely within the synthetic, on-chain layer. However, the speed and scale of the move—where a stock token was repriced by over 100% in a matter of hours—suggest that as these assets become more popular, the potential for "rehearsals" like this to escalate into broader market shocks remains high. The system functioned as designed, but it proved that when the "real world" closes for the weekend, the "on-chain" world is capable of writing its own, often chaotic, reality.
