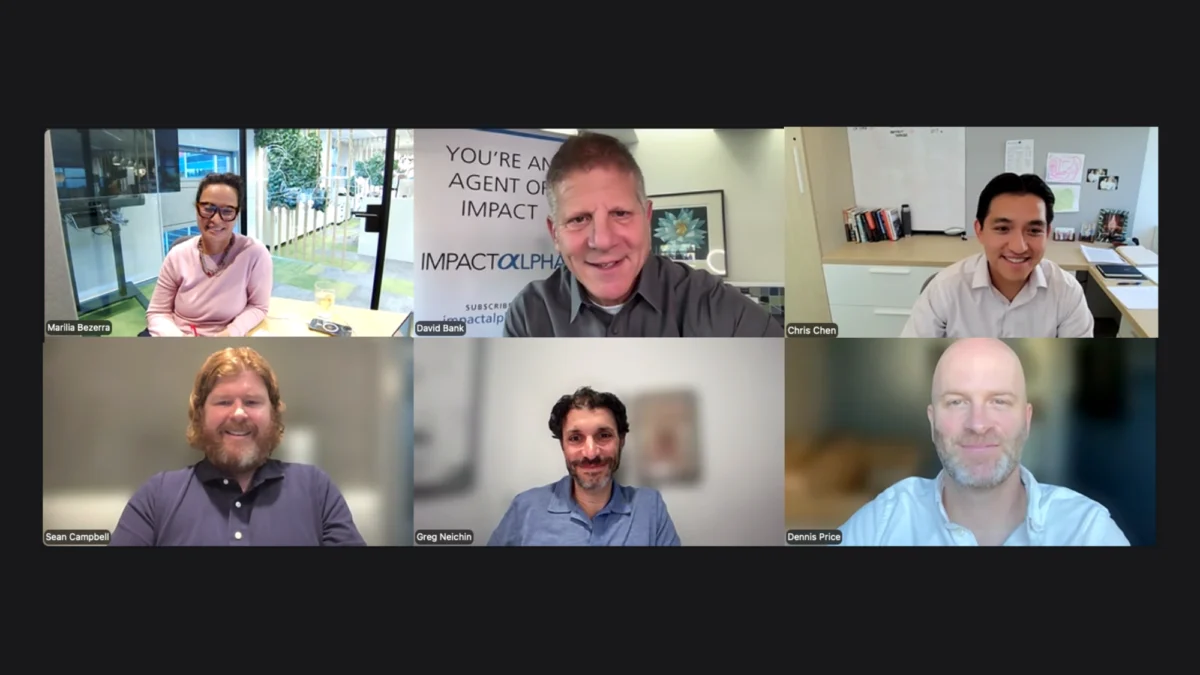
The shifting paradigm of global philanthropy and sustainable finance took center stage during a recent gathering of institutional investors, family offices, and market strategists known collectively as Agents of Impact. Eschewing the conventional macroeconomic commentary that typically dominates financial circles, the participants tuned in to examine a burgeoning asset class: impact-first investing. Representatives from the IKEA Foundation, Arnold Ventures, Earlystone, and Ceniarth converged to deconstruct how modern institutional allocators are deploying capital where social and environmental mandates supersede traditional risk-adjusted financial returns.
For decades, the boundary between philanthropy—defined by non-repayable grants aimed at social good—and private equity or venture capital, which demands maximum financial extraction, remained rigid. However, a new wave of capital allocators is intentionally blurring these lines. Operating on the foundational premise that capital should be structured around the specific nature of a systemic problem rather than the constraints of a financial model, these organizations are proving that patient, flexible capital can address intractable global challenges. While their specific operational mandates, geographic focuses, and asset classes vary widely, these pioneers share a unified philosophy: start with the problem, design the financial architecture accordingly, and let the economic returns follow organically.
The Evolution of Regulatory Frameworks and Institutional Mandates
The momentum behind impact-first investing is not merely ideological; it is being propelled by structural shifts in regulatory environments and a growing disillusionment with pure-play commercial impact investing. Critics of mainstream impact investing frequently point to "impact washing," a phenomenon where traditional venture capital or private equity funds market themselves as socially responsible while primarily pursuing commercial alpha with only tangential social benefits. In contrast, impact-first LPs are explicit about their willingness to accept sub-market financial returns, capital preservation, or even total loss of principal if the corresponding social or environmental dividends are sufficiently high.
A primary catalyst for this movement has been the gradual evolution of legal and regulatory frameworks governing charitable endowments and private foundations. Historically, foundation trustees faced stringent fiduciary duties that prioritized the preservation and growth of corpus assets above all else, often discouraging non-grant deployments into high-risk, low-return enterprises. However, regulatory updates—such as those enacted in the Netherlands in 2024, which expanded the legal scope for charitable foundations to engage in public-benefit investments—have unlocked billions of capital previously restricted to traditional grantmaking.
This regulatory modernization allows institutional philanthropies to operate along a continuum of capital. They can now seamlessly transition from traditional non-repayable grants for early-stage ecosystem development to debt instruments, guarantees, and direct equity stakes in enterprises that traditional commercial markets routinely ignore due to perceived high risk or administrative complexity.
Problem-First Philanthropy: The IKEA Foundation Approach
Among the most prominent institutional participants driving this evolution is the IKEA Foundation, a Netherlands-based philanthropic powerhouse that has historically relied on grantmaking to fulfill its mission. Following the recent adaptation of Dutch regulatory guidelines, the foundation has systematically built an investment practice that runs parallel to its traditional grant portfolio, operating under a singular, uncompromising mandate: to fight global warming with and for the many people.
Marilia Bezerra, chief program officer at the IKEA Foundation, emphasized during the briefing that the organization’s capital cannot and does not conform to commercial expectations, even if leadership desired it. Because the foundation’s assets are explicitly dedicated to public-benefit outcomes, the investment team is liberated from the pressure of chasing market-rate financial hurdles.
Instead, the foundation adopts a strictly problem-first methodology. Whether the initiative involves architecting regenerative food systems to support smallholder farmers in Brazil or deploying climate adaptation strategies across Kenya, Uganda, Ethiopia, India, and Indonesia, the analytical process invariably begins with the systemic challenge at hand. Only after the environmental or social parameters are thoroughly mapped does the team determine the appropriate financial instrument required to effect change.
Bezerra offered a sharp critique of the broader sustainable finance sector, arguing that impact investors seeking commercial returns frequently suffer from an overinflation of ambition. In her view, market-rate impact funds often set unrealistic expectations for both financial yields and social outcomes, ultimately underdelivering on both fronts. By shedding the obsession with commercial alpha, the IKEA Foundation aims to maintain strict parity between its ambition and its practical delivery, using its rare capacity to absorb high risk in geographies and sectors that commercial capital fundamentally avoids.
The Implied Grant Value Framework at Arnold Ventures
While the IKEA Foundation focuses heavily on international development and climate resilience, Arnold Ventures—founded in 2008 by philanthropists Laura and John Arnold—has carved out a distinct methodology rooted in evidence-backed policy, rigorous data analytics, and market-building within the United States. Traditionally known for funding randomized control trials to determine what social interventions actually work, Arnold Ventures has integrated direct impact investing as a critical mechanism to scale proven solutions in areas such as housing affordability, criminal justice reform, and healthcare access.
Led by Chris Chen, the impact investing team at Arnold Ventures functions with rigorous selectivity. Operating without a mandatory internal financial returns hurdle, the team evaluates potential transactions through a specialized lens adapted from the Bill & Melinda Gates Foundation: the "implied grant value."
Under this analytical framework, Chen’s team underwrites every prospective deal as if they were purely financially motivated investors. They then compare the projected risk-adjusted financial return of the asset against a standard market-rate benchmark. The differential—representing the financial return sacrificed by the investor—is quantified as the implied grant value. This methodology allows philanthropy to evaluate a direct equity investment, a low-interest subordinated debt facility, and a traditional philanthropic grant on a single, comparable scorecard, weighing the precise social impact purchased by the concessionary capital.
A prime illustration of this philosophy in action is Arnold Ventures’ early-stage backing of real estate developers utilizing California’s Starter Home Revitalization Act. This legislative framework allows property owners to partition large single-family backyards into as many as ten distinct parcels for townhomes or compact housing units. By providing early-stage, patient capital to validate an innovative, decentralized housing model, Arnold Ventures is helping to prove the commercial viability of a concept that traditional lenders view as overly novel or legally complex.
Chen is candid about the structural limits of philanthropic capital. He acknowledges that the multi-million-unit housing deficit in the United States cannot be resolved through philanthropy alone. Consequently, the primary objective of Arnold Ventures’ impact investments is not to permanently subsidize housing construction, but to de-risk innovative models effectively enough to crowd in commercial real estate developers and institutional capital. This introduces the perennial challenge of additionality—or the "but for" test. Chen noted that investment professionals must constantly interrogate whether a deal is being ignored by mainstream markets because it is fundamentally flawed or simply because it falls outside conventional underwriting parameters.
Financing the Overlooked: Earlystone and Community-Led Assets
For asset managers operating on behalf of single clients with deeply held values, the definition of market failure is often symptomatic of systemic undervaluation rather than poor economic fundamentals. Sean Campbell, who leads the community investing strategy at Earlystone, articulated a foundational critique of modern capital markets: when financial institutions routinely undervalue specific demographics, marginalized communities, and grassroots labor, the fault lies within the architecture of the markets themselves, not in the underlying reality of the assets.
Earlystone approaches impact not as an asset class feature, but as an operational methodology executed in direct partnership with organized communities. This philosophy is reflected in the firm’s transaction history, which includes backing Integrity Community Solutions in its pioneering effort to convert a manufactured home park into a resident-owned cooperative. More recently, Earlystone turned its attention toward the Bronx, evaluating the complex redevelopment of a decommissioned armory in partnership with a local community organization that secured a 20% equity stake via a 99-year ground lease.
Such transactions fundamentally challenge conventional real estate finance. While the deal economics pencil out sustainably over the long term, Campbell observed that no traditional commercial investor would willingly absorb the administrative and structural complexity—the metaphorical "brain damage"—associated with navigating a $20 million to $30 million real estate transaction alongside an active community coalition and non-standard cash flow profiles.
Campbell posits that market investability exists on a continuous spectrum. The realization of high-impact community projects is rarely correlated strictly with risk-adjusted financial returns; rather, it correlates inversely with the friction and difficulty required for an investment professional to shepherd the deal through legal, regulatory, and structural hurdles.
The Ceniarth Perspective: Acknowledging the Boundaries of Blended Finance
The debate over the degree to which impact-first capital can successfully integrate with or catalyze commercial markets remains fierce. Few institutions have articulated the strict impact-first thesis as consistently as Ceniarth, a family office that has long advocated for concessionary capital deployment in deep-impact sectors such as community development financial institutions (CDFIs) and microfinance institutions in emerging markets.
Greg Neichin of Ceniarth offered a sobering assessment of the landscape, bluntly reminding observers that while impact-first allocators use financial instruments, the underlying exercise is fundamentally philanthropic. Ceniarth’s explicit objective for its impact-first portfolio is to generate verifiable social impact while preserving or recovering a portion of its principal—typically targeting a small positive return or a modest break-even portfolio performance.
Neichin cautioned against harboring unrealistic expectations regarding crossover with pure-play commercial investors. Utilizing an athletic analogy, he suggested that while impact-first investors and commercial Wall Street allocators both operate within the broad arena of finance, their objectives, risk tolerances, and metrics of success are as fundamentally misaligned as those of a golfer and a football player. Fully funding rural CDFIs or high-impact microfinance networks, Neichin argued, represents a domain where commercial capital will simply never tread organically.
Ceniarth’s recent portfolio disclosures indicate that its impact-first allocations are roughly breaking even. However, Neichin was quick to contextualize this financial performance, noting that such results heavily rely on an ecosystem of even more catalytic actors—including first-loss capital providers and guarantors who absorb disproportionate risks to enable secondary investors like Ceniarth to achieve modest, low-single-digit returns.
This perspective generated pushback from veteran development finance experts, including Bob Annibale, a senior fellow at the University of London. Annibale contended that even highly derisked blended finance structures serve a vital educational purpose for mainstream financial institutions. By establishing a verifiable performance track record, concessionary investments gradually prevent commercial bank credit committees from treating community-level and underserved assets as high-risk "junk."
While initially defending a position of pragmatic cynicism, Neichin ultimately conceded the point, acknowledging that repeated validation of non-traditional assets slowly erodes institutional bias within banking compliance and credit risk departments.
The Unfunded Prequisites of Investability: Ecosystem Preparation
A recurring theme across all institutional contributions was the hidden cost of making underserved communities and projects investable in the first place. Theresa van der Walt of Terra Vita Global raised a critical operational question during the recent briefing: who ultimately finances the foundational groundwork required before capital can be deployed—including local evidence gathering, community engagement, governance structuring, and financial preparation?
The consensus among the allocators was stark. Investors like Ceniarth rarely fund this preliminary capacity-building directly, yet they are entirely dependent upon it to execute their mandates. Consequently, impact-first investors must rely heavily on the technical assistance facilities of grantmaking foundations and specialized non-profits to prepare the ground.
Similarly, the IKEA Foundation approaches new geographic mandates by mapping entire ecological and socio-economic systems—such as Indonesia’s threatened peatlands—to determine precisely where non-repayable grants are required to build foundational market infrastructure before investment capital can safely enter. Bezerra reiterated that the ultimate value of philanthropic capital lies in its unmatched freedom to absorb ambiguity and uncertainty.
Analytical Implications for the Future of Sustainable Finance
The convergence of institutions like the IKEA Foundation, Arnold Ventures, Earlystone, and Ceniarth signals a maturing of the impact investing movement. For over a decade, the industry was dominated by a singular narrative: that every social or environmental problem could be solved profitably if packaged correctly for the capital markets.
The rise of explicit, unashamed impact-first mandates introduces a necessary dose of realism. By formally decoupling social outcomes from commercial return expectations, these allocators are carving out a permanent, highly specialized niche at the intersection of philanthropy and finance. Their willingness to embrace complex legal structures, accept concessionary yields, and absorb first-loss positions demonstrates that while capital markets are powerful engines of economic growth, they require patient, problem-focused intervention to address the structural inequalities left in their wake. As regulatory frameworks continue to adapt and institutional allocators refine tools like implied grant valuation, the impact-first sector is poised to play an increasingly vital role in financing a more equitable and resilient global economy.