The landscape of financial technology and domestic payments in the United Kingdom reached a pivotal juncture at the recent Open Banking Expo Regulator Day and Open Banking Expo UK & Europe 2026. Convening key figures from across the financial sector, the event provided a high-profile platform for the UK Payments Initiative (UKPI) to thrust the conversation regarding commercial variable recurring payments (VRP) directly into the spotlight. Regulators, legacy clearing banks, nimble fintech innovators, digital platforms, major merchants, and a diverse array of broader industry stakeholders gathered to debate, align, and strategize the operational framework necessary for a modern payment ecosystem.
With the official launch slated for June 2026, the urgency to bridge policy intent with live, scalable commercial capability dominated the agenda. The multi-day conference served as a crucible for hammering out the intricate technical standards, scheme rules, and economic frameworks required to transition commercial VRP from conceptual design to everyday consumer utility.
Delivering the National Payments Vision Through Collaboration
At the heart of the conference’s Regulator Day proceedings was a flagship panel discussion led by the UKPI entitled, “Delivering the National Payments Vision through industry collaboration: The case of commercial VRP.” Moderated by Claudio Pollack, independent non-executive chair at UKPI, the session drew upon a cross-section of industry expertise. Joining Pollack on stage were George Miltiadous, head of Open Banking at HSBC; Charles Damen, chief product officer at Token.io; Briony Krikorian-Slade, head of governance and strategy at UKPI; and Alex Kirykowicz, director at Frontier Economics.
The composition of the panel was deliberately comprehensive, reflecting the multifaceted perspectives required to make commercial VRP operational and commercially viable. By uniting traditional banking heavyweights with agile fintech developers, and backing their insights with rigorous economic advice alongside well-structured scheme governance, the panel mapped out a collaborative blueprint.
During the session, Pollack emphasized the foundational role of cooperation in achieving long-term systemic change. He noted that the UKPI demonstrates how the market can effectively build upon shared technical standards and forge a cohesive commercial model capable of transforming regulatory policy into tangible market reality. Furthermore, Pollack highlighted that the initiative’s scope extends far beyond the upcoming June 2026 launch, with strategic plans already in motion to develop and introduce additional open banking products.
The Journey to Launch: A Test and Learn Methodology
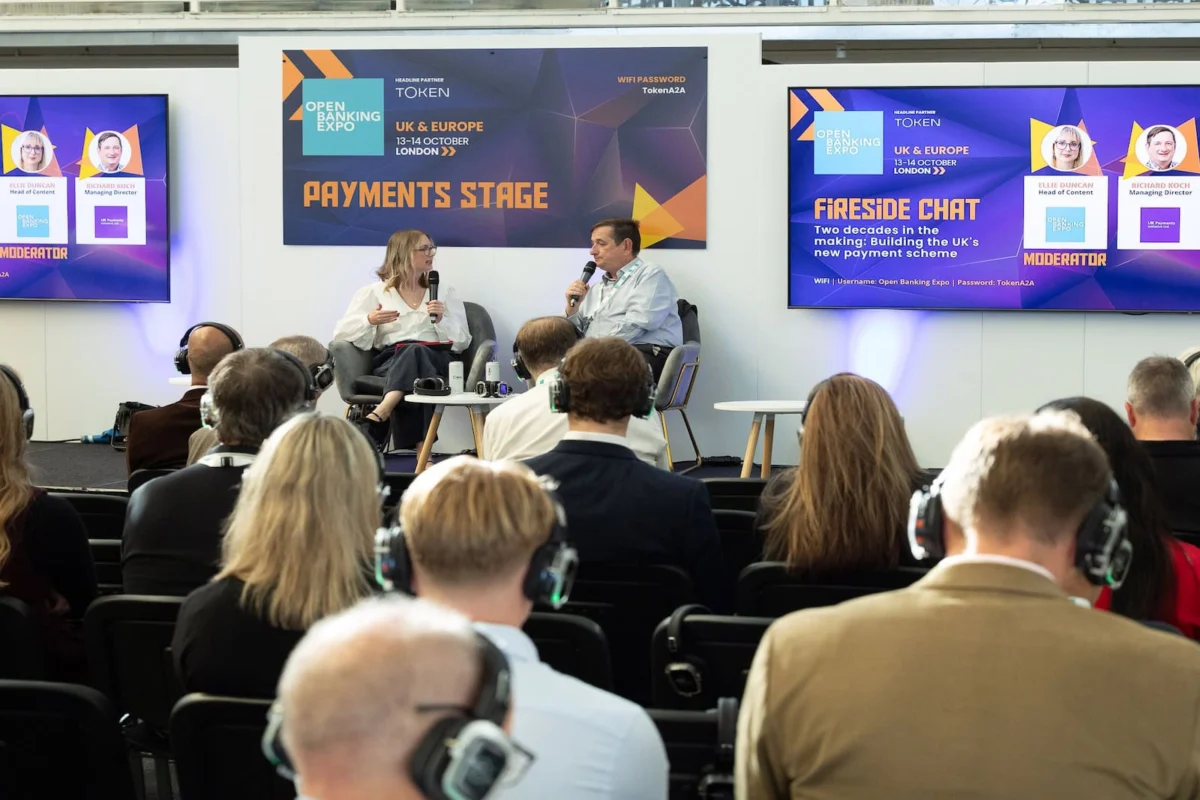
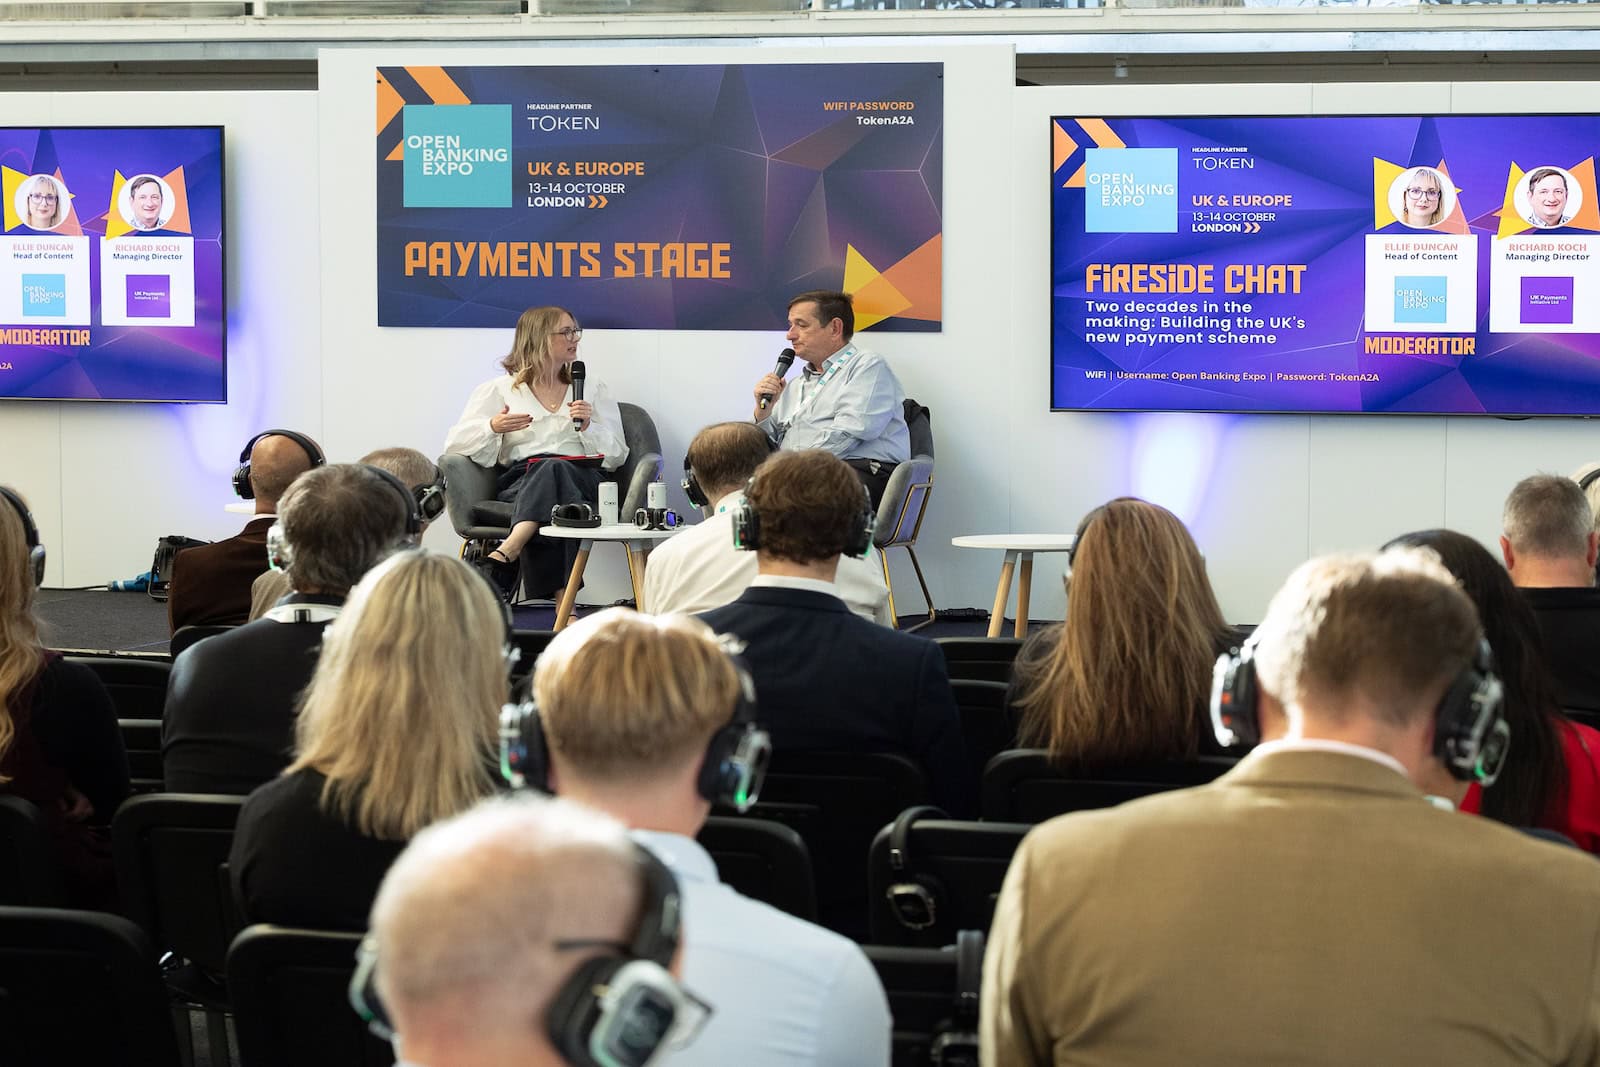
Providing deeper historical context to the initiative, UKPI managing director Richard Koch addressed attendees in a dedicated fireside chat titled, “Two decades in the making: Building the UK’s new payment scheme.” Koch’s remarks reflected on the protracted evolution of the UK payments landscape over the past twenty years, detailing the precise catalysts that necessitated the creation of a brand-new, industry-led scheme. He outlined the arduous journey of translating a high-level concept into an active national infrastructure, emphasizing the extraordinary diplomatic and technical coordination required to bring banks, third-party providers (TPPs), and regulatory bodies into alignment behind a single shared vision.
Rather than pursuing a risky, "big-bang" deployment across the entire economy, Koch characterized the UKPI’s overarching strategy as a deliberate "test and learn journey." This incremental approach focuses on validating the foundational payment model through carefully selected Wave 1 use cases. By evaluating performance during early live implementations, the scheme aims to build institutional confidence and iron out operational friction before attempting broader systemic scaling.
During the discussion, Koch also addressed the economic realities of payment processing, drawing comparisons between commercial VRP and legacy alternatives like Direct Debit. While acknowledged as a traditionally low-cost mechanism for larger merchants, Koch pointed out the hidden operational inefficiencies of Direct Debit. He argued that Direct Debit is only cost-effective when transactions proceed without exception; the cumulative administrative and financial overhead associated with payment failures, mandate cancellations, chargebacks, and consumer disputes can quickly erode those initial savings.
Wave 1 Use Cases and Cross-Sector Engagement
Across the exhibition halls and breakout sessions of the 2026 Expo, engagement surrounding the initial rollout of commercial VRP was notably high. Stakeholders from a wide spectrum of consumer-facing sectors—including utilities, telecommunications, public transport, financial services, central and local government, and charitable organizations—actively explored how the technology could optimize their respective billing and collection cycles.
Discussions throughout the event crystallized around two paramount priorities necessary to guarantee widespread market adoption:
- Market Awareness and Value Proposition: Industry participants stressed the critical need to educate both corporate entities and end-users, ensuring that the distinct benefits of account-to-account (A2A) recurring payments are clearly articulated.
- Consistent User Experience: Delivering a frictionless, highly secure, and universally positive consumer interface was identified as the ultimate driver for mass adoption, ensuring that consumers feel as comfortable authorizing an open banking payment as they do tapping a contactless card or utilizing a traditional direct debit instruction.
Strengthening the Ecosystem: Milestone Shareholder Growth
The timing of the Open Banking Expo coincided with a major corporate milestone for the UKPI, which officially celebrated the successful close of its latest subscription funding period. The initiative now boasts a robust roster of 26 dedicated shareholders. This coalition includes 10 major high-street banks and building societies, establishing a strong foundation of traditional institutional backing alongside an influential cohort of fintech innovators and payment service providers.
This diverse ownership structure is viewed by market analysts as essential for fostering universal trust. By ensuring that both legacy financial institutions and disruptive market challengers share a vested interest in the governance of the scheme, the UKPI has positioned itself to deliver a scalable, secure framework where account-to-account recurring payments can function efficiently for consumers, merchants, and financial intermediaries alike.
Scaling Up: Risk, Fraud, and Consumer Protection
Looking past the initial June 2026 go-live date, industry conversations at the Expo quickly pivoted toward the complex architecture required for long-term scalability. Building enduring market confidence necessitates rigorous commercial frameworks, advanced risk and fraud mitigation controls, standardized liability and dispute-handling procedures, and robust consumer protections.
As account-to-account recurring payments assume a more prominent role in the UK’s financial infrastructure, stakeholders emphasized that consumer trust must remain at the absolute center of design. Ensuring that end-users possess the same level of recourse and protection as they enjoy with credit cards or traditional banking instruments will be non-negotiable for future phases of market expansion.
The Broader Vision: Beyond Recurring Payments
At the dedicated UKPI exhibition stand, conversations revealed an enthusiastic appetite for the long-term roadmap of open banking innovation. Beyond the immediate focus on recurring billing for major online merchants anticipated for later next year, the broader vision articulated by UKPI leadership encompasses a much wider horizon.
The initiative’s strategic roadmap envisions seamless integration across various emerging payment typologies, including broader open banking A2A transfers, face-to-face point-of-sale transactions, and sophisticated agentic payments. As the financial services sector begins to contemplate the integration of smart contracts and autonomous, machine-driven commerce—where artificial intelligence agents manage subscriptions and execute micro-transactions on behalf of users—trusted, bank-authorized account-to-account infrastructure will serve as the indispensable plumbing.
As the UKPI transitions decisively from its formative launch phase into active market scaling, the organization continues to issue an open invitation for broader ecosystem engagement. By actively testing live use cases, refining commercial terms, and cementing operational and consumer safeguards, the initiative is actively shaping the next chapter of British financial history.
Industry participants and commercial enterprises seeking further information regarding the upcoming June 2026 launch and participation opportunities are encouraged to visit the official UKPI portal at www.ukpaymentsinitiative.co.uk.