The convergence of regulators, legacy banking institutions, agile fintech disruptors, and enterprise merchants at the Open Banking Expo UK & Europe 2026 marked a pivotal milestone in the evolution of the United Kingdom’s financial infrastructure. At the heart of this gathering was the UK Payments Initiative (UKPI), which utilized the platform’s Regulator Day and the broader conference schedule to drive substantive, cross-industry dialogue regarding the commercialization of variable recurring payments (VRP). As the financial sector gears up for the targeted June 2026 launch, stakeholders are increasingly focused on bridging policy intent with operational reality, ensuring that account-to-account (A2A) payment ecosystems mature in a secure, scalable, and consumer-centric manner.
Main Facts and the Drive Toward June 2026
The primary objective for UKPI at the 2026 expo was to anchor the commercial VRP conversation firmly within the broader context of the UK’s National Payments Vision. With regulatory frameworks continuing to evolve, the industry faces the complex task of establishing a viable commercial model that satisfies the economic expectations of participating banks while offering competitive, frictionless alternatives for merchants and third-party providers (TPPs).
The scheduled June 2026 launch date serves as the critical anchor for these efforts. Achieving this milestone requires intricate coordination across technical standards, scheme governance, risk management frameworks, and dispute-resolution protocols. By convening diverse market participants, UKPI’s presence at the expo underscored the reality that no single sector—whether traditional banking or emergent fintech—can build a nationwide payment scheme in isolation. The initiative’s collaborative framework is designed to align these disparate interests, establishing a unified foundation for recurring A2A payments that can ultimately rival legacy payment rails like Direct Debit and card networks.
Chronology and Background of the UK Payments Initiative
To understand the weight of the discussions at the Open Banking Expo, one must examine the trajectory of the UK’s open banking journey over the past two decades. The foundation was laid by the Competition and Markets Authority (CMA) Open Banking remedy, which mandated the UK’s largest nine banks to adopt standardized application programming interfaces (APIs). While initial phases successfully established read-access and single immediate payments, the subsequent ambition—moving into recurring payments and commercial VRP—proved technologically and commercially more intricate.
Recognizing the need for a dedicated, industry-led vehicle to shepherd this transition, UKPI was formed to take open banking principles out of the regulatory mandate phase and into a self-sustaining commercial environment. Over the preceding months, UKPI achieved a significant corporate milestone by closing its latest subscription period, securing 26 shareholders. This group now comprises 10 major banks and building societies, alongside a robust contingent of fintech organizations. This coalition provides the necessary market coverage and capital backing to ensure that the commercial VRP infrastructure is robustly funded and widely adopted from day one.
The Regulator Day Dialogue: Collaboration in Practice
A central highlight of the event was the Regulator Day panel discussion entitled “Delivering the National Payments Vision through industry collaboration: The case of commercial VRP.” Moderated by Claudio Pollack, independent non-executive chair at UKPI, the session assembled a cross-section of industry leaders: George Miltiadous, head of Open Banking at HSBC; Charles Damen, chief product officer at Token.io; Briony Krikorian-Slade, head of governance and strategy at UKPI; and Alex Kirykowicz, director at Frontier Economics.
The panel addressed the fundamental triad required for commercial VRP success: robust economic advice to shape a sustainable commercial model, refined technical standards, and an intuitive user experience. Opening the discussion, Pollack emphasized the practical nature of the initiative, noting that UKPI demonstrates how the market can leverage shared technical standards to translate high-level policy into active, live capabilities. He further affirmed UKPI’s long-term roadmap, stating that the organization plans to extend its framework into additional product categories beyond the initial rollout.
Economic and Operational Perspectives
A recurring theme throughout the expo was the granular economic calculus required to convince merchants to migrate payment volumes to commercial VRP. While traditional payment methods such as Direct Debit are often perceived as inexpensive for larger merchants, industry experts caution that headline costs do not tell the full story.
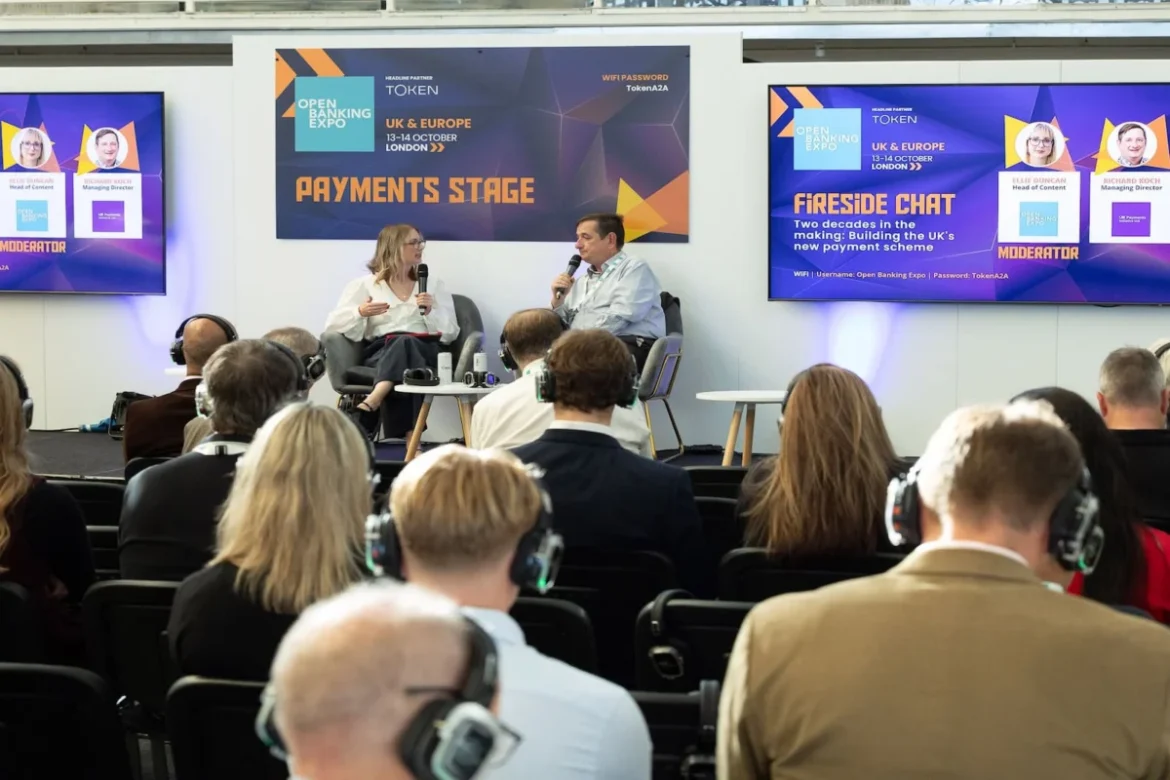
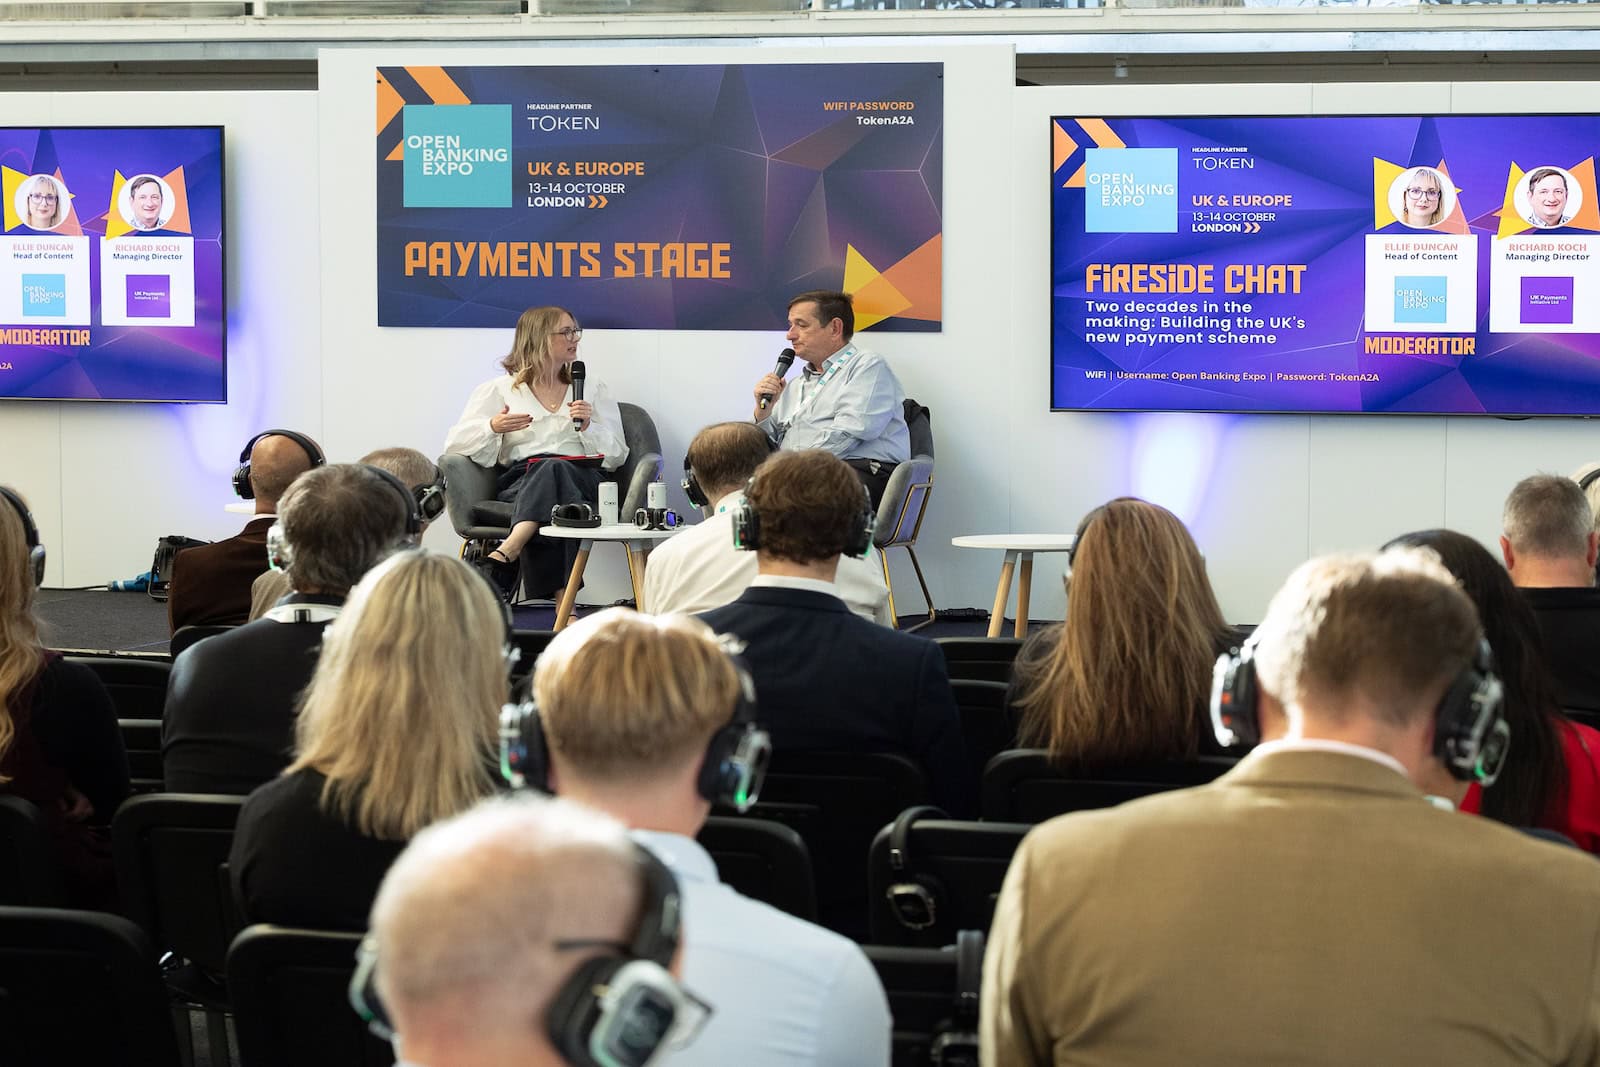
During a fireside chat titled “Two decades in the making: Building the UK’s new payment scheme,” UKPI managing director Richard Koch addressed this very friction. Koch pointed out that Direct Debit is only cost-effective when transactions execute seamlessly. In reality, the operational overhead associated with payment failures, indemnity claims, customer disputes, and exception handling can impose substantial hidden costs on businesses.
By contrast, commercial VRP offers real-time authentication, instant confirmation of funds, and significantly reduced fraud risks through strong customer authentication (SCA). Koch characterized UKPI’s deployment strategy as a deliberate “test and learn journey.” Rather than attempting a sweeping, high-risk rollout across the entire economy simultaneously, the initiative focuses on proving the economic and operational model through carefully selected Wave 1 use cases. This incremental approach allows stakeholders to gather empirical data from live implementations, iron out operational bottlenecks, and cultivate the market confidence necessary for long-term scaling.
Wave 1 Use Cases and Market Engagement
Sector-specific engagement at the expo was notably high, with stakeholders evaluating the readiness of Wave 1 use cases spanning utilities, telecommunications, transportation, financial services, government collections, and the charitable sector. These industries share a common operational need for reliable, recurring collections, making them ideal proving grounds for commercial VRP.
Conversations on the expo floor coalesced around two primary imperatives for Wave 1 success:
- Market Awareness and Value Proposition: Merchants and consumers alike must clearly understand the tangible benefits of switching to A2A recurring payments. Clear communication regarding cost savings, control, and security will be paramount to driving initial adoption.
- User Experience (UX) Consistency: To prevent drop-off at the checkout or setup stage, the user journey must be seamless, uniform, and frictionless across all participating bank interfaces. A fragmented UX risks undermining consumer trust before the scheme reaches critical mass.
Beyond immediate operational concerns, discussions also explored the foundational infrastructure required for future scaling. This includes robust risk and fraud mitigation controls, comprehensive liability frameworks, and transparent dispute-resolution mechanisms that protect consumers while providing legal certainty for merchants and banks.
The Broader Vision: Looking Beyond 2026
While the immediate industry focus remains squarely on the June 2026 delivery of commercial VRP, UKPI’s broader vision extends far beyond initial recurring collections. Interactions at the UKPI exhibition stand revealed considerable market anticipation for subsequent product phases.
Looking toward the horizon, market participants are already exploring how the underlying A2A payment architecture can be extended to support larger online enterprise merchants next year. Over the longer term, the roadmap anticipates applications in face-to-face retail environments and advanced digital paradigms such as agentic payments and smart contracts. These futuristic use cases highlight the expansive potential of trusted, bank-authorised A2A rails to redefine consumer journeys, enabling automated commerce where artificial intelligence agents securely manage transactions on behalf of users within strict regulatory and consent parameters.
Fact-Based Analysis of Implications
The structured transition of commercial VRP from a regulatory aspiration into an industry-delivered commercial reality carries profound implications for the UK financial landscape. For banks, participating in UKPI provides an opportunity to monetize open banking APIs and retain primary customer relationships in an increasingly disintermediated digital economy. For fintechs and TPPs, the establishment of standardized scheme rules lowers barriers to entry and fosters product innovation without the friction of bilateral negotiations with every individual banking institution.
For merchants, commercial VRP promises faster settlement times, lower processing costs relative to cards, and dramatically reduced fraud liabilities. However, the ultimate success of the initiative will depend on execution discipline. As UKPI transitions from conceptual design into active scale, maintaining alignment among its 26 shareholder institutions and the broader regulatory ecosystem will be vital. The “test and learn” philosophy advocated by leadership ensures that potential vulnerabilities can be identified and remediated in controlled phases, mitigating systemic risk.
Conclusion and Next Steps
The Open Banking Expo UK & Europe 2026 served as a crucial proving ground for the UK Payments Initiative, crystallizing industry-wide commitment to the June 2026 launch of commercial VRP. By successfully aligning banks, fintechs, merchants, and regulators around a shared commercial and technical framework, UKPI has established a collaborative blueprint for the future of British payments.
As the initiative moves from launch preparation into full operational scale, ongoing stakeholder engagement remains essential. The insights gathered at the expo reinforce that while the technical and commercial hurdles are complex, the collaborative momentum within the ecosystem has never been stronger. Organizations seeking to engage with the rollout, monitor live use-case developments, or contribute to the shaping of operational and customer protections are encouraged to visit the official UKPI portal at www.ukpaymentsinitiative.co.uk.