
Traditional financial institutions have long maintained a cautious distance from the creator economy, largely bypassing influencer marketing even as nimble fintech competitors like Current and Chime successfully capture these audiences. This widespread reluctance points to a deeper, more systemic issue within traditional banking: a fundamental lack of comprehension regarding how the creator ecosystem operates. Consequently, financial products tailored specifically to the unique lifestyle and operational needs of content creators remain scarce.
This oversight represents a significant missed opportunity for legacy banks and credit unions. The creator economy is expanding rapidly, driven by remarkably low barriers to entry, and is sustained by individuals who are intensely motivated by financial independence and stability. According to industry research, approximately 78% of people participating in the creator economy report that doing so directly helps them establish long-term financial stability. For forward-thinking financial institutions willing to adapt, this underserved demographic presents an array of solvable challenges. Similar to traditional small and medium-sized businesses (SMBs), creators require robust tools to manage their day-to-day operations and streamline invoicing and payments. Although major banks have developed comprehensive suites of products for conventional SMBs, the distinct characteristics of the creator economy—such as highly volatile payment schedules and deeply diversified revenue streams—demand a specialized, dedicated strategic approach.
Understanding the Reticence of Traditional Financial Institutions
To understand why traditional banks have been slow to enter this market, industry experts point out that the very attributes distinguishing creators from conventional small business owners also make them considerably more challenging to service from a risk-assessment perspective.
Influencers and content creators consistently fail to fit neatly into the rigid risk models that legacy financial institutions have relied upon for decades. Tachat Igityan, chief financial officer and founder of destream, a specialized financial platform for content creators, highlights the core structural misalignment. Traditional banks are fundamentally not structured to build products for creators due to the inherent instability of their income streams. Standard banking business models rely on servicing predictable, stable customers, such as salaried employees or brick-and-mortar business owners. Consequently, institutions often view digital creators as high-risk clients because applying traditional financial metrics—such as automated credit scoring, underwriting, lending, and long-term financial planning—proves exceedingly difficult.
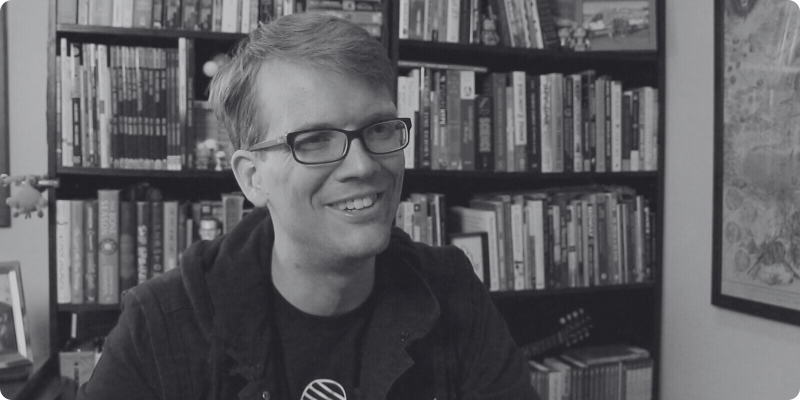
Compounding this structural hesitation is the vast diversity of needs within the creator community itself. Veteran YouTuber and digital entrepreneur Hank Green, author and founder of the crowdfunding platform Subbable—which was later acquired by Patreon—has frequently discussed the profound difficulties of building scalable products for this sector. Having considered developing creator-specific financial infrastructure during peak venture capital funding cycles, Green noted that creators possess such remarkably diverse needs that attempting to build a scalable product often results in failure. Crafting a solution that avoids excessive individualization costs while still serving the broad market frequently yields substandard products that fail to satisfy users.
Furthermore, the operational autonomy of content creators is heavily constrained by the immense power wielded by major social media conglomerates. Even highly experienced, professionally established digital creators frequently struggle to obtain clarity regarding their baseline earnings. Highlighting the opacity of platform payouts earlier this year, Green publicly noted the ongoing frustrations of relying on opaque algorithmic dashboards that fail to accurately report earnings, update financial ledgers in a timely manner, or consistently process correct currencies.
The Evolution and Growth of the Creator Economy
To contextualize the current banking gap, it is essential to examine the rapid evolution of the creator economy over the past decade and a half. The modern creator ecosystem began taking shape in the late 2000s, coinciding with the monetization programs launched by platforms like YouTube. Initially viewed as a hobbyist space populated by independent videographers, bloggers, and early social media personalities, the sector transitioned during the 2010s into a viable professional career path.
The proliferation of smartphones, high-speed mobile internet, and sophisticated, accessible editing software drastically lowered the barriers to entry. By the late 2010s and early 2020s, the global COVID-19 pandemic served as a major acceleration point. Lockdowns forced millions indoors, dramatically increasing digital consumption while simultaneously disrupting traditional employment markets. A massive wave of workers turned to content creation as a secondary income source or a full-time livelihood.
During this period of explosive growth, fintech startups recognized the opportunity early. Challenger banks and digital wallet providers began offering early access to earnings, customized debit cards, and streamlined expense tracking tailored to freelancers. However, legacy financial institutions largely remained on the sidelines, viewing the sector as a passing fad rather than a permanent pillar of the modern workforce. By the time venture capital funding peaked between 2020 and 2022, millions of creators were generating substantial revenue globally without access to institutional banking products that understood their cash flow cycles.
Why Creators Urgently Need Dedicated Financial Products
Given that financial motivations consistently rank as a primary driver for individuals entering the creator economy, the ongoing shortage of appropriate banking products actively prevents creators from fully capitalizing on their labor. At the center of these operational challenges lies the payments infrastructure.
Unlike traditional employees who receive predictable bi-weekly or monthly paychecks, or traditional retail businesses with steady point-of-sale transactions, content creators navigate a complex web of income sources. Their revenue streams typically comprise a mosaic of platform ad-revenue sharing, brand sponsorships, affiliate marketing commissions, direct fan funding via platforms like Patreon or Substack, merchandise sales, and live-streaming donations. Each of these revenue channels operates on entirely different payment cycles, ranging from net-30 or net-60 corporate invoice terms to delayed platform payout thresholds that can leave accounts uncredited for months.
This payment volatility creates cascading financial complications. When creators attempt to secure housing leases, auto loans, mortgages, or business lines of credit, traditional underwriting departments routinely reject their applications due to fluctuating month-to-month earnings reports. Standard credit-scoring algorithms fail to account for upcoming brand contracts or seasonal spikes in ad revenue, penalizing creators for an economic reality that is entirely normal within the digital media landscape.
The Economic Implications and Broader Market Opportunity
The reluctance of mainstream financial institutions to innovate within the creator economy carries significant economic implications for both the banking sector and the independent workforce. For banks, continuing to ignore this demographic means ceding an increasingly influential, digitally native customer base to agile fintech competitors and neobanks. As creators mature professionally and accumulate substantial wealth, the financial institutions that establish early trust and provide customized solutions will secure long-term loyalty.
Conversely, the broader market implications for creators are profound. Without institutional backing, creators face heightened financial vulnerability, paying higher fees for alternative financial products and struggling to manage complex tax obligations across multiple international jurisdictions. The lack of tailored accounting, invoicing, and tax-planning tools tailored to cross-border digital earnings limits the scalability of individual creator businesses.
Bridging the Gap: What Financial Institutions Must Do Next
Addressing the unique financial needs of the creator economy requires a fundamental pivot in how traditional banks evaluate risk and design products. Financial institutions must move beyond rigid, legacy credit-scoring models that penalize income volatility. Instead, progressive banks can develop dynamic underwriting frameworks that analyze a creator’s historical platform engagement, diversified revenue streams, and verified contract pipelines rather than relying solely on traditional tax returns or W-2 documentation.
Furthermore, integrating advanced cash-flow smoothing tools could help creators manage periods of low revenue by offering micro-lending products or advances tied directly to verified upcoming brand deals or platform payouts. By treating creators not as high-risk anomalies, but as the modern equivalent of small business enterprises, traditional financial institutions can unlock a massive, rapidly expanding market segment that is currently eager for reliable, institutional-grade financial partnership.
