
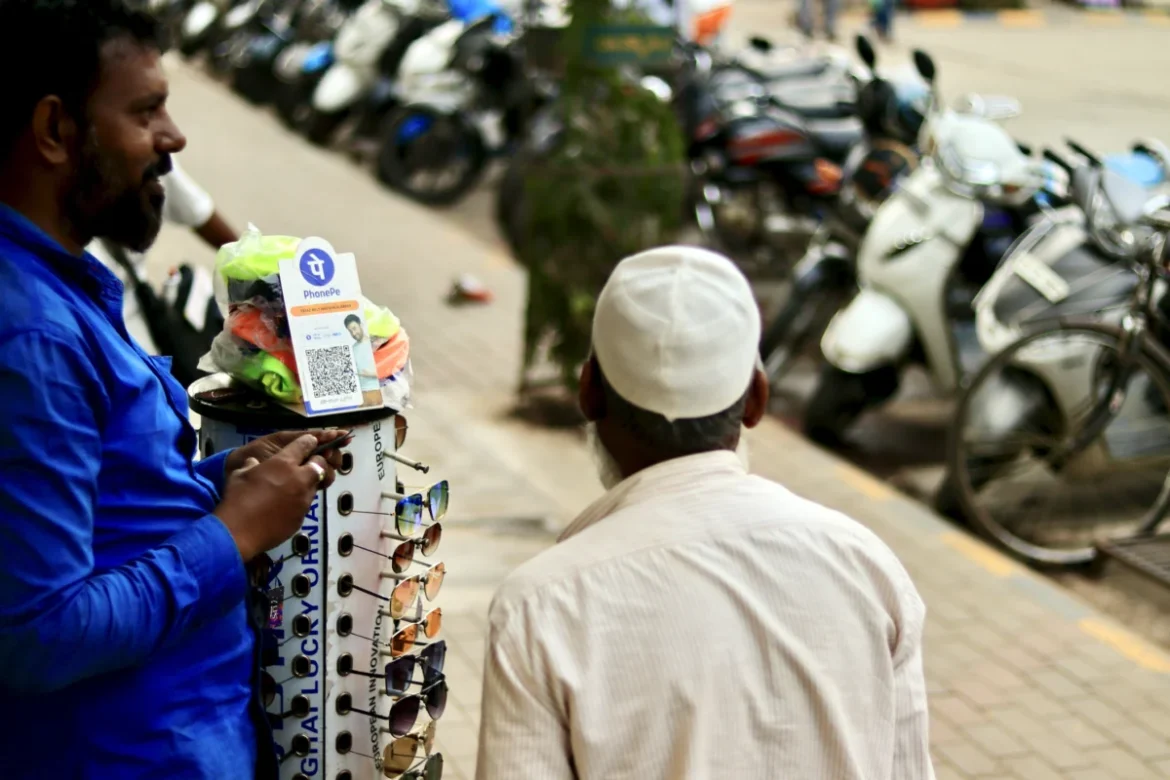
India has officially crossed a major Rubicon in its digital payments evolution, introducing a merchant discount rate for larger transactions on its ubiquitous Unified Payments Interface (UPI). After years of a strictly zero-fee regime that fueled exponential adoption and transformed daily commerce across the South Asian subcontinent, the National Payments Corporation of India (NPCI) has announced a 0.4% merchant fee on specific high-value payments exceeding ₹2,000, roughly equivalent to $21. This monumental structural adjustment, slated to take effect on October 15, is designed to transform the world’s most dynamic instant payments network into a financially self-sustaining ecosystem. While businesses handling substantial sums will now shoulder a nominal operational cost, individual consumers remain completely shielded, continuing to execute peer-to-peer and peer-to-merchant transfers without paying a single rupee.
The implementation of this fee structure follows months of intense deliberation within New Delhi’s financial corridors, industry advocacy groups, and banking boardrooms. For years, the total absence of a merchant discount rate (MDR) placed a heavy financial burden on the private and public sector banks, technology giants, and fintech aggregators that built, scaled, and maintained the underlying infrastructure. By authorizing a controlled fee framework, Indian regulatory authorities aim to secure the long-term viability of a network that handles tens of billions of transactions monthly, ensuring that innovation, cybersecurity upgrades, and capacity expansion can continue without relying exclusively on state subsidies or unsustainable corporate absorptions.
Chronology and Regulatory Evolution
The path toward monetizing high-value UPI transactions has been carefully orchestrated over several years, marking a strategic pivot from aggressive market acquisition to long-term economic consolidation.
In January 2020, to accelerate digital inclusion and diminish the dominance of physical cash, the Indian government scrapped merchant fees on UPI payments entirely. This bold regulatory incentive triggered a meteoric rise in adoption, turning neighborhood street vendors, auto-rickshaw drivers, and high-end luxury retailers alike into enthusiastic adherents of QR-code-based scanning. However, as transaction volumes swelled into astronomical figures, the infrastructure costs required to prevent system outages, thwart sophisticated cyber threats, and maintain lightning-fast settlement speeds escalated dramatically.
Recognizing the widening gap between operational expenditures and revenue, the Indian government laid foundational legislative groundwork in August by amending core payment laws to permit merchant fees on selective UPI transactions. This legal adjustment culminated in a formal notification issued on Monday, which explicitly barred banks from levying charges on UPI payments up to ₹2,000, thereby clearing a legal pathway for the newly minted fee schedule targeting larger commercial ticket sizes.
Detailed Breakdown of the Fee Structure
Under the newly released guidelines from the NPCI, the fee architecture is designed to protect micro-enterprises and everyday retail commerce while capturing value from larger corporate and institutional movements.
Transactions of ₹2,000 or less remain entirely free for merchants, preserving the friction-free experience for small-ticket purchases that dominate daily life. Furthermore, small merchants whose cumulative monthly UPI receipts do not exceed ₹100,000 (approximately $1,041) are fully exempt from the new charges. This specific exemption safeguards local mom-and-pop stores, street vendors, and independent service providers from unexpected overhead costs.
For transactions crossing the ₹2,000 threshold, a standard 0.4% merchant fee applies, though strict caps have been instituted to prevent excessive burdens on larger commercial exchanges. Specifically, the merchant fee is capped at a maximum of ₹300 (roughly $3) for transactions totaling ₹75,000 ($783) or more.
Specialized sectors have been granted tailored fee adjustments to accommodate unique industry operating margins. Key sectors including railways, telecommunications, insurance, and fuel will incur a flat fee of just ₹5 (about 5 cents) on UPI transactions exceeding ₹2,000. Meanwhile, capital-market transactions will attract a modest 0.02% fee, similarly capped at ₹300. To ensure market integrity and consumer protection, the NPCI has stipulated that merchants are strictly prohibited from passing these processing fees onto customers. Consumers will continue to pay the exact listed price for goods and services, regardless of their chosen payment mechanism.
Supporting Data and Scale of the UPI Economy
The urgency behind establishing a revenue model for UPI becomes glaringly apparent when examining the sheer volume and economic weight of the network. According to recent data published by the NPCI, UPI processed an astonishing 24.51 billion transactions in the single month of August, with a total monetary value reaching ₹29.9 trillion, equivalent to approximately $312 billion.
Industry estimates cited by the NPCI place the annual cost of operating, securing, and scaling this massive digital backbone at roughly ₹200 billion ($2.1 billion). These operating expenses encompass massive server capacities, round-the-clock fraud prevention mechanisms, advanced artificial intelligence monitoring, and continuous technical support needed to ensure near-zero downtime.
Comparatively, traditional payment methods have long operated under significantly higher cost structures. Standard credit card merchant fees in India typically range from 1.5% to 2.5% per transaction, while debit card fees are statutorily capped at 0.9%. Against this backdrop, UPI’s new 0.4% cap remains highly competitive, positioning it as an economical alternative for businesses even after the inclusion of processing charges. Moreover, transactions of up to ₹2,000 account for more than 95% of all UPI merchant transactions by volume, meaning the vast majority of daily retail interactions will remain completely untouched by the new financial framework.
Official Responses and Industry Implications
Reactions from financial experts, economists, and fintech executives highlight the delicate balancing act required when managing critical national financial utilities.
The newly announced merchant fees will be systematically distributed among the various participants in the UPI ecosystem—including issuing banks, acquiring banks, and application service providers. This financial distribution is expected to provide a much-needed revenue boost to prominent fintech firms and payment gateways such as Paytm, Pine Labs, Razorpay, and the IPO-bound PhonePe, all of which have invested heavily in building out the consumer-facing apps and merchant terminal hardware that make instant transfers possible.
Furthermore, a portion of the generated revenue will be channeled into a dedicated fund established in collaboration with the Reserve Bank of India over the next three months. This fund is explicitly earmarked for expanding digital-payment infrastructure, enhancing cybersecurity measures, and driving merchant adoption in India’s underserved tier-2, tier-3, and rural districts.
However, the policy shift has also generated intellectual debate regarding the philosophical nature of digital public infrastructure. Krishnamurthy Subramanian, a former chief economic adviser to the Indian government, has argued that systems like UPI yield broad societal benefits that extend far beyond direct transactional accounting. These include curbing the black economy, shrinking the physical cash footprint, and systematically formalizing unorganized business sectors. Writing on social media platform X, Subramanian posed a fundamental economic question: "The right question is: what is the opportunity cost of charging UPI transactions and what are its social benefits?"
This perspective underscores a lingering policy challenge: even as digital transactions surge, India continues to bear substantial macroeconomic costs associated with maintaining a massive physical cash network. Data from the Reserve Bank of India indicates that currency in circulation continues to grow at double-digit rates year-over-year, illustrating that cash remains an entrenched medium of exchange alongside digital rails.
Looking Ahead: The Market Test
As October 15 approaches, the true test of the new policy will unfold on the ground level. While the NPCI maintains that a 0.4% fee is marginal enough for businesses to absorb without altering consumer behavior, the ultimate outcome depends on how merchants with razor-thin profit margins respond. Observers will be closely monitoring whether commercial enterprises willingly absorb the new overhead or quietly seek ways to incentivize alternative payment methods for larger purchases. For now, India’s digital payments titan stands on the threshold of a new financial era, balancing the demands of fiscal sustainability with the imperative of maintaining the world’s most successful instant payment ecosystem.
