
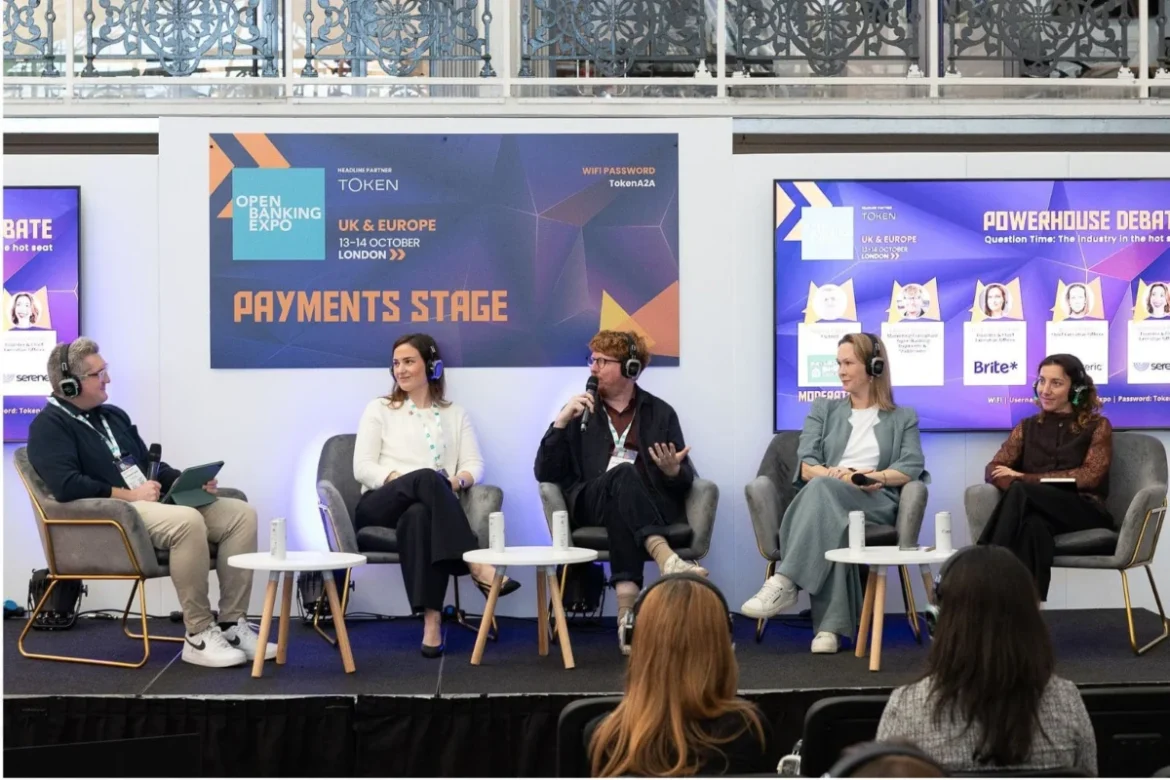
Commercial Variable Recurring Payments (cVRP) have entered a pivotal stage of development and deployment across the United Kingdom and European financial landscapes. Industry leaders convening at the Open Banking Expo UK & Europe 2026 underscored how this financial technology is poised to transcend its foundational use cases. By offering enhanced flexibility for everyday transactions, streamlined household financial management, and immediate liquidity for both merchants and consumers, cVRP represents a significant paradigm shift in how account-to-account (A2A) payments operate.
The widespread discourse surrounding cVRP at the premier industry event highlighted a collective optimism among fintech founders, payment architects, and banking executives. As discussions moved from theoretical capabilities to practical implementation, the overarching consensus pointed toward an imminent wave of mass adoption driven by technological maturation, evolving consumer expectations, and deepening collaboration between traditional financial institutions and nimble fintech enterprises.
Main Facts and the Evolving Landscape of cVRP
At its core, commercial variable recurring payments allow consumers to securely connect a third-party provider to their bank account to make recurring payments of varying amounts and frequencies, all within pre-agreed parameters set by the account holder. Unlike legacy mechanisms such as Direct Debits or standing orders—which are historically rigid regarding timing and exact amounts—cVRP introduces dynamic flexibility. This capability is fundamentally reshaping how consumers handle regular financial commitments.
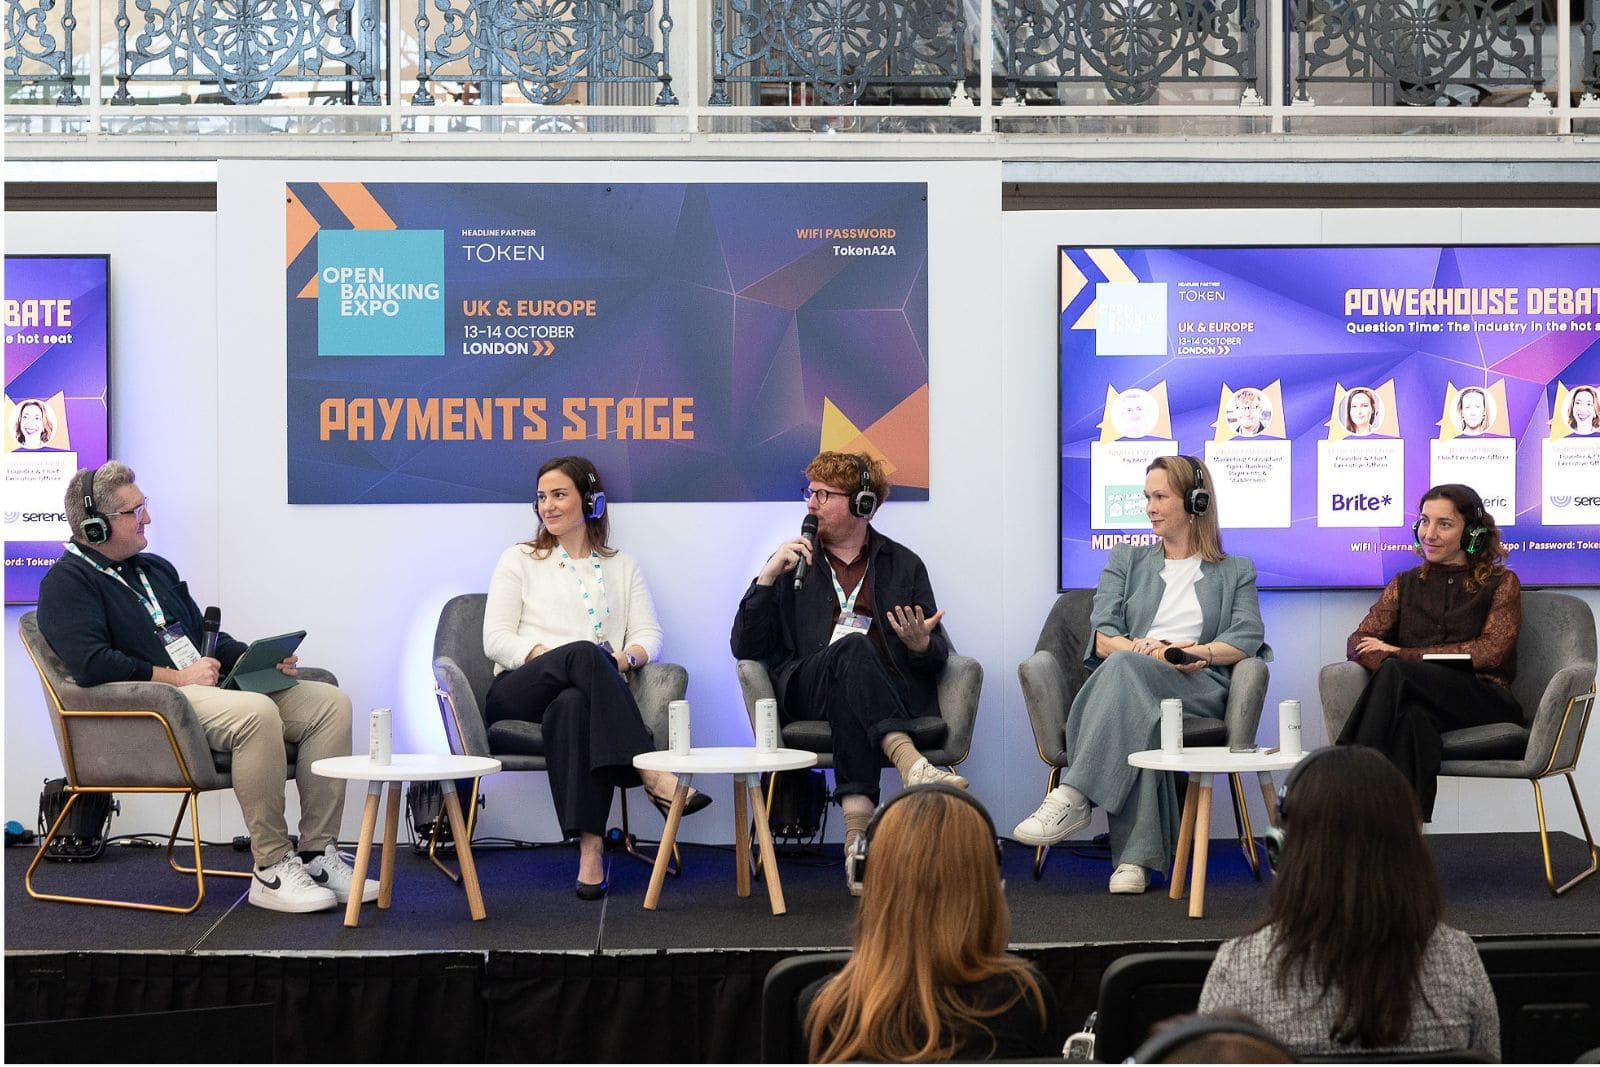
During the interactive session titled "Question Time: The industry in the hot seat" at the Open Banking Expo 2026, a panel of prominent payments specialists dissected the necessary prerequisites for achieving meaningful market scale. The conversation mapped out a roadmap where consumer trust, robust commercial incentives, and seamless technological integration serve as the primary pillars for widespread success.
Lena Hackelöer, founder and chief executive officer of Brite Payments, captured the prevailing sentiment of the delegation during her address. Expressing profound confidence in the trajectory of the technology, Hackelöer stated that the industry is "just on the brink of mass adoption." Her remarks reflect a broader market shift wherein open banking-powered payments are transitioning from alternative payment methods to mainstream financial infrastructure.
Background Context and Chronological Evolution of Open Banking
To understand the current momentum of cVRP, it is essential to examine the chronological progression of open banking frameworks. Following the implementation of the revised Payment Services Directive (PSD2) in Europe and the Competition and Markets Authority’s (CMA) Open Banking remedy in the UK, the initial focus centered heavily on account aggregation and basic payment initiation services (PIS).
During the formative years of open banking between 2018 and 2022, adoption was largely constrained by a lack of standardized commercial models. While traditional account-to-account payments proved effective for peer-to-peer transfers and single-ecommerce checkouts, recurring payments remained dominated by legacy card-on-file arrangements and Direct Debits. The introduction of sweeping reforms and voluntary agreements laid the groundwork for VRP, initially deployed for sweeping funds between a consumer’s own accounts.
The subsequent evolution toward commercial VRP—enabling payments from a consumer’s account to a business—marked a critical inflection point. By 2024 and 2025, regulatory bodies, working groups, and industry participants began laying the operational and commercial foundations required for cross-sector rollout. The discussions at the 2026 Open Banking Expo signify the maturity of these efforts, moving the conversation away from regulatory compliance toward consumer-facing utility and commercial viability.
Solving Real-World Friction in Household Financial Management
A primary highlight of the expert panels was the practical application of cVRP in solving long-standing consumer frustrations regarding household budgeting. Adam Chapman, an open banking, payments, and stablecoins marketing consultant, illustrated the limitations of legacy payment rails by focusing on routine civic obligations, such as council tax payments.
Chapman noted that traditional Direct Debit arrangements frequently bind consumers to rigid, inflexible payment dates. For households experiencing fluctuating income cycles—such as gig economy workers, freelancers, or salaried employees whose pay schedules shift due to weekends and holidays—fixed collection dates can precipitate inadvertent overdrafts or financial distress.
By leveraging cVRP, consumers gain the ability to align their regular financial obligations directly with their actual cash flow schedules. Because commercial VRP parameters can accommodate variable amounts and flexible timing within predetermined guardrails, customers retain absolute authority over their financial permissions while enjoying unprecedented adaptability. Chapman emphasized that cVRP effectively resolves these systemic timing mismatches, offering a modern solution to a legacy administrative problem.
The Multi-Dimensional Value of Instant Payments
Beyond the structural advantages of flexible scheduling, the panel evaluated the broader economic and operational efficiencies unlocked by instant account-to-account settlements. While early discussions surrounding open banking frequently championed transaction cost savings—principally by bypassing traditional card interchange fees—industry leaders increasingly point to speed and liquidity as the true catalysts for adoption.
Lena Hackelöer identified financial services and digital goods as prime sectors where instantaneous value transfer fundamentally enhances the user journey. For instance, in the realm of consumer lending, instant loan disbursements made possible by A2A rails eliminate the frustrating delays associated with legacy BACS or CHAPS processing times. Consumers receive approved funds immediately, transforming the borrowing and spending experience.
Echoing this perspective, Savannah Price, founder and chief chief executive officer of Serene, emphasized the critical importance of settlement velocity for both merchants and consumers. Price noted that the advantages of instant payments become exceptionally compelling when enhanced speed creates tangible improvements in a consumer’s immediate financial standing. For everyday shoppers, faster refunds translate to earlier access to working capital, significantly easing the friction typically associated with returns and exchanges.
Simultaneously, merchants benefit from immediate settlement. In an era where cash flow management is paramount for business survival, bypassing the multi-day clearing cycles inherent in legacy card processing allows enterprises to meet their financial obligations more efficiently, reduce working capital requirements, and mitigate the risk of settlement failures.
Overcoming Behavioral Barriers: Consumer Trust and Incentives
Despite the technical superiority and operational efficiencies of cVRP, the panel acknowledged significant behavioral hurdles that must be addressed to achieve critical mass. Adam Chapman observed that consumer habits are deeply entrenched. Individuals routinely default to familiar payment methods—such as traditional debit and credit cards—even when demonstrably superior alternatives are readily available.
Overcoming this inertia requires more than technological capability; it demands a strategic combination of compelling consumer incentives, frictionless user experiences, and unyielding institutional trust. Savannah Price reinforced this assertion, designating trust as the cornerstone of sustained adoption. Price noted that consumers must feel completely secure regarding the safety of their funds and possess a clear, transparent understanding of dispute resolution mechanisms if a transaction fails to execute as intended.
To bridge this confidence gap, fintech providers, banks, and merchants are tasked with designing intuitive, transparent customer journeys. Providing clear, easily digestible disclosures regarding permissions, revocation processes, and liability protections will be vital as open banking payments become increasingly ubiquitous in everyday commerce.
The Synergy of Fintech and Traditional Banking Collaboration
A recurring theme across the conference proceedings was the ongoing maturation of the relationship between legacy financial institutions and innovative fintech enterprises. Historically characterized by friction and competitive posturing, the modern financial ecosystem reflects a decisive shift toward collaborative ecosystem partnerships.
Savannah Price detailed how contemporary market dynamics encourage organizations to pool their respective strengths. By combining the vast customer reach, regulatory expertise, and foundational trust of traditional banks with the agile technology, user-experience design, and innovative architecture of fintechs, the industry can construct frictionless end-to-end payment journeys.
Adam Chapman further amplified this observation, highlighting the growing integration of fintech innovations directly into the product suites of established financial institutions. Rather than viewing traditional banking and financial technology as mutually exclusive entities, the panel concluded that the future of digital commerce relies upon symbiotic collaboration. This cooperative approach accelerates the development, distribution, and scaling of next-generation payment solutions like cVRP.
Fact-Based Analysis of Broader Implications and Market Outlook
The strategic implications of the widespread adoption of commercial variable recurring payments extend far beyond consumer convenience. From a macroeconomic perspective, the proliferation of efficient A2A payment rails has the potential to compress the total cost of payments within the global economy, reallocating billions of pounds in processing fees back into productive enterprise and consumer spending.
Furthermore, the integration of cVRP into utility billing, subscription services, insurance premiums, and governmental disbursements creates a unified standard for recurring digital commerce. As regulatory frameworks continue to evolve—particularly with ongoing initiatives regarding open finance in the UK and Europe—the technological boundaries separating traditional banking from digital ecosystems will continue to dissolve.
However, realizing this potential requires sustained vigilance. Industry stakeholders must navigate complex regulatory compliance requirements, establish robust standardized liability models, and maintain rigorous cybersecurity protocols to protect against emerging vectors of financial fraud. The collaborative posture exhibited at the Open Banking Expo 2026 suggests that the financial services sector is actively aligning to meet these challenges.
Conclusion and Future Trajectory
The dialogue at the Open Banking Expo UK & Europe 2026 solidifies the reality that commercial variable recurring payments are no longer a distant theoretical concept, but an active operational reality approaching a definitive inflection point. By fusing the administrative flexibility demanded by modern consumers with the settlement velocity and cost-efficiency required by enterprises, cVRP is uniquely positioned to redefine the parameters of recurring financial transactions.
As industry leaders chart the course for the next phase of open banking adoption, the combined forces of flexible customer permissions, instantaneous settlement, and fortified cross-sector collaboration will dictate the pace of market transformation. For consumers and businesses alike, the anticipated normalization of cVRP promises a future defined by greater financial control, reduced administrative friction, and a more resilient digital economy.
