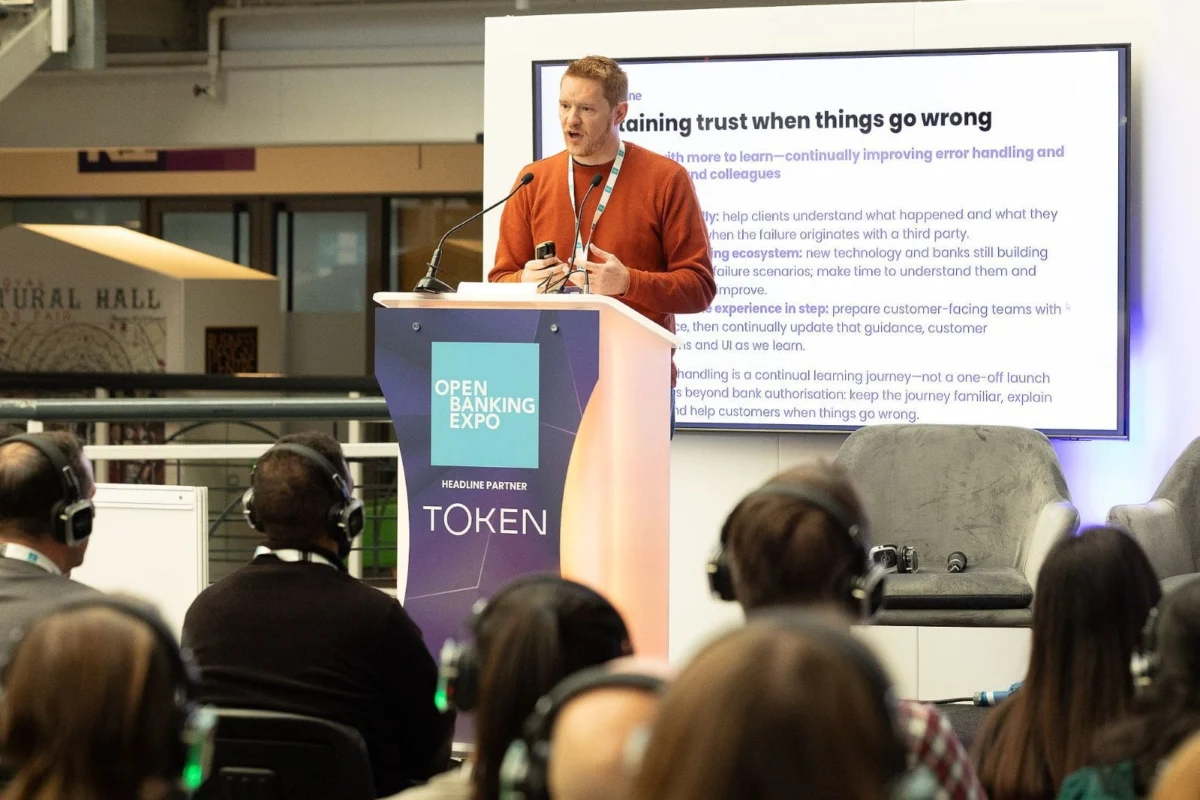
The landscape of digital wealth management and open banking experienced a significant milestone as investment platform InvestEngine revealed the exceptional performance of its newly integrated commercial variable recurring payments (cVRP) framework. Speaking at the prestigious Open Banking Expo UK & Europe 2026, Nick Ōen, Head of Product for Payments at InvestEngine, shared comprehensive data detailing the platform’s seamless transition to the next-generation payment method. Within a remarkably short four-month implementation window, the London-based investment platform successfully established approximately 13,000 commercial VRP mandates, achieving an unprecedented 98% payment-request success rate.
This early triumph provides the financial technology and open banking sectors with a robust, real-world case study. It demonstrates definitively how commercial VRP can transcend traditional sweeping use cases—such as moving money between a customer’s own accounts—and effectively power regular, automated investments where speed, reliability, and security are paramount.
Background Context and Strategic Evolution
To fully appreciate the magnitude of InvestEngine’s achievement, it is essential to examine the operational backdrop of the platform. Managing more than £3.5 billion in assets under management (AUM) on behalf of approximately 150,000 retail clients, InvestEngine has long prioritized technological efficiency to keep fees low and user experiences frictionless. Historically, the platform relied on a legacy combination of direct debit mandates and traditional sweeping VRP arrangements to facilitate regular customer deposits and portfolio contributions.
However, this hybrid approach introduced distinct friction points. Direct debit, while widely understood by consumers, is notoriously sluggish, often introducing frustrating multi-day settlement delays before funds are fully cleared and available for investment activities. Meanwhile, sweeping VRP—though significantly faster—was legally and functionally constrained primarily to moving funds between accounts held in the same person’s name, limiting its flexibility for broader commercial and recurring payment applications.
Recognizing these limitations, InvestEngine partnered with prominent open banking payments provider TrueLayer to overhaul its payment architecture. The strategic objective was clear: eliminate settlement lag, streamline the user journey, and create a unified, highly reliable recurring payment method that could rival or supersede debit cards and direct debits. By introducing commercial VRP, InvestEngine aimed to bridge the gap between instant account-to-account (A2A) payments and the automated convenience traditionally reserved for legacy payment rails.
Chronology of the Rollout
The integration of commercial VRP was executed through a carefully managed, phased implementation strategy designed to minimize operational risk and safeguard the customer experience. The rollout chronology unfolded as follows:
- Preparation and Infrastructure Design (Late 2025): InvestEngine collaborated closely with TrueLayer and major UK banking institutions to build the necessary infrastructure. Rather than forcing users onto an entirely unfamiliar payment pathway, the product team cleverly embedded the new open banking rails inside the platform’s existing, trusted savings and investment workflow. Customers were directed to authenticate payment mandates securely via their own banking apps before being seamlessly redirected back to the InvestEngine interface.
- Initial Phased Launch (Early 2026): The platform initiated its live rollout by onboarding new users onto the cVRP framework while simultaneously beginning the migration of existing clients who had previously relied on sweeping VRP. Initial integration efforts heavily engaged customers banking with major high-street institutions, including NatWest, Santander, HSBC, and Lloyds.
- Rapid Scaling and Mandate Milestone (Four Months Post-Launch): Within four months of going live, InvestEngine successfully established approximately 13,000 active commercial VRP mandates. The bulk of this early migration velocity was concentrated among customers utilizing NatWest and Santander, both of which had advanced open banking application programming interfaces (APIs) capable of supporting complex cVRP flows.
- The Open Banking Expo Reveal (2026): Presenting at the Open Banking Expo UK & Europe 2026, Nick Ōen formally published the preliminary performance metrics, highlighting the platform’s high conversion rates and setting a new benchmark for the broader wealth-tech sector.
Performance Data and Analytical Insights
The data presented by InvestEngine at the expo offers compelling quantitative evidence of commercial VRP’s superiority over legacy payment methods. Most notably, the platform recorded a 98% success rate across all payment requests executed via cVRP. This represents a statistically significant improvement over InvestEngine’s legacy sweeping VRP arrangements, which historically hovered around a 95% success rate.
Elaborating on these figures during his presentation, Ōen noted that out of every 100 payment requests dispatched by the platform via commercial VRP, an extraordinary 98 returned a positive, successful settlement confirmation. Furthermore, the platform observed an encouraging uptick in the average transaction value among customers who transitioned to the new rails, indicating that frictionless payment experiences may actively encourage larger capital allocations toward investment portfolios.
Despite these glowing metrics, InvestEngine maintained a rigorously objective analytical stance, cautioning industry observers against attributing the 3% performance boost entirely to technological superiority. During a Q&A session with expo delegates, Ōen suggested that demographic and behavioral variables played a substantial role. A significant portion of the early adopters were either newly onboarded customers or existing investors actively reauthorizing their payment parameters. Such cohorts typically exhibit higher levels of financial engagement and awareness, inherently reducing instances of failed transactions caused by insufficient funds or expired mandates.
Implementation Challenges and Technical Realities
While the quantitative results are overwhelmingly positive, InvestEngine’s leadership transparently addressed the operational hurdles encountered during the transition. Commercial VRP remains an evolving technology, and deploying it at scale across multiple legacy banking institutions is not without friction.
InvestEngine reported running into occasional technical roadblocks tied to individual banks rolling out their own backend cVRP capabilities. These hiccups occasionally manifested as customer-facing friction during the initial mandate setup phase. Ōen emphasized that fintech companies and merchants seeking to adopt commercial VRP must prepare robust operational contingencies. Successful deployment requires anticipating transaction failures, maintaining crystal-clear communication channels with end-users, and fostering exceptionally close coordination with open banking aggregators and participating retail banks to troubleshoot API discrepancies in real time.
Strategic Implications for Open Banking and Wealth Management
The implications of InvestEngine’s successful cVRP rollout extend far beyond a single investment platform, signaling a profound shift in how recurring payments may be handled across the United Kingdom and European financial ecosystems.
For the wealth management sector, the ability to execute instant, high-reliability recurring payments unlocks unprecedented operational efficiencies. Traditional reliance on direct debits exposes investment platforms to settlement risks and administrative overhead associated with unpaid items and chargebacks. By replacing direct debits with default commercial VRP rails, platforms like InvestEngine can grant customers immediate access to investment funds, eliminating processing lags and allowing investors to capitalize on market movements instantaneously.
From a consumer perspective, the transition aligns with modern expectations of digital financial services. By anchoring the advanced open banking rails within familiar, trusted user journeys, InvestEngine proved that complex back-end technological upgrades can be achieved without inducing cognitive load or anxiety for the end-user. As Ōen articulated during his keynote address, the ultimate measure of success for any payment innovation is not the sophistication of the protocol itself, but how seamlessly it removes barriers to customer intent: "The goal for us was never around the new payment technology. It’s around enabling customers to do what it is they want to do… quickly, simply, and confidently."
Future Outlook and Industry Trajectory
As InvestEngine looks toward the remainder of 2026 and beyond, the immediate operational challenge lies in scaling adoption across the remainder of its 150,000-strong client base. While 13,000 established mandates represent a phenomenal start for a four-month window, converting the broader mass of investors into active cVRP users will require continued education, user interface optimization, and further maturation of open banking infrastructure across tier-two and tier-three UK banking institutions.
For the broader financial services industry, InvestEngine’s pioneering deployment serves as a watershed moment. It bridges the theoretical potential of commercial variable recurring payments with hard commercial reality, proving that A2A payment methods can successfully displace legacy direct debit and card-on-file arrangements in complex, high-value vertical markets. As regulators, banks, and fintechs monitor these early results, the blueprint established by InvestEngine and TrueLayer is expected to accelerate the wider adoption of commercial VRP across subscription services, utilities, lending, and digital wealth management throughout the UK and Europe.