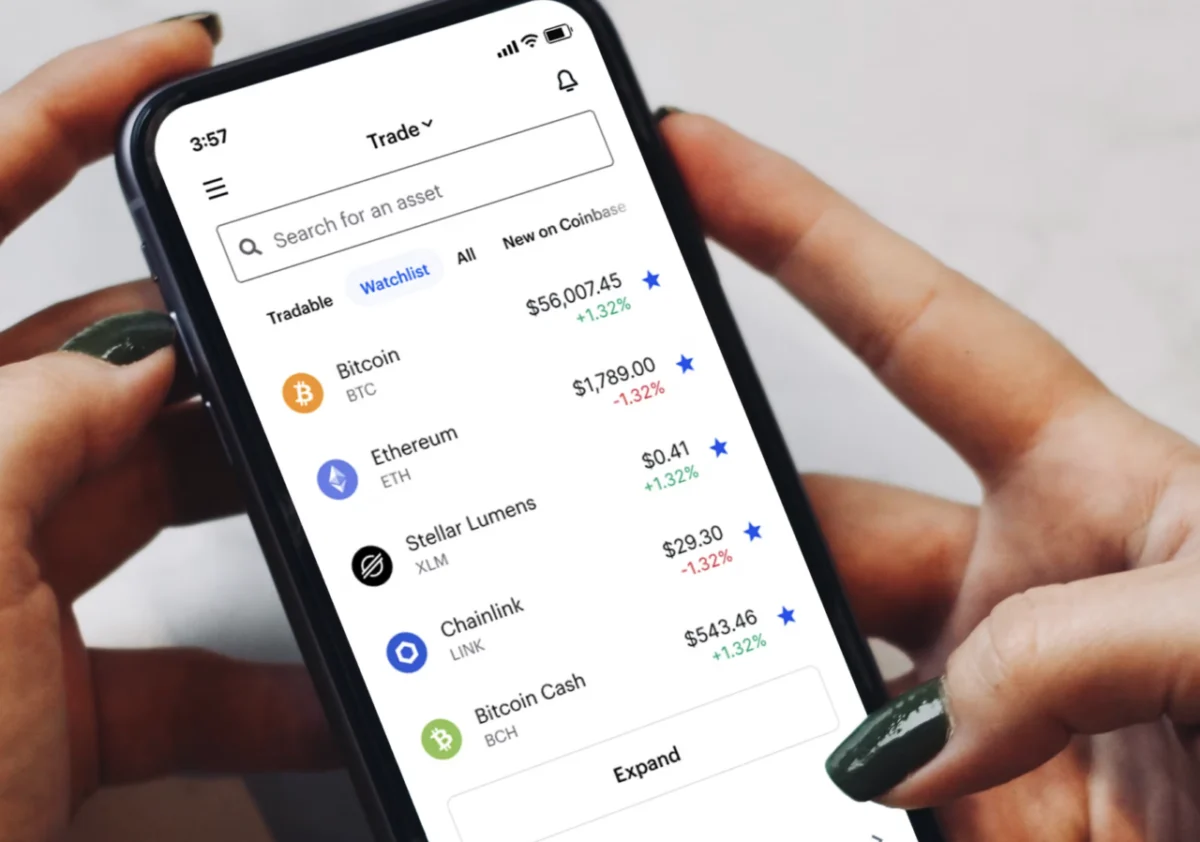
The intersection of traditional finance and the decentralized digital economy reached a significant milestone as cryptocurrency exchange giant Coinbase announced a strategic partnership with DeFi banking infrastructure provider Stablecore. This collaboration aims to bridge a critical gap in the financial services sector by enabling thousands of community banks, regional financial institutions, and credit unions to offer regulated digital asset products directly to their customers. Rather than forcing local financial institutions to undergo massive infrastructure overhauls or abandon their legacy core systems, the integration allows everyday bank customers to trade, hold, and interact with digital assets and stablecoins without ever leaving their trusted banking applications.
The initiative targets a network of more than 3,000 community banks and credit unions across the United States. Through Stablecore’s specialized, white-labeled integration layer, powered on the backend by Coinbase’s robust institutional infrastructure, these smaller institutions can roll out custody solutions, trading capabilities, and high-speed stablecoin payments under their own brand names. As consumer demand for digital assets continues to mature, this alliance provides localized financial institutions with the technological ammunition necessary to compete not only with mega-banks, but also with digital-first fintech platforms that have historically lured away tech-savvy consumers.
Background Context and the Evolution of the Partnership
For over a decade, the cryptocurrency and decentralized finance (DeFi) ecosystems operated largely in parallel to traditional banking infrastructure. Consumers wishing to purchase Bitcoin, Ethereum, or utilize stablecoins for transactions were forced to establish independent accounts with centralized exchanges like Coinbase or manage self-custody digital wallets. This created a fragmented financial experience where traditional checking accounts and digital assets remained siloed from one another.
Over the past several years, however, regulatory clarity surrounding digital assets has slowly evolved, creating pathways for regulated financial entities to explore blockchain-based technologies. Concurrently, community banks and credit unions have faced mounting pressure from younger demographics and digitally native customers who view crypto and stablecoins as essential components of modern financial management. Without access to these tools, local institutions risked losing crucial deposit relationships to competing fintechs and digital asset platforms.
Stablecore, established in 2025 as a specialized fintech firm based in Texas, emerged precisely to solve this dilemma. Recognizing that smaller institutions lack the engineering bandwidth and compliance budgets to build proprietary crypto infrastructure from scratch, Stablecore engineered a centralized middleware solution. By partnering with Coinbase—one of the most heavily regulated and liquid crypto platforms in the world—Stablecore has positioned its banking partners to bypass years of developmental hurdles and immediately deploy enterprise-grade digital asset services.
Chronology of Integration and Pilot Programs
The rollout of the Coinbase and Stablecore collaboration represents the culmination of months of backend engineering and regulatory compliance alignment.
- Early 2025: Stablecore is founded in Texas with a singular mandate: to build white-labeled, embedded fintech infrastructure tailored exclusively for community and regional banks and credit unions.
- Mid-2025: Initial technological frameworks are developed to securely connect traditional core banking systems with decentralized ledgers, emphasizing regulatory compliance, anti-money laundering (AML) protocols, and know-your-customer (KYC) standards.
- Late 2025 to Early 2026: Pilot programs are initiated with select forward-thinking regional institutions, most notably Amarillo National Bank in Texas. These trials test the seamless integration of tokenized deposits and stablecoin rails within existing retail banking dashboards.
- September 2026: Coinbase officially formalizes its partnership with Stablecore, scaling the infrastructure to over 3,000 community financial institutions and bringing institutional-grade digital asset capabilities to Main Street banking customers.
Supporting Data and Market Dynamics
The strategic timing of this partnership is underscored by broader macroeconomic shifts in global payments and consumer behavior. Stablecoins, in particular, have emerged as one of the fastest-growing sectors in financial technology, facilitating trillions of dollars in annualized settlement volume by offering instantaneous, low-cost cross-border and domestic transactions.
According to various financial market analyses, community banks and credit unions collectively hold trillions of dollars in total deposits across the United States. However, they have historically captured a minor fraction of the digital asset economy due to technological barriers. By integrating Coinbase’s deep liquidity and custody infrastructure through Stablecore, these institutions can theoretically recapture billions of dollars in transaction fees and asset management volume that otherwise leaks out of the traditional banking sector into standalone crypto applications.
Furthermore, white-labeled fintech adoption among community lenders has surged. Industry surveys indicate that over 65% of regional bank executives view digital asset integration as a crucial differentiator for customer retention, particularly among millennial and Generation Z account holders who routinely utilize multiple financial apps simultaneously.
Official Responses and Leadership Perspectives
Executives from both companies have emphasized that the partnership is designed to empower local institutions rather than disrupt them. By preserving the primary banking relationship, the initiative helps community lenders defend their turf against encroaching megabanks and agile fintech competitors.
"Community banks and credit unions shouldn’t have to choose between staying local and staying current," stated Alec Lovett, Head of Infrastructure Business at Coinbase. "Together with Stablecore, we are helping put them on the cutting edge of payments technology—cheaper, faster money movement, and the tools they need to stay strong for the communities they serve."
Lovett’s sentiments are echoed by the leadership team at Stablecore, who emphasized that the operational friction of updating core banking software has historically stifled innovation at the community level.
"Banks and credit unions should not have to move to completely new technology platforms to support digital assets for their clients," said Alex Treece, Co-Founder and CEO of Stablecore. "We built Stablecore to bring together all of the pieces so they don’t have to."
Amarillo National Bank, serving as an early commercial adopter of the technology, has praised the flexibility of the platform. By deploying the digital asset offering under its own proprietary brand, the Texas institution retains full ownership of client relationships, ensuring that underlying deposits and lending activities remain anchored within the local economy rather than migrating to external digital platforms.
Broader Industry Implications and Strategic Analysis
The Coinbase-Stablecore partnership highlights a fascinating shift in corporate strategy for major cryptocurrency exchanges. Historically, crypto enterprises operated with a strict ethos of disintermediation, striving to make traditional banking intermediaries obsolete. However, as the digital asset market matures, industry leaders recognize that mainstream adoption requires deep integration with existing financial structures rather than wholesale replacement.
By acting as an infrastructure provider behind the scenes, Coinbase is effectively executing a B2B (business-to-business) pivot alongside its consumer-facing exchange operations. In this model, Coinbase does not necessarily need to own the end-consumer relationship. Instead, it monetizes the underlying infrastructure, powering the digital asset engines for thousands of community banks. If a bank customer chooses to buy cryptocurrency or execute stablecoin transfers inside their local credit union app, Coinbase captures the transaction volume on the backend while the financial institution retains the customer loyalty.
For community banks and credit unions, the implications are equally profound. For decades, these institutions have struggled to match the massive technology budgets of Wall Street megabanks and well-funded Silicon Valley fintechs. By leveraging pre-packaged, compliant middleware from partners like Stablecore and Coinbase, smaller lenders can level the playing field.
As regulatory frameworks surrounding digital assets continue to solidify globally, the ability to offer tokenized deposits, secure crypto custody, and instantaneous stablecoin rails will likely shift from being a novel luxury to a mandatory baseline service for retail banking institutions. Through this collaboration, Main Street banking customers gain secure, regulated access to the future of finance without ever needing to leave the safety and familiarity of their local bank.