A coalition of federal lawmakers has introduced comprehensive legislation aimed at curbing the rising tide of staged motor vehicle accidents, a phenomenon commonly referred to as "crash for cash" schemes. The Stop Auto Fraud Act of 2026, unveiled earlier this month by Congresswoman Laura Gillen (D-NY-04) alongside Representatives Troy Nehls (R-TX-22), Josh Gottheimer (D-NJ-05), and Vince Fong (R-CA-20), seeks to classify the deliberate staging of automotive collisions as a federal crime. By imposing significant statutory penalties, including the potential for life imprisonment in cases involving death, the bill aims to address a systemic issue that has plagued both the insurance industry and public safety for over a decade.
The proposed legislation represents a significant shift in how the federal government approaches insurance-related crime. While individual states have long maintained their own statutes regarding insurance fraud, the Stop Auto Fraud Act seeks to establish a unified federal standard, providing law enforcement and federal prosecutors with broader jurisdiction to dismantle organized crime rings that often operate across state lines.
The Anatomy of "Crash for Cash" Schemes
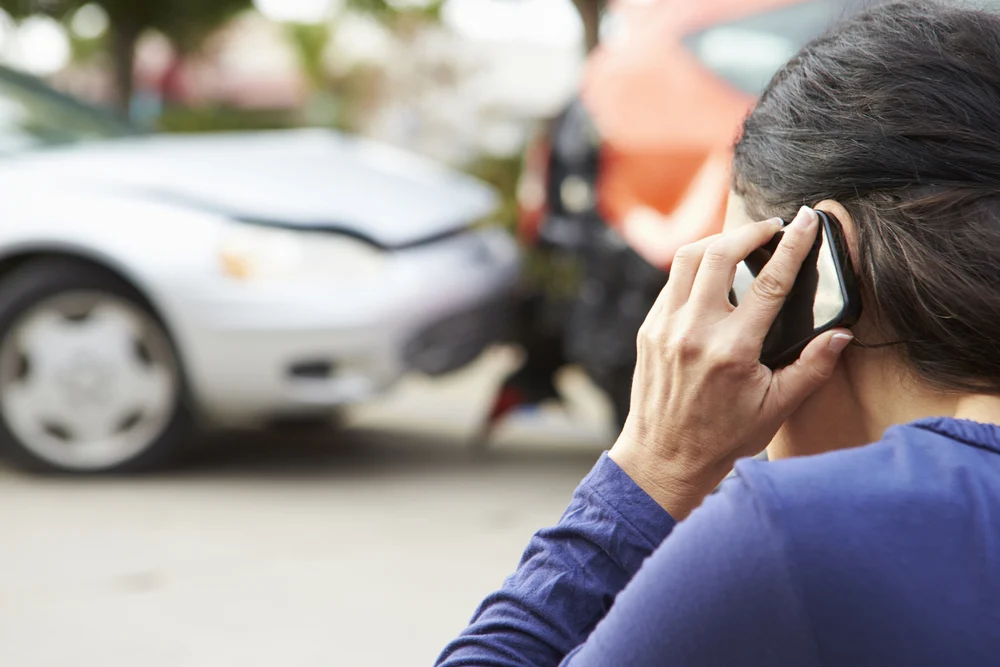
Staged accidents involve the deliberate orchestration of a collision to facilitate fraudulent insurance claims. These schemes typically fall into three primary categories: "swoop and squat" maneuvers, where one vehicle cuts off another to force a rear-end collision; "drive down" scenarios, where a fraudster waves a driver into traffic only to strike them intentionally; and "phantom" accidents, where claims are filed for damages that never occurred.
These acts are not merely financial crimes; they are inherently violent. Fraudsters often ignore the physical safety of their targets, utilizing high-speed maneuvers that frequently result in catastrophic injury or death. According to industry reports, these criminals have become increasingly sophisticated, employing spotters, lawyers, and even corrupt medical professionals to maximize the value of fraudulent claims. The involvement of these "facilitators" has turned a once-scattered nuisance into a multi-billion-dollar enterprise that directly impacts the premiums paid by every insured driver in the United States.
Chronology of an Escalating Crisis
The rise of staged accidents can be tracked alongside the increasing complexity of vehicle technology and the rising costs of medical care. Throughout the 2010s, insurance companies began to notice a pattern of repetitive claims involving the same medical clinics, law firms, and body shops.
- 2018–2020: Insurance regulators reported a steady climb in suspicious claims. The National Insurance Crime Bureau (NICB) identified "hot spots" for staged accidents in major metropolitan areas, particularly in New York, Florida, and California.
- 2020–2021: The COVID-19 pandemic caused a temporary dip in overall traffic; however, the proportion of fraudulent claims remained high. As traffic levels normalized in late 2021, the volume of reported staged incidents began to accelerate.
- 2023: A watershed year for data collection. The New York State Department of Financial Services recorded 38,270 incidents of suspected motor vehicle insurance fraud—a staggering 58% increase compared to 2020.
- 2026: The introduction of the Stop Auto Fraud Act marks the first major legislative attempt at the federal level to treat these incidents as a distinct, high-priority national security and public safety concern.
Data-Driven Economic Implications
The financial burden of these crimes is disproportionately shifted onto the American consumer. The NICB estimates that the average driver faces approximately $300 in increased annual insurance premiums directly attributable to the cost of fraudulent claims. When insurance carriers pay out on a staged accident, those losses are recouped through rate hikes across their entire policyholder base.
For the commercial trucking industry, the impact is even more acute. Because commercial vehicles are perceived as having "deep pockets" via corporate insurance policies, they have become the preferred targets of organized fraud rings. Large-scale freight operators have reported a significant increase in legal expenses and insurance premiums, costs that are eventually passed down to consumers through the rising prices of goods and services.
The Stop Auto Fraud Act addresses this by mandating that fines collected from successful prosecutions be funneled into the Highway Trust Fund. This provision creates a cyclical benefit: funds extracted from the criminals responsible for degrading road safety are redirected into infrastructure improvements, potentially lowering the frequency of accidents by enhancing road conditions.
Official Responses and Industry Support
The bill has received broad, cross-industry support, reflecting the consensus that existing state-level penalties are insufficient to act as a deterrent.
Congresswoman Laura Gillen emphasized the human and financial cost during the press conference announcing the bill. "Long Islanders pay some of the highest car insurance rates in the country, and ‘crash for cash’ schemes on our roads are driving rates even higher," Gillen stated. "When fraudsters stage car wrecks to scam their way to huge payouts, they’re putting lives at risk and forcing responsible drivers to bear the costs. I’m proud to lead this bipartisan bill to hold these criminals accountable."
Kyle McCollum, Vice President of the National Insurance Crime Bureau, praised the move as a long-overdue necessity. "Staged vehicle accidents are not harmless property crimes. These are violent offenses that put innocent drivers and pedestrians at risk of injury or worse—all so that fraudsters and their facilitators can cash in," McCollum said. He noted that the NICB has been advocating for more stringent, organized responses to keep pace with the increasingly professional nature of these crime syndicates.
The American Trucking Associations (ATA) also issued a strong endorsement. Alex Rosen, SVP of Legislative Affairs at the ATA, highlighted the vulnerability of commercial fleets. "On highways across the country, brazen criminals are intentionally colliding with other motorists in an attempt to score a big payday, and commercial trucks are a top target," Rosen said. "We need stronger penalties to deter those who perpetrate these schemes, which is why ATA strongly supports the Stop Auto Fraud Act."
Legislative Analysis and Future Prospects
The Stop Auto Fraud Act of 2026 proposes a tiered sentencing structure based on the severity of the incident. Under the current draft, the baseline penalties for staging an accident are significant, but the legislation mandates severe enhancements if the crime results in physical injury or death. In the most extreme scenarios, perpetrators could face life in prison, aligning the penalties for these "property crimes" with those for violent felonies.
The coalition backing the bill is extensive, including:
- The American Property Casualty Insurance Association (APCIA)
- The National Association of Mutual Insurance Companies (NAMIC)
- The American Bus Association
- The Truck Renting and Leasing Association
- The Coalition Against Insurance Fraud
- Various regional trucking associations, including those from New York, Texas, and the Southwest.
The Road Ahead: Challenges and Implications
While the legislation enjoys strong backing, it will face the standard scrutiny of the legislative process. Critics of federalizing such crimes often point to the potential strain on federal courts and the Department of Justice, which would be tasked with investigating and prosecuting cases that were previously handled by local district attorneys.
However, proponents argue that the complexity of modern fraud—which often involves interstate logistics, shell companies, and cross-border telecommunications—necessitates the resources and reach of federal agencies like the FBI and the Department of Transportation.
The enactment of this legislation would signify a major victory for consumer advocacy groups and insurance companies alike. If passed, the law will not only provide a more powerful tool for prosecution but will also serve as a signal to organized crime groups that the United States government is no longer willing to tolerate the victimization of its citizens on public highways.
As the bill moves through committee, the focus will likely remain on the balance between deterring organized fraud and ensuring that legitimate accident litigation—which is a necessary function of the legal system—is not inadvertently chilled. For the average motorist, the passage of the Stop Auto Fraud Act would represent a rare instance of federal policy directly addressing a daily frustration, promising a future of potentially lower premiums and safer roads.
The success of this bill will ultimately hinge on the ability of the bill’s sponsors to keep the bipartisan momentum alive in a divided Congress. With stakeholders from both sides of the aisle and diverse industries from trucking to insurance supporting the measure, the Stop Auto Fraud Act of 2026 stands as a significant piece of legislation to watch in the coming months. If the current trend of increasing fraudulent activity continues unabated, the pressure on legislators to pass the bill will only intensify, making it one of the most consequential transport-related legislative efforts in recent years.